Is Your Company Ready to Go Public? IPO Financial Readiness Gaps That Can Cause Delays

IPO financial readiness

Your business has been growing consistently. Sales are up, customers are coming back, and your leadership team is now discussing an IPO. That is when IPO financial readiness becomes a priority. If you are exploring IPO Services in India share the state of your financial records along, with your growth plans. Advisers need both to understand what is ready and what still needs work.

Someone wants to see the money that each customer owes. Another person is asking for the history of loans given by the owners. Your auditors are looking for proof of a change in accounting that happened two years ago. All a sudden going public doesn’t feel like starting a new chapter. It feels like opening every drawer and every box in the business. 

This is what being ready, for an IPO means: making sure that your financial information, your processes and your records can handle a look. Good sales help tell your story. Honest numbers help others check it. 

What Financial Gaps Can Delay a Company’s IPO? 

Financial gaps that can slow down the process of preparing for an IPO include accounting practices missing supporting documents, unresolved audit issues, poor visibility into cash flow, unclear transactions with related parties unbalanced tax accounts and plans for using the money raised that are not properly supported. 

The effect of each problem depends on what the problem’s how big it is and how much work is needed to fix it. Not all gaps stop an IPO from happening. Big issues can mean more analysis, more paperwork or more changes need to be made. 

Preparing the offer document, in India must follow the rules set by SEBI the requirements of the stock exchange and other relevant laws. The method used and the situation matters a lot. 

IPO Financial Readiness Starts Before the Filing 

It is tempting to treat financial preparation as something the finance team completes once management decides to list. 

In practice, finance depends on information held across sales, operations, procurement, legal and management. 

A customer contract may explain when revenue should be recognised. Warehouse records may support inventory figures. A board decision may explain a funding arrangement. 

Profitability and Readiness Are Different 

A profitable company can still have: 

  • Slow or unreliable monthly accounts. 
  • Unsupported adjustments. 
  • Poor visibility over collections. 
  • Incomplete group-company records. 
  • Informal financial approvals. 

These weaknesses do not disappear because the latest profit figure looks healthy. 

Financial preparation for an IPO means being able to explain how the numbers were produced, what supports them and which judgments were involved. 

If every question needs the founder to reconstruct an old conversation, preparation becomes harder. 

Financial Reporting Gaps That Create Extra Work 

Financial information used for an offer document may require preparation and examination beyond the company’s usual annual reporting exercise. 

The relevant framework can involve restated financial information, related-party disclosures and supporting information about funding arrangements. 

Inconsistent Accounting and Unsupported Revenue 

Suppose one business unit records revenue when an invoice is raised, while another waits for delivery or customer acceptance. 

The question is not which team’s spreadsheet looks cleaner. It is whether the accounting follows the applicable framework and the facts of the transaction. 

Review areas such as: 

  • Revenue recognition. 
  • Sales returns and credit notes. 
  • Rebates and discounts. 
  • Capitalised expenses. 
  • Inventory valuation. 
  • Provisions and estimates. 

Check whether invoices, contracts, dispatch records and acceptance evidence tell a consistent story.  Missing support can turn an apparently simple figure into a lengthy investigation. 

Unresolved Audit Issues 

Read past audit reports with your advisers. Identify qualifications and other reported matters that need assessment. 

Different audit matters have different implications. An emphasis-of-matter paragraph, for example, is not automatically an audit qualification. 

For each issue, establish: 

  • What was reported. 
  • Whether it remains unresolved. 
  • Whether figures or disclosures need attention. 
  • Who will complete the work. 
  • What evidence will demonstrate resolution. 

Avoid treating the audit report as a document that only matters at year-end. 

Cash Flow and Working Capital Questions 

“We are profitable” does not answer “Can we meet our obligations?” 

A business may report profits while customers take longer to pay, inventory builds up and suppliers shorten payment terms. 

Review: 

  • Receivables ageing and recoverability. 
  • Customer concentration. 
  • Inventory ageing. 
  • Supplier payment patterns. 
  • Seasonal funding needs. 
  • Short-term borrowing dependence. 

For example, a manufacturer may expect strong sales during a busy quarter but need cash for materials months earlier. 

A credible working-capital assessment should explain that timing. 

Improving IPO financial readiness therefore includes understanding where cash gets tied up—not simply presenting a forecast with a rising revenue line. 

Related-Party Transactions, Debt and Tax Exposure 

Some arrangements feel ordinary inside a closely held business. Outsiders may need a much fuller explanation. 

Transactions That Need Clear Documentation 

Perhaps a promoter owns the premises, a group company supplies materials, or another entity provides temporary funding. 

These arrangements need assessment, rather than assumptions that they are either harmless or automatically problematic. 

Prepare records covering: 

  • The parties involved. 
  • The commercial purpose. 
  • Pricing and payment terms. 
  • Outstanding balances. 
  • Agreements and approvals. 
  • Relevant accounting and disclosures. 

The applicable disclosure framework addresses related-party transactions and funding arrangements. 

Good IPO due diligence looks beyond a list of names. It examines how money, obligations and benefits move between connected parties. 

Obligations Missing From Management’s Picture 

Does the debt schedule capture guarantees and security arrangements? Are lender conditions being monitored? Do tax balances reconcile with returns and correspondence? 

Build a complete record of: 

  • Borrowings and repayment schedules. 
  • Security and guarantees. 
  • Covenant compliance. 
  • Tax notices and disputed demands. 
  • Relevant litigation. 
  • Potential obligations requiring assessment. 

Do not assume an old notice has become irrelevant because nobody followed up recently. 

The accounting treatment and disclosure response should be determined with the appropriate professionals. 

Weak Controls and Inconsistent Business Metrics 

A company cannot depend indefinitely on one person knowing which spreadsheet is correct.  Review how financial information moves through the business: 

  • Who approves payments? 
  • Who can change vendor details? 
  • Who reviews journal entries? 
  • How are bank accounts reconciled? 
  • Who checks inventory adjustments? 
  • How are access rights removed? 

Controls should fit the company’s size and risks. The objective is reliable reporting and clear responsibility. 

Business metrics deserve the same discipline. 

If management presents customer retention, order value or EBITDA, everyone should understand the definition and source. 

A metric used in a presentation should not quietly differ from the version used internally. Changes need explanation and appropriate review. 

Preparing a Credible Use-of-Proceeds Plan 

“We want to expand” is a starting point, not a complete funding plan. 

Where a fresh issue will raise money for the company, the proposed use needs appropriate support. An offer for sale involves selling shareholders and should not be confused with funds received by the issuer. 

Depending on the proposed objects, preparation may involve: 

  • Project estimates. 
  • Vendor quotations. 
  • Implementation schedules. 
  • Working-capital assumptions. 
  • Debt-repayment details. 
  • Dependencies and approvals. 

Public offer documents illustrate the use of supporting certificates and records for working capital and proposed objects. The exact requirements must be assessed for the issue. 

If a project budget changes, related figures and explanations may need updating too. Treat the plan as a connected set of assumptions. 

Turning Financial Gaps Into an Action Plan 

Start with a diagnostic review, rather than waiting for every document request to arrive. 

An effective IPO financial readiness plan assigns each issue: 

  • A clear description. 
  • Its potential impact. 
  • A responsible person. 
  • Required professional input. 
  • Supporting evidence. 
  • A target completion date. 

Prioritise work that affects other tasks. Resolving an accounting issue may be necessary before finalising related figures and disclosures. 

Then establish a controlled data room. Identify current versions, restrict access appropriately and track outstanding requests. 

IPO advisory services can help coordinate preparation within an agreed scope. Confirm who handles each workstream and which regulated or independent professionals must be separately involved. 

Keep management engaged. Advisers can identify gaps, but the company must supply records, make decisions and implement changes. 

Frequently Asked Questions

Can a Profitable Company Still Face IPO Delays?

Yes. Profitability does not resolve missing evidence, reporting inconsistencies, unresolved obligations or eligibility questions. Each needs separate assessment.

Do We Need to Resolve Every Receivable Before Filing?

Not necessarily. Assess recoverability, provisioning, concentration and disclosure under the applicable framework. Collecting every outstanding invoice is not a universal filing condition.

Does IPO Preparation Mean Rewriting Old Accounts?

No. Any adjustments or restated information must follow the applicable framework and professional examination. Preparation should explain and correct issues appropriately, not improve appearances.

How early should financial preparation start?

Start when an IPO becomes an important choice. The time needed depends on the records the group structure, the reporting systems and the problems that are found.

Will fixing gaps make it certain that the company gets listed?

No. Eligibility, regulatory checks, market situations and other things still matter. Better preparation makes things clearer; it does not promise a result.

Conclusion 

IPO financial readiness is about being able to support the story that the numbers tell. Look at the reports cash flow, arrangements with parties, obligations and controls before the deadlines start to feel urgent. Assign each gap to a person. Make sure there is proof of the work done. A company that knows its finances—and can explain them in a way—is, in a better position to handle the tough work that comes with becoming a publicly traded company.
IPO Services in India: Why Do Companies Need Professionals

IPO Services in India

Taking a company public is a decision. For business owners, a company going public represents years of work, business growth and the opportunity to raise money for future expansion. Launching an Initial Public Offering (IPO) is not as simple, as inviting people to invest in a company.  This is where IPO Services in India become important. 

There are records to review legal requirements to meet documents to prepare and important decisions to make about valuation and pricing. Even a established business can find the process challenging if company lacks the right guidance.

Professional IPO advisors help companies understand the process of going public get ready for rules and regulations work with legal experts and make smart choices before joining the stock market. 

For businesses thinking about an IPO getting help from professionals at a stage can stop extra problems and get them ready, for the duties of being a company that is listed on the stock market. 

What Are IPO Advisory Services? 

From my experience IPO advisory services guide companies in planning, preparing and managing every stage of going public. IPO advisory services are essential, for a transition. 

An IPO allows a company to sell its shares to the public for a period. Companies often think about an IPO when they need to raise money. An IPO can help a business grow, and gives owners a chance to sell shares. An IPO also makes it easier to reach capital markets. 

However going public also creates responsibilities. Companies must meet the requirements set by the Securities and Exchange Board of India (SEBI) stock exchanges and other relevant authorities. 

Professional advisors help businesses understand these requirements and coordinate the work to comply. 

What Does an IPO Advisor Actually Do? 

Depending on their expertise and engagement, IPO advisors may assist with: 

  • Assessing whether a company is ready for an IPO 
  • Reviewing financial and business information 
  • Identifying possible regulatory or compliance gaps 
  • Helping companies understand listing requirements 
  • Coordinating with merchant bankers, auditors, and legal professionals 
  • Supporting documentation and due diligence 
  • Assisting with IPO planning and timelines 
  • Preparing management for investor discussions 
  • Helping companies understand post-listing responsibilities 

It is important to know that an IPO consultant does not automatically have the authority to perform every activity. 

In India certain IPO‑related responsibilities must be handled by registered intermediaries, such, as SEBI‑registered merchant bankers. 

An IPO consultant can provide preparation and coordination support but regulated professionals carry out their respective statutory responsibilities. 

Why Do Companies Need Professional IPO Services in India? 

Every business has its own reasons for considering an IPO. 

Some companies want capital to open new manufacturing facilities. Others may be planning acquisitions, expanding into new markets, or reducing existing debt.  Whatever the objective, an IPO requires careful preparation.  Here are some important reasons companies seek professional support. 

1. Understanding Whether the Company Is Ready for an IPO 

One of the biggest mistakes a company can make is starting the IPO process before assessing its readiness. 

A business may be generating good revenue and growing steadily, but that doesn’t automatically mean it is prepared for a public listing.  Before moving forward, companies need to examine several areas. 

These include: 

  • Financial performance and reporting 
  • Corporate governance practices 
  • Business structure and shareholding 
  • Existing loans and liabilities 
  • Legal and regulatory compliance 
  • Internal controls and record-keeping 
  • Management experience 
  • Eligibility under applicable listing requirements 

For example, imagine a manufacturing company that has expanded rapidly over the last five years. 

Its sales are increasing, and management wants to raise capital through an IPO to build another factory. 

However, during an initial review, the company discovers that some corporate records need updating and certain financial reporting processes require improvement. 

Identifying these issues before formally beginning the IPO process gives the company time to address them. 

Professional advisors can help management understand which areas need attention and what preparations should come first. 

2. Managing Complex Regulatory Requirements  

Going public means stepping into a world. Companies that plan to go public in India need to pay attention to SEBI rules stock exchange rules, company law rules and other legal obligations. 

The exact rules they must follow depend on things like the type of stock exchange they want to list on, how strong their financial position. How they structure the offer. 

For instance the rules for a mainboard IPO are not the same as the rules, for an SME IPO. 

Businesses may need assistance understanding: 

  • Applicable IPO eligibility conditions 
  • SEBI disclosure requirements 
  • Corporate governance obligations 
  • Shareholding and promoter-related requirements 
  • Financial reporting standards 
  • Stock exchange listing procedures 
  • Regulatory filings and approvals 

Missing an important requirement can lead to additional questions, corrective work, or delays. 

This is one reason businesses explore IPO Advisory services in India before making major decisions about their proposed public issue. 

3. Preparing Financial Records and Business Documents 

Financial transparency becomes especially important when a company plans to invite public investment. 

Potential investors need reliable information to understand the company’s performance, financial position, risks, and future plans. 

A company preparing for an IPO may need to review and organize: 

  • Historical financial statements 
  • Restated financial information, where required 
  • Details of assets and liabilities 
  • Outstanding borrowings 
  • Related-party transactions 
  • Tax and statutory compliance records 
  • Material business agreements 
  • Litigation and contingent liabilities 
  • Promoter and shareholding information 

Consider a growing technology company that has received several rounds of private investment. 

Financial statements may be available. The company may still need to reconcile shareholder records review earlier investment agreements and organize information, about related-party transactions. 

These details matter during IPO due diligence. 

Advisors can help coordinate the collection and review of documents so that relevant professionals have the information they need. 

How Do IPO Advisory Services in India Help With Valuation and Pricing?

Valuation is one of the important decisions during an IPO.

A company naturally wants to achieve a valuation. At the time investors want to know if the proposed price truly reflects the business’s financial position, its growth potential and the risks involved. Finding the balance is not easy. It takes analysis and a clear understanding of what the business is worth. 

Understanding Business Valuation 

There are factors that can influence how a company is valued. These include earnings, revenue, market position, industry trends and future growth opportunities. Each of these plays a part in shaping the number. The more a company can demonstrate performance and long-term promise the higher the valuation may be. It’s not just about numbers. Confidence, from investors matters too. A company that shows stability and clear direction often gets value. 

These may include: 

  • Revenue and profitability 
  • Cash flow and financial stability 
  • Industry conditions 
  • Business growth opportunities 
  • Competitive position 
  • Comparable listed companies 
  • Management quality 
  • Market sentiment and investor demand 

For example, two companies operating in the same industry may generate similar revenue but have different valuations. 

One may have stronger profitability, lower debt, and more predictable cash flows. The other may be expanding quickly but facing higher operational risks. 

Investors may assess these businesses differently.  Professional advisors can help management understand the factors influencing valuation and prepare the information needed for discussions with the merchant bankers responsible for the issue. 

Why IPO Pricing Needs Careful Planning 

IPO pricing can affect investor interest and the amount of capital raised. 

A price that investors consider too high may reduce demand, while a lower price may not fully reflect the company’s expectations.  However, pricing is not determined by a consultant alone. 

The final approach depends on the offer structure, applicable regulations, market conditions, and the responsibilities of the appointed intermediaries. 

Professional guidance helps companies approach these discussions with better preparation and realistic expectations. 

How Does an IPO Consultant in India Support the Listing Process? 

An IPO involves several professionals working together.  Depending on the issue, these may include merchant bankers, legal advisors, auditors, registrars, bankers, and other intermediaries. 

For management teams handling everyday business operations, coordinating all these activities can become demanding. 

An IPO consultant may help organize the preparation process and improve communication between the company and its professional advisors. 

Coordinating Different IPO Activities 

Support may include: 

  • Preparing an IPO readiness checklist 
  • Organizing required company information 
  • Coordinating meetings with professional advisors 
  • Tracking documentation requirements 
  • Identifying pending compliance activities 
  • Monitoring preparation milestones 
  • Helping management respond to information requests 

For instance, a company’s finance team may be working with auditors while its legal team reviews material contracts. 

At the same time, the merchant banker may require additional business information. 

A structured coordination process can help everyone understand what needs to be completed and when. 

This doesn’t replace the responsibilities of regulated intermediaries. It helps the company manage its own preparation more effectively. 

Mainboard IPO vs SME IPO: Why Choosing the Right Route Matters 

Not every company follows the same path to the stock market.  In India, eligible companies may explore a mainboard IPO or an SME IPO, depending on their size, financial position, objectives, and applicable requirements. 

Mainboard IPO 

Mainboard listings are generally associated with companies seeking access to the broader public equity market. 

Companies must satisfy the applicable eligibility, disclosure, governance, and listing requirements. 

SME IPO 

SME platforms provide a listing route for eligible small and medium-sized businesses.  However, an SME IPO is not simply an easier version of a mainboard IPO. 

It has its own eligibility conditions, issue requirements, and continuing obligations.  Before choosing a route, companies should consider: 

  • Their current financial position 
  • Capital requirements 
  • Applicable eligibility criteria 
  • Listing and ongoing compliance costs 
  • Investor expectations 
  • Long-term business plans 

Professional advice can help management compare the available options without assuming that one route suits every company. 

Common Mistakes Companies Make Before Launching an IPO 

An IPO requires planning, and some problems begin long before the company files its offer documents. 

Here are several mistakes businesses should avoid. 

Starting Without a Clear Fundraising Objective 

A company should understand why it wants to raise money. 

Is the capital intended for expansion, debt repayment, working capital, or another permitted business purpose? 

Clearly defined objectives help the company explain its plans and assess whether an IPO is the right funding option. 

Ignoring Corporate Governance 

Public companies face greater scrutiny than many privately held businesses. 

Weak internal controls, incomplete records, and unclear decision-making processes can create concerns during IPO preparation. 

Underestimating IPO Costs 

The cost of going public extends beyond advisory fees. 

Depending on the transaction, expenses may include: 

  • Merchant banking fees 
  • Legal and audit fees 
  • Registrar and other intermediary charges 
  • Regulatory and stock exchange fees 
  • Advertising and communication expenses 
  • Ongoing compliance and reporting costs 

Businesses should evaluate these costs before committing to the process. 

Expecting Guaranteed Results

An IPO does not guarantee successful fundraising, strong investor demand, or an increase in share value after listing. 

Market conditions can change, and investors may respond differently from what the company expects. 

Professional advice helps companies understand these risks, but it cannot eliminate them. 

How to Choose the Right IPO Advisory Partner

Choosing an advisory partner is an important decision because IPO preparation can involve sensitive financial information and significant business changes. 

Before appointing an advisor, companies should ask a few practical questions. 

What Should You Look for in an IPO Advisor? 

Consider the following: 

  • Experience: Has the advisor worked on IPO readiness, capital market transactions or similar assignments? 
  • Understanding of regulations: Can the advisor explain the requirements clearly? 
  • Defined responsibilities: Which activities will the advisor handle directly and which require intermediaries? 
  • Transparent fees: Are the scope of work, charges and additional expenses clearly explained? 
  • Communication: Will management receive updates, on preparation activities? 
  • Practical guidance: Can the advisor identify business- issues rather than offering only a general checklist? 

A reliable advisor should also be clear about what they cannot guarantee.  Be cautious of anyone promising SEBI approval, guaranteed listing, or assured investor returns. 

What Happens After a Company Gets Listed? 

Many businesses focus heavily on getting listed but spend less time thinking about what happens afterward. 

In reality, becoming a listed company brings continuing responsibilities.  Depending on the applicable framework, these may involve: 

  • Periodic financial disclosures 
  • Corporate governance requirements 
  • Stock exchange reporting 
  • Disclosure of material events 
  • Shareholder communication 
  • Compliance with insider trading regulations 
  • Maintenance of appropriate internal controls 

For example a company that used to share updates with just a few shareholders might have to follow much more organized ways of sharing information once it goes public. 

Leaders need to get ready, for these duties before the public offering instead of waiting to deal with them later. 

Frequently Asked Questions About IPO Services in India

1. Why does a company need IPO services? 

IPO advisory services help a company check if it is ready to go public learn about the rules and laws that must be followed get the papers ready manage the work of different experts and get ready for the duties that come with being a public company. 

2. Is hiring an IPO consultant, in India?

Hiring a separate IPO consultant is not generally mandatory. However, an IPO requires the involvement of appropriate regulated intermediaries and professionals under the applicable framework. 

3. How long does the IPO process take in India? 

There is no fixed timeline for every IPO. The duration depends on company readiness, documentation, regulatory review, market conditions, and the proposed issue structure. 

4. Can a small company launch an IPO in India? 

Yes, an eligible small or medium-sized company may consider listing through an SME platform, subject to the applicable requirements. Not every small company will qualify.

5. What is the difference between an IPO advisor and a merchant banker?

An IPO advisor may support readiness assessment, planning, and coordination. A SEBI-registered merchant banker performs regulated responsibilities associated with managing a public issue, including applicable due diligence and offer-related activities. 

6. Can IPO advisors guarantee a successful listing?

No. Advisors cannot guarantee regulatory approval, investor subscription, listing success, or future share performance. 

Conclusion

Going public can create new opportunities for a growing company, but it also requires careful preparation and long-term responsibility.  From reviewing financial records and understanding regulations to evaluating valuation expectations and preparing for investor scrutiny, every stage deserves attention.  Professional IPO Consultant in India can help businesses approach these activities in a more organized way and identify potential issues before they become larger problems. Working with an experienced IPO consultant in India can also help management understand the available listing routes, coordinate preparation activities, and make informed decisions about the company’s future. 

An IPO is not just about raising capital. It’s about preparing your business for the expectations and responsibilities that come with public ownership.  The better prepared your company is before the IPO, the stronger its foundation will be for life as a listed business. 

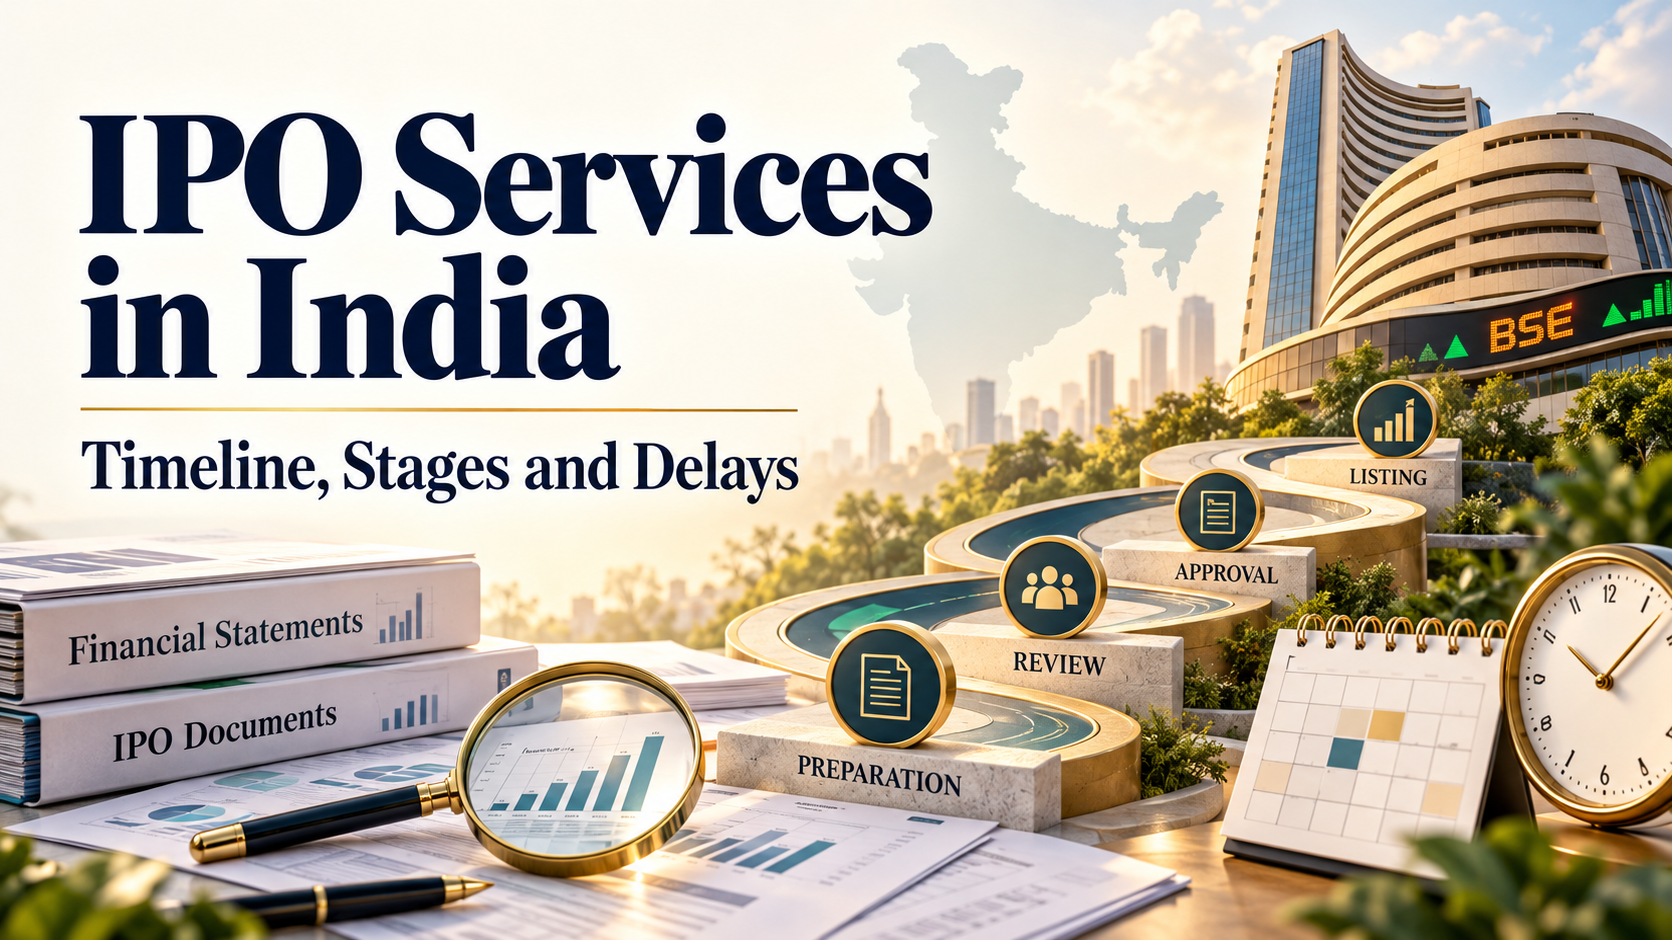
IPO Services in India: Timeline, Stages and Delays

IPO services in India

Once a company begins thinking about going public, the first question people usually ask is “When can we go public?” It makes sense. Leaders want to prepare for the money owners want to know for sure. Everyone needs a date to aim for. But before comparing IPO services in India, it helps to understand what that date depends on. The public offer is only the final stretch of a much longer project. 

Some companies arrive with organized records, clear ownership, and a team ready to answer questions. Companies that bring organized records show that they value order. Companies that have ownership never get lost in responsibility. Companies, with a team can respond quickly to any query. Other companies discover documents or unresolved compliance issues during preparation. Those differences can change the schedule considerably. 

A useful IPO timeline starts with the company’s current position. It should explain what needs doing, who will do it and what could hold things up. 

How Long Does an IPO Take in India? 

An IPO in India is generally a months-long project.  

There is no one end-to-end deadline that applies to every company. Companies that need a lot of preparation, changing their structure or fixing things they did wrong, may take much longer than companies that are already ready to file. Each company is different. Some are not prepared at all. Some are almost ready. The time needed depends on what each company has to do. Some have more work to do than others. That is why the timeline can be different for each business. 

The timetable after the public issue closes is much shorter. SEBI’s T+3 framework provides for listing within three working days of issue closure. That is the final listing stage—not the time needed to prepare and complete an IPO. 

When someone quotes a timeline, ask what they are counting from: 

  • The first readiness assessment? 
  • Appointment of the merchant banker? 
  • Filing of the draft offer document? 
  • Completion of the review process? 

An estimate becomes useful only when its starting point and assumptions are clear. 

What Happens Before a Company Can Launch Its IPO? 

Several teams work on an IPO together. Some tasks can move in parallel, while others have to wait for earlier work. 

1. Checking whether the company is ready 

Before setting a launch target, the advisers need to understand the business and assess the appropriate listing route. 

This means looking at: 

  • Applicable eligibility requirements. 
  • Financial history and reporting. 
  • Ownership and capital structure. 
  • Governance arrangements. 
  • Outstanding compliance matters. 
  • Funding needs and proposed use of proceeds. 

This review may reveal that the company is ready to proceed. It may also identify work that needs attention before filing. 

For example, strong sales do not compensate for unclear ownership records. Both need to be examined. 

2. Choosing the route and appointing the team 

SME and mainboard listings have different requirements. Choosing between them should begin with eligibility and suitability, rather than a promise that one will be quicker. 

The company then needs the appropriate advisers and intermediaries, including merchant bankers, auditors, legal advisers and a registrar. 

An IPO consultant in India may help with readiness and coordination. That role does not replace the responsibilities of the SEBI-registered merchant banker. 

Agree early on: 

  • Who manages the timetable. 
  • Who provides each set of documents. 
  • Who reviews the information. 
  • Who follows up on queries. 
  • Who resolves decisions requiring management approval. 

Without clear responsibilities, even straightforward requests can get stuck. 

3. Preparing financial information and completing due diligence 

This is where the preparation becomes detailed. 

The team examines financial information, corporate records, material agreements, litigation, licences and other matters relevant to the offer. 

Auditors and advisers may ask for evidence behind figures or statements management uses routinely. 

Suppose the company describes a customer relationship as long-term. The contract, however, allows the customer to leave at short notice. The offer document needs to reflect the agreement. 

Due diligence is about making sure the information can be supported, not simply gathering files into a folder. 

4. Drafting the offer document 

For a conventional mainboard IPO, the draft red herring prospectus, or DRHP, contains detailed disclosures about the company and proposed offer. 

These include: 

  • The business and its operations. 
  • Financial information. 
  • Risk factors. 
  • Promoters and management. 
  • Material litigation. 
  • The proposed use of funds. 

Drafting takes coordination. Finance, operations and management may describe the same issue differently, and those differences need to be resolved. 

Filing the draft is a significant milestone. It does not make the launch date certain. 

What Happens After the Draft Is Filed? 

The company moves into the applicable review process, followed by preparation for launch. 

Responding to questions 

SEBI and the stock exchanges may seek information, clarification or revised disclosures through their respective processes. 

A query can require input from several people. The lead manager may need an explanation from management, supporting records from finance and confirmation from an auditor. 

SME offer-document scrutiny follows the relevant exchange process under the applicable framework. It should not be treated as identical to the conventional mainboard route. 

This is why a review period should not be presented as a guaranteed countdown from the first filing. 

Getting ready to open the offer 

Once the relevant requirements have been addressed, preparation continues. 

The team may need to: 

  • Update disclosures and financial information. 
  • Complete offer documents and filings. 
  • Finalise the offer structure. 
  • Coordinate investor communication. 
  • Complete operational arrangements. 
  • Choose a suitable launch window. 

Being procedurally ready does not necessarily mean management will launch immediately. Investor feedback and market conditions still matter. 

Opening the issue and listing 

The public subscription window is measured in days. After closure, the intermediaries complete the applicable allotment, funds-unblocking, share-credit and listing steps. 

The T+3 framework provides for listing within three working days of closure. 

Working days are important. Holidays affect the calendar, so simply adding three ordinary days can give the wrong date. 

What Commonly Delays an IPO? 

Some delays are external. Others begin with information or decisions inside the business. 

Financial records need further work 

A company’s accounts may need reconciliations, explanations or supporting evidence before the offer information is ready. 

Common pressure points include: 

  • Revenue recognition. 
  • Related-party transactions. 
  • Outstanding balances. 
  • Subsidiary records. 
  • Missing documentation. 

If a figure cannot be supported, drafting faster will not solve the problem. The underlying records need attention. 

Shareholding records do not match expectations 

Historical allotments, transfers and approvals may need checking. 

For example, a founder may believe an investor holds a particular percentage, while the available records show inconsistencies. Advisers need to establish the correct position. 

Finding this early is far easier than discovering it when documents are almost ready. 

Management takes too long to respond 

The IPO team needs information from several departments. A request that looks small can stop progress if nobody owns it. 

Appointing an internal coordinator helps. Give that person: 

  • A document tracker. 
  • Named information owners. 
  • Response dates. 
  • Access to senior decision-makers. 
  • A way to escalate unresolved questions. 

Advisers cannot answer every business question on management’s behalf. 

The company changes its plans 

Management may revise the issue size, use of proceeds, selling shareholders or business structure.

Changes can be sensible. They still need to be assessed for their effect on disclosures, approvals and the schedule.

I would suggest asking that question before agreeing to a change of after the team has rewritten the documents. 

Pricing expectations differ from investor feedback 

I believe the valuation shareholders want may not match what investors are prepared to accept. 

That gap can lead to changes, in pricing, structure or timing. Advisers can help interpret demand. Cannot guarantee subscription or a favourable listing price. 

Waiting creates additional preparation 

A postponed launch may require refreshed financial information and updated disclosures. 

This can be frustrating: documents were completed, yet more work appears. But the offer needs to reflect the relevant position at launch. 

Build room for updates into the project instead of assuming preparation ends permanently with the first draft. 

Is an SME IPO Always Faster Than a Mainboard IPO? 

No. The routes differ, but neither guarantees a shortcut. 

An SME issue still needs applicable eligibility, financial preparation, due diligence, disclosures and arrangements such as market making. 

A mainboard company may have more complex operations, subsidiaries and documentation. It may also have a stronger internal team and better-organised records. 

The useful comparison is between the actual preparation required—not just the names of the platforms. 

For mainboard IPO advisory, ask the team to separate: 

  • Requirements already met. 
  • Tasks that can run together. 
  • Issues preventing filing. 
  • External review dependencies. 
  • Decisions needed before launch. 

That gives management a workable picture of the project. 

How Can a Company Reduce Avoidable Delays? 

You cannot control every review question or market movement. You can make your own preparation more dependable. 

Organise the data room properly 

Collect the relevant documents early: 

  • Corporate and ownership records. 
  • Financial information. 
  • Material contracts. 
  • Licences and approvals. 
  • Litigation information. 
  • Intellectual property documents. 

Use clear filenames and version control. Five different copies of an agreement create confusion; one verified version saves time. 

Keep management involved 

An IPO cannot be handed entirely to advisers. 

Schedule regular meetings focused on outstanding items and decisions. Senior management should resolve issues that departmental teams cannot. 

The aim is to remove obstacles, rather than repeatedly report that they exist. 

Plan around milestones 

Use milestones such as: 

  • Readiness review completed. 
  • Financial information prepared. 
  • Draft document filed. 
  • Review questions addressed. 
  • Launch arrangements completed. 
  • Offer opened and closed. 

Revisit target dates when assumptions change. An updated schedule is more useful than repeating a date that no longer reflects reality. 

What Should You Ask Before Hiring IPO Advisers? 

When comparing IPO services in India, request a plan based on your company’s records and circumstances. 

Ask:

  • What needs fixing before filing?
  • Which assumptions support the estimate?
  • Who will act as merchant banker?
  • What must management provide?
  • What could require updated documents?
  • How would delays affect costs?
  • What support continues after listing?

Be cautious about guaranteed listing dates. A credible team should explain both its responsibilities and the parts it cannot control.

Frequently Asked Questions:

Does T+3 mean an IPO takes three days?

No. It concerns listing after issue closure. Preparation, filing and review happen beforehand.

Can the issue open immediately after DRHP filing?

No. The company must complete the applicable review and launch requirements.

Does regulatory review guarantee a safe investment?

No. Review should not be presented as an endorsement of valuation, investment quality or future returns.

Can a company postpone its IPO?

Yes, subject to applicable validity and regulatory requirements. Updates or further filings may be needed.

Should a company depend on IPO proceeds for an urgent payment?

That creates timing risk. Assess suitable alternative funding rather than relying on an uncertain launch date.

Does preparation end on listing day?

No. Listed companies have continuing disclosure, governance and other compliance obligations. Plan for that transition before listing.

Conclusion 

A realistic IPO schedule comes from understanding what is prepared, what needs work and who is in charge of each part. A lot of the work takes place before investors see the offer so checking early can stop issues from appearing late. 

Before choosing a date ask an IPO consultant in India to show you the steps and the ideas behind the plan. You should leave with an idea of what your team has to do next what might change the plan and how you will track the progress.