Starting a business in India has become significantly more streamlined over the years, thanks to regulatory reforms like the Companies Act 2013. Among the various types of companies, a Private Limited Company is one of the most popular and preferred structures for entrepreneurs due to its benefits such as limited liability, separate legal identity, and ease of operations. In this blog, we will discuss the process of incorporating a Private Limited Company under the Companies Act 2013, and provide insights into Private Limited Company Registration in India, Pvt Ltd Company Registration in India, and more.
What is a Private Limited Company?
A Private Limited Company (Pvt Ltd) is a business entity that is privately held, with the liability of its shareholders limited to the amount of capital they have invested in the company. The key features of a Private Limited Company include:
Limited Liability: Shareholders’ liability is limited to the amount unpaid on their shares. This means personal assets are protected in case of business failure.
Separate Legal Entity: A Pvt Ltd company is legally distinct from its shareholders, meaning it can enter into contracts, own property, and sue or be sued in its own name.
Restricted Share Transfer: Shares of a private limited company cannot be traded on a public stock exchange, and their transfer is limited to specific rules.
Minimum Shareholders and Directors: A private limited company can be formed with just two shareholders and two directors, with a maximum of 200 shareholders.
Why Choose a Private Limited Company for Your Business?
Credibility: Having a Private Limited Company Registration in India boosts the credibility of your business, making it easier to attract investors, raise capital, and enter into partnerships.
Limited Liability Protection: Unlike sole proprietorships and partnerships, the shareholders’ personal assets are not at risk in the event of the company’s debts or liabilities.
Tax Benefits: A Pvt Ltd company is eligible for various tax exemptions and deductions under the Income Tax Act, which helps reduce the overall tax burden.
Ease of Fundraising: A Pvt Ltd company can raise capital through the issuance of shares to investors, which is not possible in other business structures like a partnership.
Incorporation of a Private Limited Company Under the Companies Act 2013
The Companies Act 2013 governs the incorporation and operation of companies in India. The process of incorporating a Private Limited Company involves several legal steps to ensure that the company is established as per the provisions of this Act. Here’s a step-by-step guide on how to register a company in India:
Step 1: Choose a Suitable Name for Your Company
The first step is to select a unique name for your Private Limited Company that complies with the guidelines set by the Ministry of Corporate Affairs (MCA). The name must not be identical to an existing company, nor should it infringe upon any trademarks. The name should also reflect the company’s business objectives.
Step 2: Obtain Digital Signature Certificate (DSC)
All documents related to Company Registration in India need to be signed digitally. Therefore, the directors and shareholders of the company must obtain a Digital Signature Certificate (DSC), which is issued by government-authorized certifying agencies.
Step 3: Apply for Director Identification Number (DIN)
The next step is to obtain a Director Identification Number (DIN) for all proposed directors of the company. DIN is a unique number issued by the Ministry of Corporate Affairs, which is mandatory for anyone wishing to act as a director in an Indian company.
Step 4: Draft the Memorandum and Articles of Association (MOA & AOA)
The Memorandum of Association (MOA) defines the company’s objectives, while the Articles of Association (AOA) lays down the rules and regulations for its internal management. These documents must be drafted and signed by the directors and shareholders.
Step 5: Filing the Incorporation Application
Once the MOA and AOA are ready, the incorporation application is filed with the Ministry of Corporate Affairs (MCA) through the MCA portal. This is done by submitting the necessary forms, including SPICe+ (Simplified Proforma for Incorporating Company Electronically), which covers multiple services like name reservation, incorporation, and PAN and TAN applications.
Step 6: Issuance of Certificate of Incorporation
Once the application is verified and approved, the Registrar of Companies (RoC) will issue a Certificate of Incorporation, confirming the legal existence of the company.
Key Documents Required for Private Limited Company Registration
To register a private limited company, certain documents must be submitted, including:
Proof of Identity: PAN card, Aadhar card, passport, or voter ID of the directors.
Proof of Address: A recent utility bill or rental agreement for the registered office address.
Photographs: Passport-sized photos of all directors.
MOA & AOA: The company’s memorandum and articles of association.
DIN & DSC: Director Identification Number (DIN) and Digital Signature Certificate (DSC) for all directors.
How to Register a Startup Company in India?
Startups looking to incorporate a Private Limited Company have a simplified process through the Startup India initiative. This program offers various benefits, such as tax exemptions and easier compliance, for eligible startups. The registration process remains the same, but certain benefits are available to encourage innovation and entrepreneurship.
Register as a Startup: A company must be recognized as a startup by the Department for Promotion of Industry and Internal Trade (DPIIT).
Tax Exemptions: Eligible startups can avail of income tax exemptions for the first three years.
Simplified Compliance: The startup scheme offers easier regulations, allowing for fewer compliance requirements in the initial years.
Company Registration Online in India
With the increasing digitization, registering a company in India has never been easier. Company Registration Online in India is a hassle-free process that can be done from the comfort of your home or office. By visiting the MCA portal, entrepreneurs can submit their forms, track the progress, and complete the registration process online. The Company Registration Online in India system has significantly reduced paperwork and made the process faster and more efficient.
Conclusion
Incorporating a Private Limited Company under the Companies Act 2013 offers significant advantages to entrepreneurs, including limited liability protection, ease of raising capital, and enhanced credibility. If you are considering starting a business, the Pvt Ltd Company Registration in India is the ideal route for you. With the option to register a company in India online, the process has been made simpler and more efficient than ever before.
If you’re unsure of the procedure or need assistance, seeking professional advice from experts in Company Registration in India and Private Limited Company Registration in India can make the process smoother. Whether you’re a first-time entrepreneur or a seasoned businessperson, registering a startup company in India has never been more accessible.
Take the first step today and register your company in India to bring your entrepreneurial dreams to life!
India’s investment landscape has undergone a significant transformation over the last few decades. Traditional investment avenues like fixed deposits and public sector bonds are now complemented by a host of innovative investment options, one of the most popular beingAlternative Investment Funds (AIFs). These funds have grown in importance due to their ability to provide higher returns through investments in unlisted securities, private equity, hedge funds, venture capital, real estate, and other non-traditional assets.
However, in order to operate legally and attract investors, an AIF must be properly registered with the Securities and Exchange Board of India (SEBI). The registration process, though rewarding, can be complex, and it’s essential to understand the steps involved in the AIF Registration in India. In this blog, we’ll explore the process of AIF Registration Online in India, the categories of AIFs, and how an AIF Registration Consultant can help streamline the registration process.
What is an Alternative Investment Fund (AIF)?
An Alternative Investment Fund (AIF) is a privately pooled investment vehicle that collects funds from investors and makes investments in assets that are not typically available through conventional investment options like mutual funds or stocks. AIFs are designed to invest in ventures, assets, and projects that may be high-risk but also have the potential for high returns.
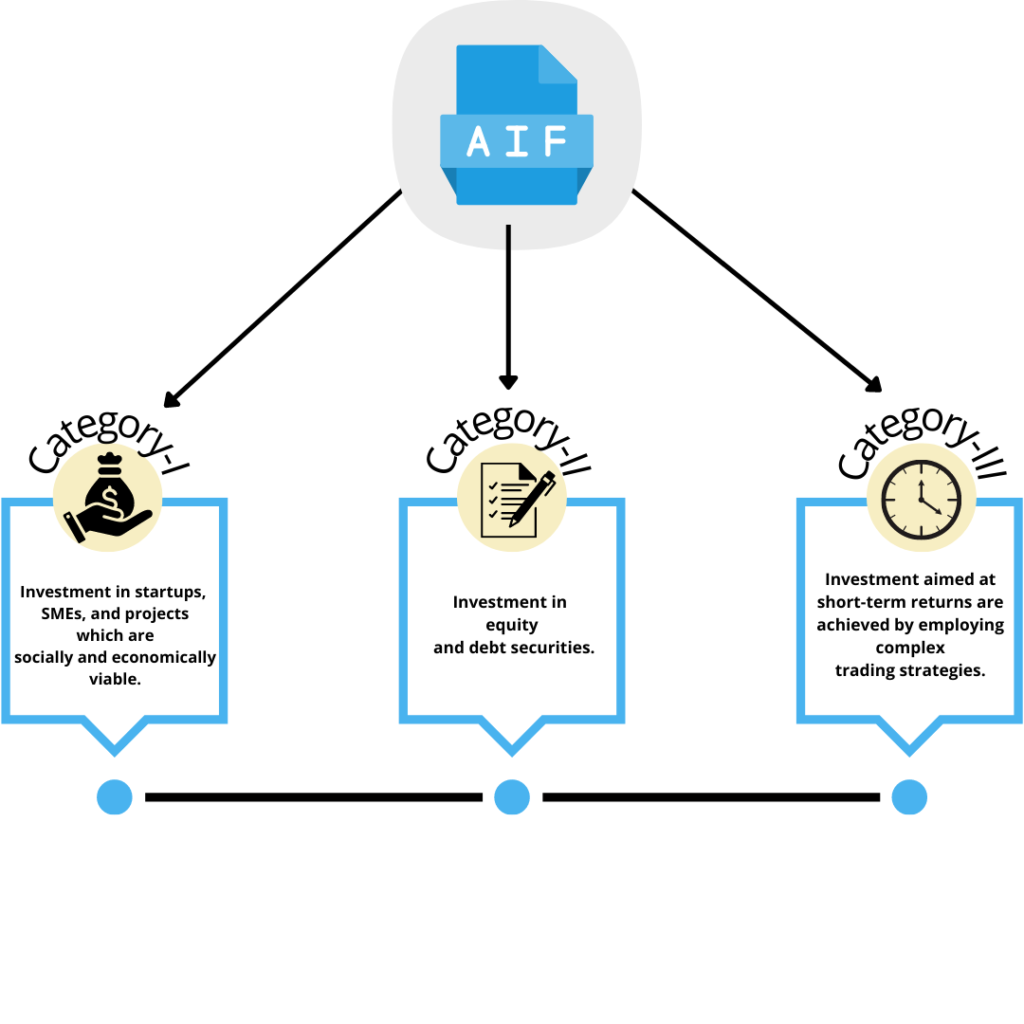
There are three categories of AIFs as regulated by SEBI:
Category I AIFs: Funds that invest in sectors or areas that are considered economically and socially beneficial, such as venture capital funds, social venture funds, and infrastructure funds.
Category II AIFs: Funds that do not take excessive risks and do not use leverage in their operations, like private equity funds and debt funds.
Category III AIFs: These include funds that employ complex strategies and use leverage for higher returns, such as hedge funds.
Why is AIF Registration Necessary in India?
For an AIF to raise capital, invest on behalf of investors, and manage assets, it needs to be registered with SEBI. TheAIF Registration in India serves to:
Ensure transparency and accountability in the functioning of the fund.
Safeguard investor interests by enforcing strict regulatory norms.
Enhance credibility by ensuring compliance with Indian laws.
Without proper registration, any fund offering investments as an AIF will be considered illegal and cannot legally raise funds from investors. Therefore, the AIF Registration Process is essential for establishing the fund’s credibility and operational legality.
Steps to Register as an AIF in India
The process of AIF Registration Online in India follows a set sequence, requiring thorough documentation and compliance with SEBI’s regulations. Let’s break down the major steps involved in AIF Registration in India.
1. Determine the Type of AIF
Before proceeding with AIF Registration Online in India, the first crucial step is deciding which category of AIF best fits your fund’s objectives and strategies. Here’s a brief overview:
Category I AIFs: These include funds that support new ventures, social causes, and infrastructure projects. This category usually benefits from some tax advantages and lighter regulatory scrutiny.
Category II AIFs: Funds in this category invest in private equity or debt instruments and employ moderate risk. These funds are required to adhere to more stringent norms.
Category III AIFs: These funds use leverage, short-selling, and other complex investment strategies to maximize returns, usually targeting sophisticated investors.
Choosing the right category is critical because it impacts the structure, investment policies, risk factors, and regulatory requirements that will apply to the fund.
2. Understand the Eligibility Criteria for AIF Registration
To qualify for AIF Registration in India, the fund must meet certain eligibility requirements. These include:
Fund Manager Requirements: The fund manager must be a registered entity, typically a company, and must possess relevant experience and qualifications to manage an AIF.
Minimum Investment Requirement: The minimum corpus for an AIF is generally ₹20 crore. However, the total corpus may vary depending on the category and other specific criteria.
Investor Requirements: An AIF can only accept funds from certain types of investors, typically high-net-worth individuals (HNIs) or institutional investors.
In addition, the fund must have clear governance, risk management policies, and a defined investment strategy.
3. Prepare the Documentation
The AIF Registration in India requires a comprehensive set of documents to be submitted to SEBI. These typically include:
Constitutional Documents: The memorandum of association (MOA), articles of association (AOA), and partnership deed (for a limited liability partnership or LLP).
Details of the Fund Manager: The qualifications and professional background of the fund manager and the management team.
Investment Strategy and Policies: A detailed outline of the fund’s investment approach, including target sectors, asset allocation, and risk management strategies.
Financial Statements: Projections of the fund’s financial performance, including balance sheets and profit & loss accounts.
Once the documentation is ready, it must be submitted to SEBI through their online platform.
4. Registering the AIF Online with SEBI
The next step is to proceed with Online AIF Registration in India. SEBI has set up a dedicated online portal for AIF registration, making it easier to submit applications and documents. Here’s how you can proceed:
Create an Account: Visit the SEBI website and create an account with the appropriate login credentials.
Submit the Application Form: Complete the online application form, providing accurate and up-to-date details about the fund, its objectives, and the fund manager’s experience.
Upload Supporting Documents: Upload all the necessary documents such as the constitutional documents, fund manager qualifications, and investment policies.
Pay the Fees: The registration process requires payment of a fee, which varies depending on the fund category.
5. Review and Approval by SEBI
After submitting the application and documents, SEBI will carry out due diligence to verify the authenticity and completeness of the information provided. The regulator may request additional documents or clarifications. Once satisfied, SEBI will approve the registration.
The approval process typically takes a few weeks to months, depending on the complexity of the application and the fund’s structure. Once SEBI grants approval, the AIF will receive a certificate of registration, and the fund can legally begin raising capital and making investments.
Role of an AIF Registration Consultant
Given the complexities of the AIF Registration Process and the stringent regulatory requirements, many fund managers opt to work with an AIF Registration Consultant. Here’s how a consultant can help:
Advisory Services: An AIF Registration Consultantcan advise you on which AIF category best suits your investment strategy, helping you understand the regulatory nuances and financial implications of each option.
Document Preparation: The consultant can assist in preparing the necessary documentation for the registration process, ensuring that all forms are filled out correctly and comply with SEBI’s guidelines.
Online Application Filing: With their experience, AIF registration consultants are well-versed in the AIF Registration Online in India process and can ensure that the online filing is accurate and timely.
Compliance Management: An AIF registration consultant can provide ongoing support to ensure that the fund remains compliant with SEBI regulations even after the registration process is complete. This helps to avoid penalties and operational disruptions.
6. Taxation and Ongoing Compliance
Once your AIF is successfully registered, it is essential to understand the taxation and ongoing compliance requirements. Different categories of AIFs have different tax implications, and failure to comply with regulatory norms can lead to severe penalties. A consultant can help you navigate these post-registration requirements.
Conclusion
The process of Alternative Investment Fund Registration in India is crucial for any fund that aims to attract investment and manage capital in a regulated manner. With the Online AIF Registration in India making the process faster and more accessible, registering an AIF has become easier, though it still requires careful attention to legal and regulatory details.
By understanding the registration process and enlisting the help of an AIF Registration Consultant, fund managers can ensure that their AIF is legally compliant, operationally sound, and poised for success in India’s dynamic investment landscape.
Whether you are launching a venture capital fund, a private equity fund, or a real estate fund, understanding how to get registered as an AIF in India is the first step in making your fund a reality.
For a private limited company in India, a good starting budget of ₹25,000 to ₹60,000 per year is needed for annual compliance costs. Things like bookkeeping, GST and TDS work, difficult audits, government charges, and filings that happen at times can make the total go over ₹1 lakh. These are estimates from professionals. They are not the prices set by the government. They are also not a promise of a package, with all costs included.
Published provider estimates vary substantially in scope. Treat the range as a starting point for obtaining itemised quotations rather than a minimum amount every company must pay.
What does annual compliance cost of a private limited company include?
Annual compliance cost is the money you spend on keeping company records preparing accounts arranging audits that are required and finishing any filings that must be done.
It usually has several parts:
Professional fees: Charges for accounting, audit, tax work and company-secretarial support.
Government fees: Amounts payable for applicable statutory filings.
Recurring operational compliance: GST, TDS and payroll-related work where applicable.
Event-based work: Additional filings triggered by changes to directors, share capital or the registered office.
Support costs: Accounting software, digital signature renewal and document management.
Keep these expenses separate from corporate income tax, GST payable and other tax liabilities. Paying an accountant to file a return is different from paying the tax shown in that return.
Company incorporation is another separate expense. A registration package does not automatically cover the following year’s compliance.
How much should a startup budget for annual compliance?
Start with your activity level and the services you actually need.
What should a straightforward company expect?
For a company with clean books, limited transactions and straightforward ownership, use ₹25,000–₹60,000 as an initial professional-service budget to test against quotations.
Check whether that amount covers:
Preparation of annual accounts.
Statutory audit.
Annual ROC filings.
Company income-tax return preparation.
Routine company-secretarial documentation.
Do not assume these services are all included merely because a provider uses the phrase “annual compliance.”
Why can the annual cost exceed ₹1 lakh?
An increase in costs can be seen when the company needs:
Monthly bookkeeping across several bank accounts.
Regular GST or TDS return preparation.
Payroll and employee-related compliance.
Inventory accounting or transaction reconciliation.
Foreign-investment or cross-border support.
Tax audit, transfer-pricing work or specialised reporting, where applicable.
Correction of past records and overdue filings.
An advertised package may be reasonably priced for its stated scope while covering only part of your company’s needs.
Action: Request separate prices for core annual compliance, recurring accounting and tax work, and additional filings.
Which core obligations should a private limited company plan for?
For an ordinary active private limited company, the baseline includes maintaining accounts, statutory audit, corporate records and applicable annual filings. Low turnover alone does not remove company-law audit requirements.
What accounting and statutory audit work is involved?
Bookkeeping means recording transactions and reconciling them with invoices, bank statements and other evidence.
Statutory audit is the independent examination of financial statements under applicable company law. It is different from maintaining the books.
Budget for:
Recording income and expenses.
Bank and payment reconciliation.
Reviewing receivables and payables.
Preparing financial statements.
Supporting the auditor’s questions and evidence requests.
Finalising the audit report and relevant documentation.
Audit fees depend on the work involved, including transaction complexity and the condition of the records. Turnover is one factor, not the only factor.
Action: Confirm whether your quote includes bookkeeping, accounts preparation and statutory audit as distinct services.
What are AOC-4 and MGT-7 or MGT-7A?
These filings serve different purposes:
AOC-4: Filing financial statements and required accompanying documents, using the applicable form or variant.
MGT-7: The annual return for companies outside the OPC and small-company categories.
MGT-7A: The abridged annual return for OPCs and eligible small companies.
An annual return reports corporate information; it does not replace the financial-statements filing.
For an ordinary company, financial statements are generally filed within 30 days of the AGM, and the annual return within 60 days of the AGM, subject to applicable provisions, exceptions and extensions.
Action: Ask your company secretary to identify the correct forms and calculate your actual deadlines. Avoid using the same calendar date for every company.
Does a company need an income-tax return if it has no profit?
Yes. The Income Tax Department states that companies must file a return irrespective of whether they report profit or loss.
Your professional-service scope should address:
Return preparation and filing.
Reconciliation of income and tax information.
Review of deductions and tax adjustments.
Treatment of losses.
Applicable audit reports or other tax filings.
For FY 2025–26, the department identifies ITR-6 for companies other than those claiming exemption under section 11. Confirm the forms and law applicable to the reporting period rather than carrying old instructions into every future year.
Action: Ask whether your fee includes only uploading the return or also preparing the tax computation and resolving reconciliation differences.
Which additional costs depend on your business?
Not every company needs every compliance service. Applicability should be assessed before pricing the package.
When should you budget for GST, TDS and payroll work?
Ask your adviser which obligations apply based on registration, transactions, payments, employees and relevant thresholds.
Potential services include:
GST return preparation and reconciliation.
TDS calculation, deposit support and return preparation.
Payroll processing.
Applicable professional-tax, EPF or ESI work.
Tax audit or specialised tax reporting.
Statutory audit and tax audit are different requirements. A company-law audit does not mean a separate income-tax audit is automatically required in every case.
Action: Request an applicability checklist. Each service should be marked required, not applicable or subject to review.
Which filings should not automatically be treated as annual?
Some costs arise only when a condition is met or an event occurs:
ADT-1: Relevant auditor-appointment filing; do not assume a fresh filing is required every year.
DPT-3: Consider where deposit or specified non-deposit reporting applies.
MSME Form I: Consider where the applicable supplier-payment reporting conditions are met.
Director KYC: Check the director’s current compliance cycle.
Director changes: Review filings triggered by appointment or resignation.
Share transactions: Review filings arising from allotment or changes in capital.
Registered-office changes: Assess the applicable process and filing requirements.
One important update: ICAI’s January 2026 announcement explains that routine annual director KYC was replaced by a three-year cycle effective 31 March 2026. Do not automatically budget it as an annual filing without checking the director’s circumstances.
Does small-company status reduce compliance costs?
It can reduce parts of the workload, but it does not mean “no audit” or “no annual filing.”
The prescribed small-company financial thresholds increased from 1 December 2025 to:
Paid-up share capital not exceeding ₹10 crore.
Turnover not exceeding ₹100 crore, assessed under the applicable definition.
Both conditions and statutory exclusions must be considered. Holding companies, subsidiary companies, section 8 companies and companies governed by a special Act are excluded from the definition.
Paid-up capital is not the same as authorised capital. The figure relevant to small-company classification should not be confused with the capital basis used for filing fees.
Action: Ask your adviser to confirm your classification for the relevant year and explain which simplifications actually apply.
How are government filing fees different from professional charges?
A government filing fee is payable under prescribed rules. A professional charge pays for preparing, reviewing, certifying and submitting the documents.
For standard ROC document filings, the prescribed fee schedule uses nominal share-capital categories. The exact payable amount depends on the form, company and applicable rules.
When reviewing a quotation, ask:
Are government fees included or billed separately?
Which forms are covered?
Are applicable taxes on professional services additional?
Are certification and document preparation included?
Are corrections or resubmissions chargeable?
Does the quote exclude additional fees for delay?
Avoid treating a quoted “ROC filing cost” as the government fee alone.
Action: Ask for separate subtotals for professional charges, government charges and taxes.
How can you calculate an annual compliance budget?
Use this planning formula:
Annual compliance budget = professional services + government fees + recurring accounting and tax work + event-based work + support costs.
Avoid counting a service twice if it is already part of the annual package.
What would a hypothetical startup budget look like?
Assume a small services company receives these quotations:
Core annual package, including statutory audit and accounts preparation: ₹30,000.
Monthly bookkeeping: ₹2,000 × 12 = ₹24,000.
Applicable GST and TDS support: ₹12,000 a year.
Estimated government fees and digital-signature-related expenses: ₹2,000.
The illustrative budget is ₹68,000, before any applicable tax on professional services and unexpected event-based work.
These are assumed figures showing the calculation, not verified market rates for each service. Actual government charges and digital signature needs must be checked.
If bookkeeping or tax support is already included in the ₹30,000 package, remove the corresponding separate amount.
Action: Turn each quotation into an annual total. Monthly prices can appear small while materially changing the full-year budget.
How much can late filing add to the cost?
Delays can create additional filing fees and separate legal exposure.
The Companies Act’s section 403 framework provides for additional fees of at least ₹100 per day for delayed filings under sections 92 and 137, with amounts prescribed under the rules. Do not apply the same calculation to every MCA form.
For illustration, where the applicable charge is ₹100 per day per form:
One form delayed by 30 days adds ₹3,000.
Two forms each delayed by 30 days add ₹6,000.
That illustration excludes normal fees, professional charges and any separately imposed statutory penalties. Payment of an additional filing fee does not automatically remove other liability.
Action: Track document preparation and sign-off dates before the statutory deadline. Last-minute filing is harder when accounts or signatures are incomplete.
How can you reduce costs without missing obligations?
Reduce repeated work and prevent avoidable corrections.
Useful steps include:
Reconcile bank transactions every month.
Keep invoices and expense evidence organised.
Separate personal and company transactions.
Give your adviser complete information on time.
Review applicability before buying unnecessary services.
Compare providers on the same scope.
Keep filing acknowledgements and final documents.
Review the package when transactions, staffing or ownership change.
Assign clear responsibility:
The founder supplies business information and approvals.
The accountant maintains records and reconciliations.
The auditor performs the independent audit.
The company-secretarial adviser manages applicable corporate filings.
Outsourcing helps with execution, but directors should still monitor completion.
What should you ask before choosing an annual compliance package?
Request written answers to these questions:
Does the price include statutory audit?
Is bookkeeping included, and what transaction limit applies?
Are annual financial statements and the income-tax return included?
Which ROC filings and supporting documents are covered?
Are government fees and applicable taxes on professional services additional?
Is GST or TDS support included?
What counts as an event-based extra?
Are past-year corrections or notice responses excluded?
Who will perform the audit and certify applicable forms?
Will you receive copies of all submissions and acknowledgements?
A clearly defined package is easier to compare and budget than a broad “all-inclusive” promise.
FAQs about annual compliance costs:
Does a zero-turnover company still have compliance expenses?
Yes. Zero turnover does not automatically cancel accounting, audit or filing obligations for an ordinary active company. The work may be simpler, but it still needs to be assessed and completed.
Is statutory audit mandatory for a small private limited company?
For an ordinary active private limited company compliance, low turnover or small-company status alone does not remove the statutory audit requirement. Do not confuse this with income-tax audit thresholds.
Is ₹25,000 enough for the entire year?
It may cover a defined package for a straightforward company. It may exclude bookkeeping, GST, TDS, government fees, taxes, additional filings or backlog work. Check the written scope before relying on the amount.
Are annual compliance fees fixed by the government?
Government filing charges are prescribed. Professional fees vary with scope, complexity and the service provider. There is no single government-fixed all-inclusive compliance package price.
Does an annual package include GST and TDS returns?
Only if the quotation says so. Confirm filing frequency, transaction limits and reconciliation support.
Can a company stop filing because it has stopped trading?
Stopping operations does not automatically end the company’s legal obligations. Ask about continuing compliance, formal dormant status or closure, as appropriate, rather than simply abandoning filings.
Is director KYC still an annual expense?
Do not assume so. The routine framework moved to a three-year cycle from 31 March 2026. Confirm the director’s filing history, changes and applicable requirements.
What is the best way to compare two quotations?
Compare the same deliverables and annual total. Separate professional fees, government charges, taxes and exclusions, and identify any duplicated services.
Conclusion
The annual compliance cost of a private limited company depends on its activity, records, and applicable obligations. Use 25,000 rupees to 60,000 rupees as a starting point for a basic package. Then figure out the services the company needs.
Before finalising your budget:
Confirm your company classification and applicable filings.
Separate professional fees from government charges and taxes.
Check whether audit, bookkeeping, GST and TDS work are included.
Allow for event-based work and support costs.
Keep your records up, to date and track which filings have been completed.
An itemised annual quotation gives you a reliable budget. It helps avoid missed responsibilities, duplicate charges and last-minute surprises.
To start an SME IPO in India, check if you are eligible to hire a merchant banker who is registered with SEBI; get your company and financial records ready; send the draft offer document to the selected SME exchange; get all the needed approvals and file the required papers; start the issue and finish the allotment and listing. Make sure to create a plan for compliance after the listing is done before you begin the process.
This path can work for businesses that are already established and for startups that are at a stage where they can get public equity capital. It is not a way to get funding, for a business that has just started.
What is an SME IPO, and who is it for?
An SME IPO is a public offering that results in a company being listed on a special platform, for small and medium enterprises like NSE Emerge or BSE SME. Of getting money only from private investors a company sells shares to the public using a controlled and official process.
An offer can include two different components:
Fresh issue: The company issues new shares and receives the proceeds, subject to issue expenses.
Offer for sale (OFS): Existing shareholders sell their shares and receive the sale proceeds. That portion does not fund the company’s expansion.
For example, if an IPO includes a ₹24 crore share issue along with a ₹6 crore offer for sale the total money the company gets is ₹24 crore, not ₹30 crore. This is an example, not something that is being planned right now.
An SME IPO is something to think about if you have a plan for growth financial records that are strong and can be checked and a team that is ready for public reporting. If you need money quickly to deal with cash problems, look at other options at the same time, as you consider the IPO path.
Is your business eligible for an SME IPO in India?
Eligibility depends on applicable SEBI regulations and the selected exchange’s criteria. Passing a few financial tests does not establish complete eligibility.
Which NSE Emerge requirements should you check first?
NSE’s published general eligibility criteria include the following screening points:
Incorporation: Company incorporated in India under the Companies Act.
Post-issue capital: Paid-up capital at face value of no more than ₹25 crore.
Track record: At least three years through qualifying company, promoter or predecessor business history.
Operating profit: At least ₹1 crore from operations in any two of the previous three financial years.
Net worth: Positive net worth.
Cash flow: Positive free cash flow to equity in at least two of the three preceding financial years.
These are selected requirements, not the full checklist. Ask the merchant banker to confirm the required financial basis, qualifying history and remaining conditions.
Does the ₹25 crore limit mean you can raise only ₹25 crore?
No. The initial SME listing capital ceiling refers to post-issue paid-up capital at face value, rather than the amount collected at the issue price. BSE’s published eligibility document also identifies a ₹25 crore post-issue paid-up capital ceiling.
For example, issuing 20 lakh shares with a ₹10 face value at ₹100 per share generates ₹20 crore in gross proceeds, while adding ₹2 crore to paid-up share capital. The company must still account for its existing capital and all other eligibility conditions.
Can startups qualify without meeting the usual requirements?
Do not assume that being a startup creates an exemption. Have your adviser identify the exact listing route and assess it under current rules before you treat the IPO as a funding option.
How do you launch an SME IPO step by step?
Step 1: How should you assess IPO readiness?
Begin with a written readiness assessment before committing to a launch date. Ask whether the business qualifies, whether its disclosures are supportable, and whether the proceeds will serve a clear purpose.
Review the following areas:
Financial records: Audited statements and the evidence behind reported figures.
Cash collection: Receivables, payment cycles and cash-flow consistency.
Customer concentration: Dependence on a few customers or contracts.
Legal matters: Disputes, licences and unresolved documentation.
Ownership records: Shareholding history and agreements.
Tax reconciliations: Differences between accounts and tax filings.
Related-party transactions: Dealings with promoters and connected businesses.
A growing business can still need substantial preparation if its records are inconsistent.
Action: Create a gap tracker with four columns: issue, evidence needed, responsible person and completion date. Resolve critical gaps before setting the filing timetable.
Step 2: Who should you appoint to manage the IPO?
Appoint a SEBI-registered merchant banker with relevant SME issue experience. For an SME IPO, the merchant banker’s work includes due diligence, offer-document preparation, underwriting arrangements and ensuring market-making arrangements.
The working team will also typically involve:
Auditors to support financial preparation and verification.
Legal advisers to review contracts, disputes and disclosures.
Company-secretarial advisers to coordinate corporate records and filings.
A registrar to the issue to support application and allotment administration.
Relevant banking and depository participants for issue execution.
An IPO consultant may coordinate readiness and preparation, but that role does not replace the registered merchant banker’s responsibilities.
Action: Compare scope, professional fees, experience, team capacity and post-listing support. Ask who owns each deliverable and what happens if the transaction is postponed.
Step 3: How should you prepare the company and its records?
If your business is a private limited company, plan the conversion to a public limited company with your legal and company-secretarial team. Have them schedule the necessary corporate approvals and filings.
Next, organise a secure data room containing:
Incorporation documents, constitutional documents and statutory records.
Shareholding history, allotment records and shareholder agreements.
Financial statements, tax records and banking information.
Material contracts, licences, property records and intellectual property documents.
Details of litigation, borrowings and related-party dealings.
Your advisers should determine which records need restatement, certification or additional supporting evidence.
Action: Reconcile important figures across accounts, returns and management reports. Maintain one agreed version of each document and log subsequent changes.
Step 4: How do you choose the exchange and prepare the offer document?
Evaluate NSE Emerge and BSE SME by comparing:
Current eligibility criteria for the proposed issuer.
Documentation and application requirements.
Exchange fees and other transaction costs.
The company’s financial history and proposed issue structure.
Avoid assuming their requirements are identical.
The merchant banker leads preparation of the draft offer document: commonly a draft red herring prospectus for a book-built issue or a draft prospectus for a fixed-price issue. The document explains the business, financial information, risks, ownership, issue structure and intended use of funds.
A DRHP is a draft red herring prospectus. It supports the review process; filing it does not mean shares are already available for purchase.
Action: Build evidence behind the business story. If you claim an expanding customer base, support it with records and disclose concentration or retention risks where relevant.
Step 5: How do exchange review and regulatory filings work?
Submit the draft offer document and supporting application to the chosen SME exchange through the prescribed process. The exchange reviews the submission, raises queries where necessary and considers in-principal approval. Required offer-document filings with the Registrar of Companies and SEBI also form part of the process.
Do not describe exchange review as an endorsement of the investment. NSE explicitly distinguishes its review of listing requirements from approval under every applicable law.
Action: Maintain a query register with the question, proposed response, supporting evidence, owner and due date. Keep responses consistent with the financial and legal disclosures.
Step 6: How should you plan pricing, dilution and the use of proceeds?
Work with the merchant banker on the issue structure and pricing approach. Distinguish the funds required by the company from any shareholder sale component.
Prepare a dilution model before agreeing to an issue size. For example, if founders own all 80 lakh existing shares and the company issues 20 lakh new shares, their combined ownership becomes 80% of the one crore post-issue shares. This simplified illustration excludes other share issuances and shareholder sales.
Make each funding objective measurable:
Machinery purchases: Support the budget with supplier estimates and an implementation plan.
Working capital: Explain the operating cycle and how the funding requirement was calculated.
Expansion plans: Identify expected milestones and who will oversee delivery.
Have the merchant banker check whether each proposed objective is permitted under the applicable rules.
NSE’s published restricted SME IPO criteria prohibit objectives that include repaying loans from promoters, the promoter group or related parties, directly or indirectly. They also cap OFS participation at 20% of total issue size and sales by a selling shareholder at 50% of that shareholder’s holding.
Action: Request a written check of every proposed use of funds, shareholder sale and relevant lock-in requirement before finalising the structure.
Step 7: What must be ready before the public issue opens?
Complete the relevant approvals, offer-document filings, issue arrangements and prescribed disclosures before opening subscriptions. Coordinate the launch timetable with the merchant banker, registrar and exchange.
NSE states that SME issues must be fully underwritten, with the merchant banker underwriting at least 15% in its own books. It also requires arrangements for market making for at least three years after listing.
Underwriting is a contractual arrangement addressing subscription shortfalls under agreed terms. Market making involves an authorised participant providing buy and sell quotes to support trading. Neither guarantees a rising share price.
Action: Agree a communications approval process. Keep public statements consistent with the offer document and avoid promises of returns or listing gains.
Step 8: What happens after the issue closes?
After the issue closes, the issue team coordinates:
Reconciliation of applications.
Finalisation of the basis of allotment.
Fund unblocking or refunds, where applicable.
Credit of allotted shares to investor accounts.
Completion of final listing requirements.
NSE’s published onboarding timetable provides for listing on T+3 working days, where T is the issue-closing day. This timetable concerns the period after subscriptions close; it does not mean the whole IPO can be prepared in three days.
Action: Confirm the actual allotment, share-credit and trading dates with the issue team and exchange notices.
Step 9: How should you prepare for life after listing?
Listing changes how you manage disclosure and accountability. Prepare a compliance calendar covering:
Applicable financial reporting and filing deadlines.
Disclosure of material developments.
Shareholder communication and investor matters.
Insider-trading controls.
Monitoring and reporting of issue proceeds, as applicable.
Requirements can depend on the company’s circumstances and current rules. NSE provides a separate Emerge compliance calendar rather than leaving issuers to infer obligations from mainboard guidance.
Action: Assign an owner and backup for each obligation. Run a mock reporting cycle before listing to check that the team can produce accurate information on time.
How long does an SME IPO take, and what does it cost?
There is no dependable single timetable for every company. Preparation, audit work, restructuring, exchange queries and launch conditions can change the schedule.
Ask for a milestone plan that separates:
Readiness assessment and gap resolution.
Financial preparation and offer-document drafting.
Exchange review and responses to queries.
Final filings and public-issue launch.
Allotment, share credits and listing.
A stated launch target should explain its assumptions and dependencies.
Likewise, request an itemised cost proposal rather than relying on one package price.
Also check taxes, reimbursable expenses and withdrawal terms. Compare net usable proceeds with total transaction costs and continuing obligations.
When should you postpone an SME IPO?
Consider postponing if:
Eligibility is unresolved.
Accounting records need major repair.
The funding objective is unclear.
Important disclosures lack supporting evidence.
The management team cannot support public reporting.
Another warning sign is needing the IPO proceeds by a date the business cannot afford to miss. Compare bank finance, private equity or other suitable funding routes while fixing readiness gaps.
Use a practical decision test: can you show how the capital will improve the business, support the disclosures with evidence, and remain accountable after listing?
Frequently Asked Questions:
Is MSME or Udyam registration enough to qualify for an SME IPO?
No. MSME registration does not mean that the company meets the rules of the securities market. Check the company against the listing rules of the exchange that is being used and the rules set by SEBI.
Can a startup that is making a loss launch an SME IPO?
Do not think it can. Operating profit is not the same as profit so look at the exact financial test and the plan with the merchant banker. Check the eligibility checklist above for the points used by NSE Emerge.
Can a private limited company start the IPO directly?
A private company needs to plan to become a company and get the required approvals before starting the public offer. Let the legal team and company secretary plan the steps for the business.
Do the company and the selling shareholders get the IPO money?
No. Money from the issue goes to the company; money from the OFS goes to the selling shareholders. Keep accounts for the related costs.
Does an IPO consultant take the place of a merchant banker?
No. The consultant can help with preparation and coordination. The merchant banker is still responsible, for managing the issue as required by the rules.
Does market making ensure that there is trading or that the listing goes up?
No. It helps with trading by setting prices. It does not guarantee that every shareholder can sell any amount at the price they want or make a profit.
Is mainboard migration automatic after an SME IPO?
No. Treat migration as a separate future assessment under the exchange’s rules then in force. Do not present it as a guaranteed result of the initial listing.
What should a founderdo first?
Prepare recent audited financial statements, the current shareholding structure and a clear funding plan. Request a written eligibility and readiness assessment before committing to an issue date.
Conclusion
Launching an SME IPO in India requires preparation across eligibility, financial records, governance, documentation and issue execution. A well-prepared business should understand how much capital it needs, how the issue will affect ownership and what responsibilities continue after listing.
Before committing to a launch date:
Confirm eligibility for the proposed listing route.
Resolve financial and documentation gaps.
Appoint an experienced SEBI-registered merchant banker.
Define the use of proceeds and assess founder dilution.
Budget for issue expenses and continuing compliance.
Assign responsibility for post-listing reporting.
Start with a written IPO readiness assessment. It gives your board a practical basis for deciding whether to proceed, prepare further or choose another funding route.
Quick answer: How long does AIF registration take?
SEBI does not prescribe a guaranteed overall period for granting Alternative Investment Fund registration. As a practical planning estimate, applicants should generally allow approximately three to six months from preparation to receipt of the registration certificate.
The process can take longer—sometimes six months or more—if the application is incomplete, the fund structure is complex, the sponsor or investment manager does not clearly meet regulatory requirements, or responses to SEBI’s queries are delayed.
SEBI’s published guidance states that an applicant will generally receive an initial reply within 21 working days after submitting an application. This does not mean the registration will be granted within 21 working days. The final timeline depends substantially on how quickly and satisfactorily the applicant responds to regulatory requirements and observations. SEBI’s AIF registration guidance
Understanding SEBI AIF registration
An Alternative Investment Fund, or AIF, is a privately pooled investment vehicle that collects capital from sophisticated investors and invests according to a defined investment policy.
AIFs in India are regulated under the Securities and Exchange Board of India (Alternative Investment Funds) Regulations, 2012. The regulations were most recently amended on July 14, 2026. Current SEBI AIF Regulations
An applicant may seek registration under one of three broad categories:
Category I AIF: Includes venture capital funds, infrastructure funds, social impact funds and other funds considered economically or socially desirable.
Category II AIF: Commonly includes private equity funds, debt funds and other funds that do not undertake leverage except for permitted operational requirements.
Category III AIF: Includes funds that may use complex trading strategies and leverage, subject to applicable conditions.
The category selected affects the fund’s investment strategy, regulatory obligations and the information SEBI may examine during registration.
Estimated SEBI AIF registration timeline
A well-prepared AIF registration can be divided into the following stages:
Registration stage
Indicative time
Fund planning and category selection
1–2 weeks
Formation of the fund and manager entities
2–4 weeks
Drafting legal and regulatory documents
3–6 weeks
Filing the application on the SEBI portal
2–5 working days
Initial review or communication from SEBI
Generally within 21 working days
Responding to SEBI observations
2–8 weeks or longer
In-principle approval and payment of fees
1–3 weeks
Grant of registration certificate
Depends on satisfactory compliance
Typical end-to-end planning estimate
3–6 months
These periods are planning estimates, not statutory guarantees. Several stages may also run simultaneously.
Stage 1: Planning the AIF structure
Estimated time: One to two weeks
The registration journey begins before any application is filed. The sponsor and proposed investment manager must first determine:
The investment objective of the fund
The appropriate AIF category and subcategory
The legal structure of the fund
Target investors
Proposed fund corpus
Sponsor commitment
Management and governance structure
Investment and exit strategy
Proposed tenure of the scheme
Whether the fund will use borrowing or leverage
Key service providers
An AIF may generally be established as a trust, company, limited liability partnership or body corporate. In practice, many Indian AIFs use a trust structure, but the correct structure depends on taxation, governance, investor expectations and the commercial model.
Making major changes after the application has been submitted can lead to additional questions, document revisions and delays. It is therefore important to finalise the commercial and legal structure at the beginning.
Stage 2: Establishing the fund and investment manager
Estimated time: Two to four weeks
Once the structure has been selected, the relevant entities and arrangements must be established. Depending on the chosen structure, this may include:
Formation of the trust, company or LLP
Execution and registration of the trust deed
Incorporation or establishment of the investment manager
Appointment of the trustee, where applicable
Finalisation of ownership and control
Appointment of directors, partners or designated partners
Establishment of an appropriate office and operational infrastructure
Opening of bank accounts
Obtaining PAN and other registrations
Preparation of board or partner resolutions
The exact time will depend on the legal form, availability of documents, name approvals and coordination among the sponsor, manager, trustee and professional advisers.
Stage 3: Preparing the AIF registration documents
Estimated time: Three to six weeks
Documentation is frequently the most demanding stage of the AIF registration process. SEBI examines more than the existence of the fund entity. It also considers whether the proposed sponsor and manager are suitable, adequately experienced and capable of operating a regulated investment fund.
The application package may include:
Form A
Constitutional documents of the applicant
Trust deed, LLP agreement or memorandum and articles of association
Details of the sponsor and investment manager
Shareholding and ownership structure
Financial statements and net-worth evidence
Details of directors, partners and key investment personnel
Professional qualifications and investment-management experience
Infrastructure and staffing details
Disciplinary and litigation declarations
Investment strategy and risk-management framework
Draft Private Placement Memorandum
Compliance policies
Due-diligence declarations and supporting documents
Details of affiliates and group entities
SEBI’s January 2025 registration FAQs provide an application checklist and explain that applications must be filed through the SEBI Intermediary Portal. The stated application fee is ₹1,00,000 plus applicable GST. SEBI FAQs for grant of AIF registration
Registration fees payable after approval vary according to the AIF category. Applicants should verify the latest fees and applicable taxes at the time of filing.
Stage 4: Filing the application with SEBI
Estimated time: Two to five working days after the documents are ready
The applicant must submit the registration application through the SEBI Intermediary Portal. The applicant receives login credentials and uses the “Fresh Registration” option under the AIF section to complete the filing.
Before submission, applicants should verify that:
Form A is complete and consistent
Names and addresses match constitutional records
Supporting documents are properly executed
Financial information is updated
The AIF category matches the proposed investment strategy
Sponsor and manager details are fully disclosed
The Private Placement Memorandum is consistent with the application
The application fee has been paid correctly
Required declarations have been signed by authorised persons
Even a technically minor inconsistency can result in a regulatory query. For example, different descriptions of the investment strategy in Form A and the PPM may require clarification or revision.
Stage 5: SEBI’s initial review
Indicative response: Generally within 21 working days
SEBI’s published guidance states that an applicant will generally receive a reply within 21 working days of submitting the application. Applicants should interpret this carefully.
The 21-working-day period generally relates to an initial regulatory communication. SEBI may:
Seek additional information
Point out missing documents
Ask for clarification of the investment strategy
Request changes to the fund structure
Examine the experience of key personnel
Seek evidence of the manager’s operational capabilities
Ask questions about affiliates or past business activities
Require revisions to the PPM
Seek clarification about sponsor commitment or net worth
Therefore, receiving a reply within 21 working days is not the same as obtaining final registration within that period.
Stage 6: Responding to SEBI observations
Estimated time: Two to eight weeks, but potentially longer
This stage has the greatest influence on the overall registration timeline. The speed of approval often depends on the quality of the application and the applicant’s ability to respond quickly and accurately.
A strong response should:
Address every observation separately
Use clear and direct language
Include revised documents where required
Highlight changes made in each document
Ensure that all revised documents remain consistent
Include supporting evidence rather than unsupported statements
Be approved by the relevant sponsor, manager or governing body before submission
If the first response is incomplete, SEBI may issue another round of observations. Multiple rounds of queries can extend the registration timeline considerably.
Applicants should maintain a central response tracker showing each SEBI observation, the proposed response, the responsible person, required supporting documents and submission status.
Stage 7: Approval, registration fee and certificate
Once SEBI is satisfied that the applicant meets the regulatory requirements, it may approve the application and ask the applicant to pay the applicable registration fee.
After payment and completion of the required formalities, SEBI may grant the certificate of registration.
The fund must ensure that its subsequent activities remain within the scope of the category and conditions under which registration was granted.
Does the GARUDA mechanism make AIF registration faster?
SEBI introduced the Green-Channel: AIF Rollout Upon Document Acknowledgement, or GARUDA, mechanism through a circular dated July 30, 2026. The mechanism is intended to streamline the processing and launch of AIF schemes by relying more heavily on prescribed due diligence and declarations. SEBI GARUDA circular
However, applicants should distinguish between:
Registration of the AIF itself; and
Filing and processing of the scheme’s Private Placement Memorandum.
GARUDA primarily relates to the processing and rollout of schemes. It does not mean that every new AIF registration will automatically be completed within a fixed green-channel period.
For the first scheme, scheme launch remains connected to the grant of AIF registration. Accordingly, the applicant must still satisfy SEBI regarding its eligibility, structure, sponsor, manager, key personnel and other registration requirements.
What can delay SEBI AIF registration?
1. An incomplete application
Missing annexures, unsigned documents, outdated financial statements or incomplete declarations commonly lead to additional observations.
2. Inconsistency between documents
SEBI may seek clarification if Form A, the trust deed, investment management agreement and PPM describe the fund differently.
3. Unclear investment strategy
Broad statements such as “investing in growth opportunities” may not adequately explain the proposed asset classes, sectors, investment stages, geography, risk controls and exit strategy.
4. Insufficient experience of the investment team
SEBI may examine whether the investment manager and key personnel possess suitable professional qualifications and relevant experience.
5. Complex ownership structures
Multiple layers of holding companies, foreign shareholders or unclear beneficial ownership may increase the level of regulatory scrutiny.
6. Sponsor or manager eligibility issues
Questions concerning net worth, fit-and-proper status, prior regulatory matters, litigation or disciplinary history can lengthen the review.
7. Weak operational readiness
The manager must demonstrate that it has adequate infrastructure, personnel, compliance arrangements and systems to manage the AIF.
8. Delayed responses to SEBI
If the applicant takes several weeks to respond to each observation, the registration process will naturally take longer.
9. Frequent commercial changes
Changing the fund category, sponsor, manager, investment strategy or legal structure during regulatory review may require substantial revisions.
10. Deficiencies in the PPM
Inaccurate, incomplete or inconsistent disclosures in the Private Placement Memorandum can delay the process and create regulatory risk.
How can applicants complete AIF registration faster?
No consultant or applicant can guarantee a specific approval date because registration remains subject to SEBI’s review. However, the following steps can reduce avoidable delays:
Complete a regulatory readiness assessment
Review the sponsor, manager, key personnel, ownership structure and investment proposal against the applicable AIF requirements before filing.
Finalise the structure early
Select the fund category, legal structure, investment strategy, sponsor and manager before preparing the application.
Use a comprehensive document checklist
Create a checklist based on the latest SEBI regulations, master circulars, FAQs and portal requirements.
Keep all documents consistent
Use identical descriptions of the fund, parties, strategy, tenure, corpus and governance arrangements throughout the application.
Prepare for regulatory questions
Anticipate questions about the investment team, sponsor commitment, track record, beneficial ownership, risk management and conflicts of interest.
Assign a dedicated response team
A single team should coordinate information from legal, tax, finance, compliance and investment professionals.
Respond promptly and completely
A fast but incomplete response may create another round of questions. The objective should be to provide one comprehensive and well-supported response.
Can an AIF start raising money before receiving registration?
A proposed AIF should not represent itself as a SEBI-registered AIF before receiving its registration certificate.
Scheme launch and circulation of the PPM must also follow the applicable regulatory framework. The exact requirements may differ for regular schemes, accredited-investor-only schemes, angel funds and large value funds for accredited investors.
Applicants should examine the latest regulations and SEBI circulars before approaching investors or circulating offering documents.
Practical example of an AIF registration timeline
Consider a Category II private equity fund with an Indian sponsor and investment manager:
Weeks 1–2: The promoters finalise the fund structure, target corpus, investment strategy and key team.
Weeks 3–5: The fund entity and investment manager arrangements are established.
Weeks 4–8: Form A, constitutional documents, compliance policies and the PPM are prepared.
Week 9: The application is submitted through the SEBI portal.
Weeks 10–13: SEBI conducts its initial review and communicates observations.
Weeks 14–16: The applicant prepares and submits a detailed response.
Weeks 17–20: Additional clarifications, if any, are addressed.
Weeks 21–24: Approval, payment of registration fees and issuance of the certificate may follow, subject to SEBI’s satisfaction.
In this example, the overall process takes approximately five to six months. A simpler, exceptionally well-prepared application may move faster, while a complex application involving multiple observations may take longer.
Is there a guaranteed SEBI AIF registration timeline?
No. SEBI does not guarantee that every AIF registration application will be approved within a fixed number of days.
The regulator’s published guidance refers to an initial reply generally being issued within 21 working days. The final registration period depends on the completeness of the application, the complexity of the structure and the applicant’s speed in satisfying regulatory requirements.
Applicants should be cautious of anyone promising guaranteed approval within 21 days or any other fixed period.
Conclusion
A realistic timeline for completing SEBI AIF registration is generally three to six months, including preparation, filing, regulatory review, responses and approval formalities. Complex applications may take longer.
The most effective way to reduce delays is to submit a complete, consistent and well-supported application from the outset. Sponsors and fund managers should finalise their structure early, prepare clear disclosures and maintain a dedicated team for responding to SEBI observations.
BIATConsultant assists fund sponsors and investment managers with AIF structuring, document preparation, SEBI registration support, regulatory coordination and post-registration compliance. Professional preparation can help applicants identify potential issues before filing and move through the review process more efficiently.
Disclaimer: This article is intended for general informational purposes and does not constitute legal, tax, investment or regulatory advice. SEBI regulations, circulars, fees and portal requirements may change. Applicants should review the latest official requirements and obtain professional advice based on their proposed fund structure.
Frequently Asked Questions
How many days does SEBI take to register an AIF?
SEBI does not specify a guaranteed overall approval period. Its published guidance states that an applicant will generally receive an initial reply within 21 working days. Final registration may practically take around three to six months, depending on the application and responses to observations.
Can SEBI AIF registration be completed in one month?
It is generally not advisable to plan on completing the entire process in one month. Preparation of the entities, documents and PPM itself may take several weeks, followed by SEBI’s review and possible queries.
Why does AIF registration take several months?
The process involves scrutiny of the applicant, sponsor, investment manager, key personnel, fund structure, investment strategy, financial resources, regulatory history and offering documents.
What is the fastest way to obtain AIF registration?
The best way to avoid delay is to finalise the structure early, prepare a complete application, maintain consistency across all documents and respond comprehensively to SEBI’s observations.
Does the 21-working-day period mean automatic approval?
No. The period mentioned in SEBI’s guidance relates to a general response after receiving the application. It is not an automatic or guaranteed approval timeline.
Does the AIF category affect the registration timeline?
Yes. The category and strategy may affect the nature of SEBI’s review. Category III structures, complex strategies, leverage arrangements and unusual ownership structures may require additional explanation.
How long does Category II AIF registration take?
A Category II AIF should generally budget approximately three to six months for the complete process. The actual duration depends on documentation quality, structure and regulatory observations.
How long does Category III AIF registration take?
Category III registration may take three to six months or longer where the proposed strategy, leverage, risk controls or operational framework requires detailed review.
Can an AIF launch its first scheme immediately after filing?
Not necessarily. For a first scheme, launch remains linked to receipt of AIF registration and satisfaction of the applicable PPM filing requirements. Applicants must follow the latest SEBI regulations and circulars.
Is professional assistance mandatory for AIF registration?
Engaging a consultant is not, by itself, a substitute for meeting SEBI’s requirements. However, legal, tax, compliance and regulatory professionals can help structure the fund, prepare consistent documents and manage regulatory observations effectively.
India’s alternative investment fund market is grown significantly over the last few decades , making Alternative Investment Funds (AIFs) is one of the most preferred investment for the private firms, ventures, hedge funds and the institutional investors. To operate this legally in India, this AIF must contain registration from the Securities and Exchange Board of India (SEBI) SEBI (Alternative Investment Funds) Regulations, under 2012.
If you want plan for launching an investment fund in India, the understanding of AIF registration process is most important element for understanding AIF. This guide explains each step by step in detail.
What is an Alternative Investment Fund (AIF)?
An Alternative Investment Fund (AIF) is a specialized investment vehicle that pools capital from multiple investors to invest in non-traditional asset classes, such as private equity, real estate, hedge funds, venture capital, and commodities. These funds are typically managed by professional fund managers and are structured as limited partnerships or limited liability companies.
AIFs can be structured as:
Trusts
Limited Liability Partnerships (LLPs)
Companies
Body Corporates
These are the funds which are regulated by SEBI and are generally used for the investments in startups, private companies, infrastructure projects, real estate, private equity, venture capital, debt instruments, and hedge fund strategies.
Categories of AIFs in India
Before starting any registration process the fund managers has to choose the appropriate AIF category according to need.
Category I AIF
These are AIFs that invest on start up and early stage venture , small and medium enterprises , infrastructure . AIFs I also Include investment in social and economically desire group. Category I considered to have moderate risk and low regulatory restriction compare to other AIFs categories.
Examples:
Venture Capital Funds
Angel Funds
Infrastructure Funds
SME Funds
Social Venture Funds
Category II AIF
These are AIFs that do not fall under both categories AIFs I and AIFs II . This category known for moderate risk and uncertainites for investment . These category include private Equity funds , debt funds , and funds invest in real state among India.
Examples:
Private Equity Funds
Debt Funds
Fund of Funds
Category III AIF
Category III Use complex stragies for These are AIFs that use complex trading strategies and leverage to generate high returns for investors, such as hedge funds, among others.
Step-by-Step AIF Registration Process in India
Step 1: Determine the Fund Structure
The first step is decide the legal structure of the fund for investment process.
And determining whether the funds fall in which category either is category I , II, Or III . Choosing the correct category is critical because regulatory requirements differ for each category.
You must:
Create the trust, LLP, or company
Draft constitutional documents
Obtain PAN and other registrations
Establish the investment management entity
SEBI reviews the legal structure carefully before granting approval.
Step 2: Select the Appropriate AIF Category
The second step is to determine whether the the fund falls under which is it Category I, Category II, or Category III.
The category affects investment restrictions, compliance requirements, and operational guidelines. Selecting the correct category at the beginning helps avoid regulatory complications later.
Step 3: Appoint the Sponsor and Investment Manager
Every AIF requires a sponsor and an investment manager for the analyising of funds.
The sponsor establishes the fund and contributes the required continuing interest, while the investment manager is responsible for managing investments and making portfolio decisions.
SEBI reviews the qualifications, experience, and regulatory track record of these entities during the registration process.
Step 4: Draft the Private Placement Memorandum (PPM)
The Private Placement Memorandum (PPM) is one of the most important documents for the AIF registration in India.
It contains key information such as:
Investment strategy for the investors
Risk factors and uncertainty
Governance structure
Fee structure
Investor rights
Exit mechanisms
A well-drafted PPM improves transparency and increases the likelihood of regulatory approval.
Step 5: Prepare Documentation
The Applicants must have all the documents which are needed for the investment before filing the application.
Common documents include:
Trust Deed or LLP Agreement
Certificate of Incorporation
PAN card details
Bank account details
Sponsor information
Investment manager details
Financial statements
Compliance declarations
Private Placement Memorandum
Accurate documentation helps prevent delays during SEBI review.
Step 6: Submit the Application to SEBI
This is one of the most important key element of the AIFs registration because application is officially submitted and the review as well as approval will be done SEBI. The application for AIF registration is submitted through SEBI’s online intermediary portal. The document should well prepared for the delay of registration.
The applicant must complete Form A, upload supporting documents, and pay the applicable fees.
Once submitted, SEBI begins its review process.
Step 7: Respond to SEBI Queries
Before the approval the SEBI may seek clarifications regarding the fund structure, investment strategy, governance framework, or the documentation.
Timely and accurate responses are essential for smooth approval.
Step 7: Respond to SEBI Queries
These is the final step SEBI will ask for the document clarification regarding several step for the investment. Respond to SEBI Queries objective is to ensure that the proposed Alternative Investment Fund complies with all regulatory requirements and adequately protects investor interests. In these several Queries may ask :
Asking for the missing documents , clarification regarding the fund structure, Investors protection, Governance and compliance framework concern.
How Long Does AIF Registration Take?
The time taken for AIF registration process depends on the situation of complexity of the application and the quality of documentation that has been submitted.
In most cases:
Fund Structuring: 2–4 Weeks
Documentation Preparation: 3–6 Weeks
SEBI Review: 4–12 Weeks
Final Approval: 2–4 Weeks
Most AIF registrations are completed within 2 to 8 months.
Conclusion
AIFs is very important crucial step for every fund manager , venture capital funds ,private equity funds and investment professionals looking to establish a regulated investment platform in India. By selecting the best AIFs category , fund structure , preparing all the documents and analysing the document which is needed for the AIFs registration process. By selecting the appropriate fund structure, preparing robust documentation, drafting a comprehensive PPM, and complying with SEBI regulations, applicants can successfully launch and operate an Alternative Investment Fund.
Frequently Asked Questions (FAQs)
What is a SEBI AIF Registration?
An Alternative Investment Fund that has registered with the Securities and Exchange Board of India (SEBI) is known as a SEBI AIF Registration. AIFs are investment vehicles that invest in assets such as private equity, venture capital, real estate, and debt securities.
What is AIF Registration?
All the registration process are done and approval from the SEBI is most important . In these approval from SEBI to establish and operate an Alternative Investment Fund in India.
Is SEBI Registration Mandatory for AIFs?
Yes, it is very important in every Alternative investment funds, and must be register with SEBI.
Who Can Register an AIF in India?
A Trust, LLP, Company, or Body Corporate can apply for AIF registration subject to SEBI regulations.
How Long Does AIF Registration Take?
It takes almost 2-8 months according to document submission to SEBI. If any document is not missing it will approve soon.
What is a Private Placement Memorandum (PPM)?
A PPM is a legal document that outlines the fund’s investment strategy, risks, fee structure, governance, and investor rights.
What Are the Benefits of AIF Registration?
AIF registration provides regulatory recognition, investor confidence, fundraising opportunities, and a structured framework for managing investments.
There is more than Alternative Investment Funds (AIFs) which have become the most one of the preferred investment vehicles for the high-net-worth individuals (HNIs), family offices, institutional investors, and startups are looking for the well structured capital solutions in India.There are many investors and businesses who are still in doubt to understand the difference between Category I, Category II, and Category III AIFs.
If someone is planning to invest in AIFs, and want to launch an investment fund, or explore emerging AI-driven investment technologies, understanding these categories are very important for making informed financial decisions.
In this guide, we will try to explain everything about Category I, II, and III AIFs in a very simple language — including the structure, benefits, taxation, regulations, examples, and how technology and AI are transforming the AIF ecosystem.
What is an AIF?
There is An Alternative Investment Fund (AIF) is a privately pooled investment vehicle regulated by the Securities and Exchange Board of India (SEBI). The funds used to collect money from the sophisticated investors and invest in assets beyond traditional stocks and bonds.
AIFs generally invest in:
Startups company
Private equity
Venture capital
Real estate
Infrastructure development
Debt instruments
Hedge funds
AIFs is regulated by the SEBI (Alternative Investment Funds) under the Regulations, 2012.
Types of AIFs in India
The SEBI is classified in AIFs in three categories
Category I AIF
Category II AIF
Category III AIF
Every category has different investment strategies like risk levels, tax implications, and the regulatory benefits.
Category I AIF Explained
The Category I AIFs invest in those sectors which are considered socially and economically beneficial for India.
These kinds of funds receive more incentives and support from the government because this sector contribute to economic growth as well as innovation.
Key Features of Category I AIFs
Invest in the startups in the Newly businesses
The promotion of the Entrepreuneurship
Have less investment risk
Government incentives may apply
Long-term investment opportunity
Types of Category I AIFs
Venture Capital Funds (VCFs)
Investing in the startups and the high-growth companies.
SME Funds
These are focused in Medium enterprise
Infrastructure Funds
In these Investment in the infrastructure project for example Roads , energy and logistics.
Social Venture Funds
In these the company which creates social welfare gets Funds
Who Should Invest in Category I AIFs?
Category I AIFs are suitable for:
For the Long-term investors
Startup-focused investors which can create innovation
Investors seeking government-supported sectors
High-risk, high-growth investors
Category II AIF Explained
Category II AIFs are the most common type of AIF in India. These kinds of funds don’t receive incentive through the the government and do not have aggresive trading strategies compare to Category III.
They primarily invest in the private companies, debt instruments, and the unlisted businesses.
Features of Category II AIFs
There is no leverage expectation for operations.
Mature business gets investment
From medium to long term investment
It is Stable compared to Category III
Widely used by private equity firms
Different types of Category II AIFs
Private Equity Funds
Private companies which is established gets Investment
Debt Funds
Invest in debt for securities of companies.
Fund of Funds
Invest in other AIFs.
Real Estate Funds
Invest in commercial and residential projects.
Who Should Invest in Category II AIFs?
Ideal for:
High Net worth individual
Institutional investors
Family offices
Investors seeking balanced risk and return
Category III AIF Explained
In Category III AIFs they use high complex trading strategies and may employ leverage to generate short-term investment returns.
These funds are similar to the hedge funds and actively trade across markets.
Features of Category III AIFs
Use for leverage and derivatives
High risk for investment
Short-term opportunities for trading
Higher flow of liquidity
Suitable for sophisticated investors
Examples of Category III AIFs
Hedge Funds : wide range of assets , debt , real estates
Quantitative Trading Funds
AI-powered Algorithmic Trading Funds
Long-short equity funds
Who Should Invest in Category III AIFs?
Suitable for the :
Aggressive investors
HNIs
Institutional traders
Investors comfortable with market fluctuations of price
Difference Between Category I, II, and III AIFs
Feature
Category I AIF
Category II AIF
Category III AIF
Investment Focus on
Startups, SMEs, infrastructure
Private equity, debt
Trading & hedge strategies
Government Incentives presence
Yes
No
No
Risk Level
Moderate to High
Moderate
Very High
Leverage Allowed
Limited
Limited
Yes
Investment time period
Long-term
Medium to Long-term
Short-term to Medium-term
Liquidity
Low
Moderate
High
Type of investor
Growth investors
Balanced investors
Aggressive investors
Examples:
Venture capital funds
PE funds
Hedge funds
Taxation of AIFs in India
Taxation differs depending on the category of the AIF.
Category I and II AIF Taxation
These are categories who generally enjoy pass-through taxation status, meaning income is taxed in the hands of investors rather than the fund itself.
Category III AIF Taxation
Category III do not receive any pass through status and are taxed at their fund level.
Tax regulations can change frequently, so professional tax consultation is advisable.
According to SEBI regulations:
Minimum investment should be 1 crore rupee for the investor.
And For the directors/employees/managers of the fund should be 25 lakhs.
These are mainly designed for sophisticated investors.
Benefits of Investing in AIFs
Portfolio Diversification
In AIFs we explore beyond traditional equity and also for the debt markets.
Access to High-Growth Opportunities
Investors can directly participate in startups, private companies, and emerging sectors for the high return.
Fund Management by professional
It is Managed by experienced professionals and investment experts to reduced the risk and uncertainties of your funds.
Potential for Higher Returns
Alternative assets can be generated higher returns compare to conventional investments.
Risks Associated with AIFs
AIFs offer strong growth potential, they also come with high risks:
Limited liquidity
Market uncertainty
Government Regulation
High minimum investment
Complex structures
Investors should evaluate their risk appetite more carefully before investment in company.
How AI is Transforming the AIF Industry
Artificial Intelligence is changing very fast the way Alternative Investment Funds operate.
Modern AIF firms are using AI for:
Portfolio optimization
For identifying the risk
Detection of funds
Predictive analytics
Algorithmic trading
Investor reporting automation
AI agents can process a huge financial datasets in real-time, helping the fund managers make faster decision and more reliable investment decisions.
Businesses looking to integrate intelligent automation into investment operations can leverage custom AI solutions from Winklix AI Agent Development Services. Their AI-driven systems help enterprises build autonomous AI agents for finance, investment management, and operational automation.
Why Understanding AIF Categories Matters
Choosing the right AIF category depends on several factors:
Investment goals
Risk tolerance
Liquidity requirements
Tax planning
Investment horizon
A startup-focused investor may prefer Category I, while a stable private equity investor may choose Category II. Aggressive investors looking for high-frequency strategies may opt for Category III.
Understanding these differences helps investors make smarter financial decisions.
Future of AIFs in India
India’s alternative investment market is expected to grow further in future due to significantly aspects:
Rising the ecosystem
Due to Increased HNI participation
The growth of the private capital
AI-driven investment management
Increase of fintech and wealthtech platforms
As the financial technology is evolving, AI -powered fund management and automation is likely to become more in future of AIFs .
Final Thoughts
Alternative Investment Funds are reshaping India’s investment landscape by offering sophisticated investors access to private markets, startups, and advanced trading opportunities.
The understanding of difference between Category I, II, and III AIFs is very important key aspects before making any investment decisions. Each and every category serves different investor needs, risk profiles, and financial goals.
As AI automate and continue to transform financial services, the future of AIF management will become more increasingly data-driven and intelligent. Businesses and investment firms are adopting AI-powered solutions early will gain a strong competitive advantage in the evolving alternative investment ecosystem.
Frequently Asked Questions (FAQs)
1. What is the main difference between Category I, II, and III AIFs?
Category I focuses on startups and socially beneficial sectors, Category II focuses on private investment and debt investments, while Category III invest in complex trading and hedge fund strategies.
2. Which AIF category is the safest?
The category II AIFs are find safe and considered relatively stable for the investment.Category III is avoided because of leverage trading strategies .
3. Can Category III AIFs use leverage?
Yes, Category III AIFs are allowed to use leverage and derivatives for investment strategies.
4. What is the minimum investment required for AIFs in India?
The minimum investment amount is generally ₹1 Crore per investor.
5. Are AIFs regulated in India?
Yes, AIFs are regulated by the (SEBI)Securities and Exchange Board of India
6. Which AIF category invests in startups?
The Category I AIFs primary focus on investment in startups, SMEs, and innovative driven businesses.
7. How is AI being used in AIF management?
AI helps in many aspects like prediction analytics, algorithmic trading, investor analytics, portfolio management, and automation of investment operations.
8. Are AIFs better than mutual funds?
AIFs offer access to alternative assets and potentially higher returns, but they also comes with the higher barrier risk and it take larger investments compared to mutual funds.
Non-Banking Financial Companies (NBFCs) play a crucial role in India’s financial ecosystem by providing credit to underserved segments, SMEs, and individuals. However, managing credit risk and predicting loan defaults remain significant challenges. With the advancement of technology, Artificial Intelligence (AI) has emerged as a powerful tool helping NBFCs enhance risk assessment, reduce defaults, and improve overall portfolio performance.
Understanding Loan Default Risks in NBFCs
Loan defaults can severely impact an NBFC’s profitability and regulatory standing. Traditional credit assessment models often rely on limited historical data and manual evaluation, which may not accurately capture borrower behavior. As regulatory scrutiny increases—especially for companies holding an NBFC license from RBI in India—adopting smarter risk management practices has become essential.
How AI Transforms Loan Default Prediction
AI-driven systems analyze vast amounts of structured and unstructured data to identify patterns that humans might miss. By leveraging machine learning algorithms, NBFCs can predict potential defaults with higher accuracy and speed.
AI helps NBFCs by:
Analyzing customer transaction behavior in real time
Evaluating alternative data such as digital footprints and spending habits
Detecting early warning signals of repayment stress
Continuously improving credit models through learning algorithms
These capabilities significantly enhance credit decision-making and portfolio quality.
Benefits of AI for NBFCs
The integration of AI in credit risk management delivers multiple advantages:
Improved accuracy in credit scoring
Faster loan approval processes
Reduced operational costs
Better compliance with RBI regulations
Lower non-performing assets (NPAs)
These benefits strengthen the credibility of NBFCs operating under an NBFC license online framework.
AI and Regulatory Compliance for NBFCs
As NBFCs adopt AI-driven systems, compliance with regulatory guidelines remains critical. Whether it is NBFC registration online or ongoing regulatory reporting, AI helps streamline compliance by automating documentation, monitoring risk exposure, and ensuring transparency in decision-making.
For new entrants, completing NBFC Registration online in India becomes smoother when technology-driven processes are aligned with regulatory requirements.
Importance of Expert Guidance in NBFC Registration
Setting up an NBFC involves complex legal and compliance procedures. Engaging a professional NBFC registration consultant or an experienced NBFC Registration Consultant in India ensures that licensing, capital requirements, and RBI approvals are handled efficiently.
Consultants also guide NBFCs in adopting technology frameworks, including AI-based risk assessment tools, after securing an NBFC license from RBI in India.
Why AI Adoption Is the Future for NBFCs
AI is no longer optional for NBFCs—it is a strategic necessity. With increasing competition and tighter regulations, NBFCs that leverage AI gain a strong advantage in managing credit risk, improving customer trust, and achieving sustainable growth.
Whether you are planning NBFC registration online or scaling an existing NBFC, integrating AI-driven credit risk solutions can significantly enhance business performance.
Conclusion
AI is transforming the way NBFCs predict loan defaults by enabling smarter, faster, and more accurate risk assessment. Combined with proper compliance and expert guidance from an NBFC registration consultant, NBFCs can build resilient financial institutions ready for the future.
For businesses seeking NBFC Registration online in India and aiming to operate under a valid NBFC license from RBI in India, embracing AI-powered technologies is a vital step toward long-term success.
The foreign exchange ecosystem in India is evolving rapidly, and Full Fledged Money Changers (FFMCs) are under increasing regulatory and operational pressure. With strict RBI norms governing the full fledged Money Changer license, businesses must ensure transparency, compliance, and robust risk management. This is where Artificial Intelligence (AI) and Data Analytics are transforming the FFMC industry.
The Growing Compliance Challenge for FFMCs
Entities holding an FFMC License in India must comply with multiple regulations, including KYC, AML, FEMA, and RBI reporting requirements. Manual compliance processes often lead to delays, human errors, and higher operational costs. As full fledged Money Changers scale their operations, the complexity of monitoring transactions and identifying risks increases significantly.
How AI Enhances Compliance Monitoring
AI-powered systems can automate and strengthen compliance frameworks for FFMCs. Advanced algorithms analyze large volumes of transaction data in real time to detect anomalies, suspicious patterns, and non-compliant activities.
Generate accurate compliance reports for regulators
This significantly reduces manual intervention and improves regulatory confidence.
Data Analytics for Smarter Risk Management
Data analytics enables FFMCs to move from reactive to proactive risk management. By leveraging historical data, analytics platforms can predict potential compliance risks, customer behavior trends, and exposure to foreign exchange volatility.
This data-driven approach supports sustainable growth while maintaining compliance.
AI in Fraud Detection and AML Controls
AI models are highly effective in identifying complex fraud patterns that traditional systems may miss. For FFMCs, this means stronger AML controls and faster detection of suspicious activities, ensuring adherence to RBI guidelines.
By integrating AI with digital platforms offering FFMCs license online application and management services, businesses can also streamline internal audits and compliance reviews.
Future of FFMC Operations in India
As regulatory scrutiny intensifies, AI and data analytics will become essential tools rather than optional upgrades. FFMCs that invest in intelligent compliance systems will not only safeguard their full fledged Money Changer license but also gain a competitive edge through efficiency, accuracy, and trust.
Conclusion
AI and data analytics are redefining how full fledged Money Changers operate in India. From smarter compliance monitoring to advanced risk management, these technologies empower FFMCs to stay compliant, reduce operational risks, and scale confidently. For businesses seeking long-term success under an FFMC License in India, embracing digital intelligence is the way forward.
In recent years, the Indian financial sector has witnessed a paradigm shift where profitability is no longer the sole measure of success. Social impact investing—investments that generate measurable social and environmental benefits alongside financial returns—is gaining strong momentum. At the forefront of this transformation are Non-Banking Financial Companies (NBFCs), which play a vital role in financial inclusion and sustainable development.
With a supportive regulatory framework and growing investor awareness, NBFCs are uniquely positioned to align profit with purpose. This blog explores how NBFCs can leverage social impact investing while navigating NBFC Registration in India and RBI compliance effectively.
Understanding Social Impact Investing in the NBFC Ecosyste
Social impact investing focuses on funding initiatives that address critical challenges such as:
Financial inclusion
Affordable housing
MSME development
Renewable energy
Healthcare and education financing
NBFCs, due to their flexibility and outreach, are natural vehicles for impact-driven lending and investment. Holding a valid NBFC License in India enables companies to design customized financial products targeted at underserved communities.
Why NBFCs Are Ideal for Social Impact Investing
1. Strong Reach in Underserved Markets
NBFCs often operate in areas where traditional banks have limited presence. Through proper NBFC registration online, companies can scale operations to support rural borrowers, startups, women entrepreneurs, and small businesses.
2. Regulatory Support from RBI
The NBFC license from RBI in India provides a structured framework that balances innovation with financial stability. RBI guidelines encourage responsible lending, transparency, and long-term sustainability—key pillars of social impact investing.
3. Flexible Business Models
Unlike banks, NBFCs can tailor credit products to suit impact-focused sectors. Whether financing electric vehicles or affordable housing, NBFCs can innovate once they complete Online NBFC Registration in India.
Role of NBFC Registration in Building Investor Confidence
Investors in social impact funds seek regulatory clarity and risk mitigation. A properly structured NBFC Registration in India demonstrates:
Legal credibility
Governance transparency
Compliance with RBI norms
Many startups opt for NBFC license online processes to streamline approvals and reduce time-to-market while maintaining compliance.
Digital Transformation and Impact Measurement
Technology is playing a crucial role in aligning profit with purpose. Through NBFC registration online and digital lending platforms, companies can:
Track borrower outcomes
Measure social impact metrics
Improve loan monitoring and recovery
This data-driven approach increases accountability and attracts ESG-focused investors.
Importance of Professional NBFC Registration Consultants
The regulatory process for obtaining an NBFC License in India is complex and documentation-intensive. Engaging an experienced NBFC registration consultant or NBFC Registration Consultant in India helps ensure:
Accurate RBI filings
Faster approvals
Proper capital structuring
Long-term compliance readiness
Professional guidance allows NBFC founders to focus on impact-driven strategies rather than regulatory hurdles.
Popular Social Impact Sectors for NBFCs
NBFCs operating under a valid NBFC license from RBI in India are actively investing in:
Microfinance and financial inclusion
Green and sustainable finance
Affordable healthcare loans
Skill development financing
Agri-finance and rural credit
These sectors offer stable returns while delivering measurable social benefits.
Challenges and Risk Management
While impact investing offers long-term value, NBFCs must address:
Credit risk in underserved segments
Regulatory compliance obligations
Impact measurement frameworks
Proper structuring during NBFC Registration online in India and continuous compliance monitoring help mitigate these challenges effectively.
Conclusion
NBFCs are redefining the future of finance by proving that profitability and social responsibility can coexist. Through structured NBFC Registration in India, strong governance, and impact-focused lending, NBFCs can attract socially conscious investors while delivering sustainable financial returns.
For entrepreneurs and institutions aiming to create meaningful change, obtaining an NBFC License in India is not just a regulatory milestone—it is a gateway to aligning business success with societal progress.
Transparency and trust are critical pillars of the lending ecosystem. As India’s financial sector rapidly embraces digital transformation, Non-Banking Financial Companies (NBFCs) are increasingly exploring advanced technologies to improve efficiency, compliance, and customer confidence. One such transformative technology is blockchain.
This blog explains how NBFCs can leverage blockchain to enable transparent lending while remaining compliant with regulatory requirements such as NBFC Registration in India and RBI licensing norms.
Understanding Blockchain in the NBFC Lending Ecosystem
Blockchain is a decentralized, tamper-proof digital ledger that records transactions in a transparent and immutable manner. For NBFCs, this means enhanced data integrity, real-time verification, and reduced dependency on intermediaries.
NBFCs operating with a valid NBFC License in India can use blockchain to improve loan processing, documentation, repayment tracking, and regulatory reporting.
Why Transparency Is a Challenge for NBFC Lending
Despite regulatory oversight, NBFCs often face challenges such as:
Limited visibility into borrower credit history
Manual documentation and reconciliation errors
Delays in loan disbursement and repayments
Compliance risks under RBI and FEMA regulations
Blockchain addresses these pain points by creating a single source of truth accessible to authorized stakeholders.
Key Use Cases of Blockchain for NBFCs
1. Secure Digital Loan Records
Blockchain enables NBFCs to store loan agreements, borrower data, and repayment schedules on a secure ledger. Once recorded, data cannot be altered, ensuring complete transparency for auditors and regulators.
Smart contracts are self-executing agreements coded on blockchain. These contracts automatically trigger loan disbursements, EMI collections, or penalties once predefined conditions are met.
For NBFCs with an NBFC license from RBI in India, smart contracts help:
Reduce operational costs
Eliminate manual intervention
Ensure compliance with lending terms
3. Improved Credit Assessment and Fraud Prevention
Blockchain allows NBFCs to access verified borrower data across institutions, reducing identity fraud and credit manipulation. This enhances due diligence and supports responsible lending practices.
All repayments recorded on blockchain are time-stamped and immutable. Borrowers and lenders can view real-time repayment status, minimizing disputes and improving trust.
Such transparency strengthens the credibility of NBFCs operating under a valid NBFC License in India.
5. Regulatory Compliance and Audit Readiness
Blockchain simplifies compliance by maintaining an auditable trail of every transaction. Regulators and auditors can access verified records instantly, reducing inspection timelines.
Technology adoption does not replace regulatory compliance. NBFCs must still obtain proper authorization through NBFC registration online and comply with RBI capital, governance, and reporting norms.
Holding a valid NBFC license online application approval ensures:
Legal recognition
Higher trust among investors and borrowers
Smooth integration of emerging technologies
Professional support from an NBFC registration consultant helps NBFCs navigate licensing and technology alignment seamlessly.
Challenges and Considerations
While blockchain offers immense potential, NBFCs must consider:
Data privacy and cybersecurity risks
Integration with legacy systems
Regulatory clarity on decentralized finance models
A phased implementation strategy, guided by compliance experts, helps mitigate these challenges.
Future of Blockchain in NBFC Lending
As India’s fintech ecosystem matures, blockchain is expected to play a central role in credit scoring, co-lending models, and cross-border financing. NBFCs that invest early in transparent lending frameworks will gain a strong competitive advantage.
Securing an NBFC license from RBI in India and adopting blockchain-based systems positions NBFCs as trustworthy, future-ready financial institutions.
Conclusion
Blockchain has the potential to revolutionize NBFC lending by enhancing transparency, reducing fraud, and improving regulatory compliance. However, its success depends on a strong legal foundation and proper licensing.
By completing NBFC Registration in India, obtaining the required RBI approvals, and working with a qualified NBFC Registration Consultant in India, NBFCs can confidently leverage blockchain to build a transparent, efficient, and scalable lending ecosystem.
In India’s tightly regulated foreign exchange ecosystem, trust and compliance are the foundation of every successful transaction. For businesses dealing in foreign currency exchange, credibility is not optional—it is essential. This is where obtaining a Full Fledged Money Changer license plays a decisive role. An FFMC License in India, issued by the Reserve Bank of India (RBI), does much more than grant legal permission to operate; it significantly enhances a company’s reputation with banks, financial institutions, and strategic partners.
This blog explores how full fledged Money Changers benefit from licensing and why FFMC approval is a powerful credibility booster in today’s competitive financial landscape.
Understanding FFMC Licensing in India
A full fledge money changer license in India allows eligible entities to undertake foreign exchange transactions such as buying and selling foreign currency, traveler’s cheques, and prepaid forex cards. Governed under FEMA and regulated by the RBI, FFMCs are expected to meet strict norms related to capital adequacy, compliance, KYC, AML, and reporting.
The FFMC License in India serves as official recognition that a business meets RBI’s regulatory and financial standards, making it a trusted participant in the forex market.
Why Credibility Matters in the Forex Business
Foreign exchange transactions involve high-value funds, cross-border movement of money, and exposure to compliance risks. Banks and partners are cautious about whom they work with, as any regulatory lapse can have serious legal and reputational consequences.
Banks prefer working with entities that are directly regulated by the RBI. An FFMC license demonstrates that your business has undergone detailed scrutiny, including background checks, financial assessment, and operational review. This RBI endorsement reassures banks that the entity is compliant, transparent, and low-risk.
Banks are legally obligated to ensure that their clients comply with FEMA and RBI norms. When a business holds an FFMC License in India, banks can confidently extend services such as:
Nostro/Vostro arrangements
Cash management services
Foreign currency accounts
Payment gateway integrations
Unlicensed or informally operating entities often face repeated rejections or account freezes due to compliance concerns.
3. Reduced Due Diligence Burden
Licensed FFMCs already meet RBI’s KYC and AML requirements. This reduces the additional due diligence banks need to conduct, speeding up onboarding and strengthening long-term relationships. In contrast, non-licensed entities are subject to ongoing scrutiny, audits, and restrictions.
Strengthening Partnerships Through FFMC Licensing
1. Increased Confidence Among Business Partners
Strategic partners—such as travel companies, fintech platforms, exporters, and remittance service providers—prefer to collaborate with entities holding a valid FFMCs lincese in India. Licensing assures them that the business operates within legal boundaries and follows standardized procedures.
This credibility opens doors to:
White-label forex partnerships
Franchise and sub-agent models
Cross-border payment collaborations
2. Competitive Advantage in the Market
In a crowded forex market, having an RBI-approved FFMC license differentiates your business. Partners are more likely to choose licensed full fledged Money Changers over unregulated competitors because the risk of regulatory non-compliance is significantly lower.
This advantage often translates into higher transaction volumes and stronger commercial terms.
3. Long-Term Business Sustainability
Partnerships thrive on stability. An FFMC license signals that the business is built for long-term operations, not short-term gains. This assurance encourages partners to invest time, resources, and technology into collaborative growth.
Role of Online FFMC Licensing in Building Credibility
With regulatory processes becoming more digitized, businesses can now apply for FFMCs license online through professional consultants. Online licensing ensures:
Faster documentation and submission
Better compliance tracking
Reduced procedural errors
Opting for FFMCs license online not only simplifies the application process but also reflects a business’s commitment to transparency and modern governance—qualities highly valued by banks and partners alike.
Compliance as a Continuous Credibility Factor
Obtaining the license is only the beginning. RBI expects FFMCs to maintain ongoing compliance through:
Periodic reporting
Regular audits
Adherence to updated KYC and AML norms
Businesses that remain compliant retain their credibility and avoid penalties, suspension, or cancellation of their FFMC License in India.
Conclusion
In the foreign exchange industry, credibility is built on regulation, transparency, and trust. A Full Fledged Money Changer license is more than a legal requirement—it is a strategic asset that strengthens relationships with banks and business partners. From easier access to banking services to improved partnership opportunities, FFMC licensing lays a solid foundation for sustainable growth.
For businesses aiming to scale responsibly and build long-term trust in the forex market, securing an FFMC, full fledge money changer license in India—whether through traditional or FFMCs license online channels—is a decisive step toward success.