IPO Services in India: Why Do Companies Need Professionals

IPO Services in India

Taking a company public is a decision. For business owners, a company going public represents years of work, business growth and the opportunity to raise money for future expansion. Launching an Initial Public Offering (IPO) is not as simple, as inviting people to invest in a company.  This is where IPO Services in India become important. 

There are records to review legal requirements to meet documents to prepare and important decisions to make about valuation and pricing. Even a established business can find the process challenging if company lacks the right guidance.

Professional IPO advisors help companies understand the process of going public get ready for rules and regulations work with legal experts and make smart choices before joining the stock market. 

For businesses thinking about an IPO getting help from professionals at a stage can stop extra problems and get them ready, for the duties of being a company that is listed on the stock market. 

What Are IPO Advisory Services? 

From my experience IPO advisory services guide companies in planning, preparing and managing every stage of going public. IPO advisory services are essential, for a transition. 

An IPO allows a company to sell its shares to the public for a period. Companies often think about an IPO when they need to raise money. An IPO can help a business grow, and gives owners a chance to sell shares. An IPO also makes it easier to reach capital markets. 

However going public also creates responsibilities. Companies must meet the requirements set by the Securities and Exchange Board of India (SEBI) stock exchanges and other relevant authorities. 

Professional advisors help businesses understand these requirements and coordinate the work to comply. 

What Does an IPO Advisor Actually Do? 

Depending on their expertise and engagement, IPO advisors may assist with: 

  • Assessing whether a company is ready for an IPO 
  • Reviewing financial and business information 
  • Identifying possible regulatory or compliance gaps 
  • Helping companies understand listing requirements 
  • Coordinating with merchant bankers, auditors, and legal professionals 
  • Supporting documentation and due diligence 
  • Assisting with IPO planning and timelines 
  • Preparing management for investor discussions 
  • Helping companies understand post-listing responsibilities 

It is important to know that an IPO consultant does not automatically have the authority to perform every activity. 

In India certain IPO‑related responsibilities must be handled by registered intermediaries, such, as SEBI‑registered merchant bankers. 

An IPO consultant can provide preparation and coordination support but regulated professionals carry out their respective statutory responsibilities. 

Why Do Companies Need Professional IPO Services in India? 

Every business has its own reasons for considering an IPO. 

Some companies want capital to open new manufacturing facilities. Others may be planning acquisitions, expanding into new markets, or reducing existing debt.  Whatever the objective, an IPO requires careful preparation.  Here are some important reasons companies seek professional support. 

1. Understanding Whether the Company Is Ready for an IPO 

One of the biggest mistakes a company can make is starting the IPO process before assessing its readiness. 

A business may be generating good revenue and growing steadily, but that doesn’t automatically mean it is prepared for a public listing.  Before moving forward, companies need to examine several areas. 

These include: 

  • Financial performance and reporting 
  • Corporate governance practices 
  • Business structure and shareholding 
  • Existing loans and liabilities 
  • Legal and regulatory compliance 
  • Internal controls and record-keeping 
  • Management experience 
  • Eligibility under applicable listing requirements 

For example, imagine a manufacturing company that has expanded rapidly over the last five years. 

Its sales are increasing, and management wants to raise capital through an IPO to build another factory. 

However, during an initial review, the company discovers that some corporate records need updating and certain financial reporting processes require improvement. 

Identifying these issues before formally beginning the IPO process gives the company time to address them. 

Professional advisors can help management understand which areas need attention and what preparations should come first. 

2. Managing Complex Regulatory Requirements  

Going public means stepping into a world. Companies that plan to go public in India need to pay attention to SEBI rules stock exchange rules, company law rules and other legal obligations. 

The exact rules they must follow depend on things like the type of stock exchange they want to list on, how strong their financial position. How they structure the offer. 

For instance the rules for a mainboard IPO are not the same as the rules, for an SME IPO. 

Businesses may need assistance understanding: 

  • Applicable IPO eligibility conditions 
  • SEBI disclosure requirements 
  • Corporate governance obligations 
  • Shareholding and promoter-related requirements 
  • Financial reporting standards 
  • Stock exchange listing procedures 
  • Regulatory filings and approvals 

Missing an important requirement can lead to additional questions, corrective work, or delays. 

This is one reason businesses explore IPO Advisory services in India before making major decisions about their proposed public issue. 

3. Preparing Financial Records and Business Documents 

Financial transparency becomes especially important when a company plans to invite public investment. 

Potential investors need reliable information to understand the company’s performance, financial position, risks, and future plans. 

A company preparing for an IPO may need to review and organize: 

  • Historical financial statements 
  • Restated financial information, where required 
  • Details of assets and liabilities 
  • Outstanding borrowings 
  • Related-party transactions 
  • Tax and statutory compliance records 
  • Material business agreements 
  • Litigation and contingent liabilities 
  • Promoter and shareholding information 

Consider a growing technology company that has received several rounds of private investment. 

Financial statements may be available. The company may still need to reconcile shareholder records review earlier investment agreements and organize information, about related-party transactions. 

These details matter during IPO due diligence. 

Advisors can help coordinate the collection and review of documents so that relevant professionals have the information they need. 

How Do IPO Advisory Services in India Help With Valuation and Pricing?

Valuation is one of the important decisions during an IPO.

A company naturally wants to achieve a valuation. At the time investors want to know if the proposed price truly reflects the business’s financial position, its growth potential and the risks involved. Finding the balance is not easy. It takes analysis and a clear understanding of what the business is worth. 

Understanding Business Valuation 

There are factors that can influence how a company is valued. These include earnings, revenue, market position, industry trends and future growth opportunities. Each of these plays a part in shaping the number. The more a company can demonstrate performance and long-term promise the higher the valuation may be. It’s not just about numbers. Confidence, from investors matters too. A company that shows stability and clear direction often gets value. 

These may include: 

  • Revenue and profitability 
  • Cash flow and financial stability 
  • Industry conditions 
  • Business growth opportunities 
  • Competitive position 
  • Comparable listed companies 
  • Management quality 
  • Market sentiment and investor demand 

For example, two companies operating in the same industry may generate similar revenue but have different valuations. 

One may have stronger profitability, lower debt, and more predictable cash flows. The other may be expanding quickly but facing higher operational risks. 

Investors may assess these businesses differently.  Professional advisors can help management understand the factors influencing valuation and prepare the information needed for discussions with the merchant bankers responsible for the issue. 

Why IPO Pricing Needs Careful Planning 

IPO pricing can affect investor interest and the amount of capital raised. 

A price that investors consider too high may reduce demand, while a lower price may not fully reflect the company’s expectations.  However, pricing is not determined by a consultant alone. 

The final approach depends on the offer structure, applicable regulations, market conditions, and the responsibilities of the appointed intermediaries. 

Professional guidance helps companies approach these discussions with better preparation and realistic expectations. 

How Does an IPO Consultant in India Support the Listing Process? 

An IPO involves several professionals working together.  Depending on the issue, these may include merchant bankers, legal advisors, auditors, registrars, bankers, and other intermediaries. 

For management teams handling everyday business operations, coordinating all these activities can become demanding. 

An IPO consultant may help organize the preparation process and improve communication between the company and its professional advisors. 

Coordinating Different IPO Activities 

Support may include: 

  • Preparing an IPO readiness checklist 
  • Organizing required company information 
  • Coordinating meetings with professional advisors 
  • Tracking documentation requirements 
  • Identifying pending compliance activities 
  • Monitoring preparation milestones 
  • Helping management respond to information requests 

For instance, a company’s finance team may be working with auditors while its legal team reviews material contracts. 

At the same time, the merchant banker may require additional business information. 

A structured coordination process can help everyone understand what needs to be completed and when. 

This doesn’t replace the responsibilities of regulated intermediaries. It helps the company manage its own preparation more effectively. 

Mainboard IPO vs SME IPO: Why Choosing the Right Route Matters 

Not every company follows the same path to the stock market.  In India, eligible companies may explore a mainboard IPO or an SME IPO, depending on their size, financial position, objectives, and applicable requirements. 

Mainboard IPO 

Mainboard listings are generally associated with companies seeking access to the broader public equity market. 

Companies must satisfy the applicable eligibility, disclosure, governance, and listing requirements. 

SME IPO 

SME platforms provide a listing route for eligible small and medium-sized businesses.  However, an SME IPO is not simply an easier version of a mainboard IPO. 

It has its own eligibility conditions, issue requirements, and continuing obligations.  Before choosing a route, companies should consider: 

  • Their current financial position 
  • Capital requirements 
  • Applicable eligibility criteria 
  • Listing and ongoing compliance costs 
  • Investor expectations 
  • Long-term business plans 

Professional advice can help management compare the available options without assuming that one route suits every company. 

Common Mistakes Companies Make Before Launching an IPO 

An IPO requires planning, and some problems begin long before the company files its offer documents. 

Here are several mistakes businesses should avoid. 

Starting Without a Clear Fundraising Objective 

A company should understand why it wants to raise money. 

Is the capital intended for expansion, debt repayment, working capital, or another permitted business purpose? 

Clearly defined objectives help the company explain its plans and assess whether an IPO is the right funding option. 

Ignoring Corporate Governance 

Public companies face greater scrutiny than many privately held businesses. 

Weak internal controls, incomplete records, and unclear decision-making processes can create concerns during IPO preparation. 

Underestimating IPO Costs 

The cost of going public extends beyond advisory fees. 

Depending on the transaction, expenses may include: 

  • Merchant banking fees 
  • Legal and audit fees 
  • Registrar and other intermediary charges 
  • Regulatory and stock exchange fees 
  • Advertising and communication expenses 
  • Ongoing compliance and reporting costs 

Businesses should evaluate these costs before committing to the process. 

Expecting Guaranteed Results

An IPO does not guarantee successful fundraising, strong investor demand, or an increase in share value after listing. 

Market conditions can change, and investors may respond differently from what the company expects. 

Professional advice helps companies understand these risks, but it cannot eliminate them. 

How to Choose the Right IPO Advisory Partner

Choosing an advisory partner is an important decision because IPO preparation can involve sensitive financial information and significant business changes. 

Before appointing an advisor, companies should ask a few practical questions. 

What Should You Look for in an IPO Advisor? 

Consider the following: 

  • Experience: Has the advisor worked on IPO readiness, capital market transactions or similar assignments? 
  • Understanding of regulations: Can the advisor explain the requirements clearly? 
  • Defined responsibilities: Which activities will the advisor handle directly and which require intermediaries? 
  • Transparent fees: Are the scope of work, charges and additional expenses clearly explained? 
  • Communication: Will management receive updates, on preparation activities? 
  • Practical guidance: Can the advisor identify business- issues rather than offering only a general checklist? 

A reliable advisor should also be clear about what they cannot guarantee.  Be cautious of anyone promising SEBI approval, guaranteed listing, or assured investor returns. 

What Happens After a Company Gets Listed? 

Many businesses focus heavily on getting listed but spend less time thinking about what happens afterward. 

In reality, becoming a listed company brings continuing responsibilities.  Depending on the applicable framework, these may involve: 

  • Periodic financial disclosures 
  • Corporate governance requirements 
  • Stock exchange reporting 
  • Disclosure of material events 
  • Shareholder communication 
  • Compliance with insider trading regulations 
  • Maintenance of appropriate internal controls 

For example a company that used to share updates with just a few shareholders might have to follow much more organized ways of sharing information once it goes public. 

Leaders need to get ready, for these duties before the public offering instead of waiting to deal with them later. 

Frequently Asked Questions About IPO Services in India

1. Why does a company need IPO services? 

IPO advisory services help a company check if it is ready to go public learn about the rules and laws that must be followed get the papers ready manage the work of different experts and get ready for the duties that come with being a public company. 

2. Is hiring an IPO consultant, in India?

Hiring a separate IPO consultant is not generally mandatory. However, an IPO requires the involvement of appropriate regulated intermediaries and professionals under the applicable framework. 

3. How long does the IPO process take in India? 

There is no fixed timeline for every IPO. The duration depends on company readiness, documentation, regulatory review, market conditions, and the proposed issue structure. 

4. Can a small company launch an IPO in India? 

Yes, an eligible small or medium-sized company may consider listing through an SME platform, subject to the applicable requirements. Not every small company will qualify.

5. What is the difference between an IPO advisor and a merchant banker?

An IPO advisor may support readiness assessment, planning, and coordination. A SEBI-registered merchant banker performs regulated responsibilities associated with managing a public issue, including applicable due diligence and offer-related activities. 

6. Can IPO advisors guarantee a successful listing?

No. Advisors cannot guarantee regulatory approval, investor subscription, listing success, or future share performance. 

Conclusion

Going public can create new opportunities for a growing company, but it also requires careful preparation and long-term responsibility.  From reviewing financial records and understanding regulations to evaluating valuation expectations and preparing for investor scrutiny, every stage deserves attention.  Professional IPO Consultant in India can help businesses approach these activities in a more organized way and identify potential issues before they become larger problems. Working with an experienced IPO consultant in India can also help management understand the available listing routes, coordinate preparation activities, and make informed decisions about the company’s future. 

An IPO is not just about raising capital. It’s about preparing your business for the expectations and responsibilities that come with public ownership.  The better prepared your company is before the IPO, the stronger its foundation will be for life as a listed business. 
Mistakes to Avoid When Applying for NBFC Registration in India

NBFC registration in India

The big things to watch out for are picking the NBFC type using old rules about how much money the company needs, sending in papers that don’t match each other and having a business plan that doesn’t show how the company will work. Starting to do work before getting the proper permission is a big problem too.  NBFC Registration in India is more, than making a company and putting papers online. The Reserve Bank of India (RBI) has to check if the person applying meets the rules and can handle the financial business in the right way. 

A useful starting point is to check your business model, capital position and ownership records together. If these do not tell the same story, resolve the differences before filing. 

1. Applying Without Checking Whether Registration Is Required

Not every business connected with finance needs the same RBI registration. A company lending from its own balance sheet, a loan-service provider and a platform connecting borrowers with lenders may have different regulatory positions. 

For the general principal-business assessment, financial assets and income from financial assets are both relevant. However, category-specific rules and exemptions must also be considered. 

Before proceeding, clarify: 

  • What financial activity will the company undertake? 
  • Who will provide the money? 
  • Will the company lend directly or support another lender? 
  • Will it interact with customers? 
  • Does a specific exemption or another regulatory framework apply? 

For example, a company referring customers to an existing lender should not assume it needs the same registration as the lender. Equally, calling a lending business a “technology platform” does not remove its regulatory obligations. 

2. Choosing the Wrong Category for NBFC Registration in India

“NBFC” covers several types of financial businesses. Their permitted activities, capital requirements and operating conditions are not identical. 

A general lending business may fall within the Investment and Credit Company category. Microfinance, factoring, peer-to-peer lending and account aggregation have separate frameworks. 

Check the category against your actual plans: 

  • The products you intend to offer. 
  • Your proposed customers. 
  • Whether loans will appear on your balance sheet. 
  • Your funding arrangements. 
  • Any category-specific restrictions. 

An account aggregator, for instance, is not simply an alternative route to starting a lending company. Selecting a category because its requirements appear easier can leave your application disconnected from your intended business. 

3. Using Outdated Capital Requirements

Old articles frequently describe ₹2 crore as the capital requirement for every NBFC. That is not a safe assumption.

For new NBFC-ICC applicants undertaking ordinary customer-facing lending, the applicable minimum Net Owned Fund is generally ₹10 crore. Other categories can have different requirements. Transitional arrangements for existing companies should not be confused with entry requirements for new applicants. 

Net Owned Fund Is Not Just a Bank Balance

Net Owned Fund, or NOF, is a regulatory calculation. It involves eligible owned funds and prescribed deductions. 

Before doing an NBFC Registration, have the calculation reviewed rather than relying only on paid-up capital or money shown in the bank account. 

Check: 

  • Whether the capital qualifies for the calculation. 
  • Accumulated losses and other required deductions. 
  • Relevant investments and group exposures. 
  • Whether financial records support the stated figure. 
  • Whether sufficient capital will remain after setup expenses. 

A company may have the required paid-up capital but still need adjustments when calculating its NOF. 

4. Failing to Explain Where the Capital Came From

Having money available and being able to explain its origin are separate matters. 

The application should present a clear funding trail. Large transfers without supporting records, unexplained shareholder contributions or inconsistent disclosures can raise questions. 

Organise the relevant evidence: 

  • Bank statements showing the movement of funds. 
  • Share subscription and allotment records. 
  • Shareholder financial information. 
  • Supporting records for the source of contributions. 
  • Details of ownership and beneficial ownership. 

Suppose a promoter contributes money received from selling an asset. Keep the transaction documents and bank trail together. 

Do not treat borrowed money as qualifying owned capital merely because it has entered the company’s account. Its legal and accounting treatment matters. 

5. Submitting a Copied or Unrealistic Business Plan

A business plan should explain your proposed company, not describe the NBFC sector in general. 

Statements such as “we will provide innovative financial solutions” tell the reader very little. Explain who will borrow, how applications will be assessed and how the company will manage repayment risk. 

Include practical details about: 

  • Target customers and loan products. 
  • Customer acquisition channels. 
  • Credit assessment and approval. 
  • Funding sources. 
  • Pricing and operating costs. 
  • Collection and recovery procedures. 
  • Staffing and technology.
  • Financial projections and their assumptions.

For example, a lender serving small retailers should explain how it will assess businesses with seasonal sales or limited formal financial records. 

Projections should also allow for defaults, delays and expenses. Assuming every customer pays on time makes the plan less convincing. 

6. Ignoring Director Backgrounds and Governance

The people running the company matter as much as its capital. 

Incomplete information about directors, unexplained changes in management or missing disclosures can complicate the application. A strong professional profile does not replace accurate records. 

Review: 

  • Qualifications and relevant experience. 
  • Current and previous directorships. 
  • Regulatory or legal proceedings requiring disclosure. 
  • Conflicts of interest. 
  • Responsibilities for credit, finance and compliance. 

Avoid appointing someone only to make the application look stronger. The proposed management should be able to explain and oversee the business after registration. 

A useful test is whether each key person understands the policies and responsibilities assigned to them. 

7. Allowing Documents to Contradict Each Other 

Small inconsistencies can become a larger problem when they concern ownership, capital or the proposed business. 

For example, the business plan may describe one shareholding structure while company records show another. A director’s address may differ across documents without explanation. 

The NBFC registration process in India benefits from a coordinated document review. 

Cross-check: 

  • Company name, CIN and registered address. 
  • Shareholding and capital figures. 
  • Director details. 
  • Financial statement dates. 
  • Board resolutions. 
  • Constitutional documents and proposed activities. 
  • Signatures, certifications and attachments. 

Use one document tracker. Record who prepared each document, who reviewed it and whether an updated version has replaced it. 

8. Starting Operations Before the Necessary Approval

Company incorporation is not the same as RBI authorization. 

A business requiring registration should not commence the regulated activity merely because it has applied. An acknowledgement or application reference is also not a Certificate of Registration. 

Before launch, check: 

  • Whether the necessary registration has been granted. 
  • What activities it permits. 
  • Whether any conditions must be satisfied. 
  • Whether advertisements accurately describe the company’s status. 

The term NBFC license in India is commonly used, but the formal authorization is generally the RBI’s Certificate of Registration. 

Registration also does not automatically permit accepting public deposits. Deposit-taking authorization is a separate matter; do not build a funding plan around an assumption that customers can deposit money. 

9. Leaving Compliance Planning Until After Approval

Treating compliance as something to arrange later can leave the business unprepared. 

Policies should explain how the company will operate. A copied policy mentioning systems or teams that do not exist is unlikely to help your staff. 

Prepare for applicable requirements covering: 

  • Customer identification and KYC. 
  • Anti-money-laundering controls. 
  • Fair lending practices and disclosures. 
  • Customer complaints. 
  • Credit decisions and collections. 
  • Recordkeeping and regulatory reporting.
  • Technology security and outsourced services. 

For a digital lending model, also assess the rules governing the lender, its service providers, customer communications and data handling. 

Each policy needs an owner who understands how it will work in practice. 

10. Relying on Guaranteed Approval or Fixed Timelines

Be cautious when someone promises approval by a particular date. The RBI makes the decision, and the application may require further information. 

An NBFC registration consultant in India can help assess readiness, organise documents and coordinate responses. They cannot guarantee the regulator’s decision. 

Before appointing one, ask: 

  • What does the engagement include? 
  • Who checks the category and capital calculation? 
  • Who reviews the business plan? 
  • Are responses to regulatory queries included? 
  • What support is available after filing? 

Also check the current filing instructions. RBI’s application forms direct applicants to PRAVAAH; older guides referring to previous systems should not be followed blindly. 

Monitor communications and respond within the deadline stated in each request. 

What Should You Check Before Filing?

Before submitting NBFC Registration, arrange a final review involving the promoters, finance team and person responsible for regulatory preparation. 

Confirm that: 

  • The registration requirement and category have been assessed. 
  • Capital requirements and NOF calculations are current. 
  • Funding and ownership records are traceable. 
  • The business plan matches the proposed operations. 
  • Documents are complete and internally consistent. 
  • Management responsibilities are clear. 
  • Someone will monitor application communications. 

If an important point remains unresolved, fix it before submission. 

Frequently Asked Questions

Is Company Incorporation Enough to Start an NBFC? 

No. Incorporation only creates the company. If RBI registration is needed you must get the authorization before you start any regulated activity.

Does Every NBFC Need ₹10 Crore? 

No. The capital requirement depends on the type of NBFC. ₹10 Crore is usually required for NBFC-ICC NBFC-MFI and NBFC-Factor applicants. Other categories have rules so the amount varies. 

Can Missing Documents Be Submitted?

The RBI may ask for information after the application is filed but you should not assume that missing documents can be added later. Submitting an application is essential. Always check the document requirements before you apply. 

How Long Does Registration Take? 

There is no time for registration. It depends on the category of the NBFC how complete your application is and whether the RBI asks for details. Processing times can vary a lot. 

Can a Consultant Guarantee Approval? 

No. Consultants can help with paperwork and guidance. They cannot guarantee approval. The final decision is always, with the RBI. You should not rely on any consultant to promise success. 

Conclusion

Successful preparation for NBFC Registration in India starts with a business model, adequate capital and records that back every important statement in the application. 

Having an NBFC Registration licence in India that gives quality review and sound advice, of one that promises quick approval. Filling gaps before filing builds a base for the company both for NBFC Registration and for day‑to‑day operations.

Minimum Investment Required to Start an AIF Registration in India

AIF Registration in India

Under the standard SEBI framework, an AIF registration in India generally needs a minimum corpus of ₹20 crore per scheme. However, the minimum investment from an individual investor is usually ₹1 crore, while the sponsor or manager must also make a prescribed continuing investment in the fund. 

These are three different requirements, and understanding them is important before you start planning your fund. 

If you’re exploring AIF Registration in India, you may already know that Alternative Investment Funds allow investors to pool capital for investments in private equity, venture capital, real estate, debt and other permitted assets. 

But launching an AIF isn’t simply about collecting money from investors. You also need to choose the right fund structure, meet SEBI’s eligibility conditions, prepare legal documents and arrange the capital required to operate the fund. 

Let’s understand the investment requirements, registration process and expenses involved in setting up an AIF. 

What Is an Alternative Investment Fund (AIF)? 

An Alternative Investment Fund is a privately pooled investment vehicle that collects funds from eligible investors and invests according to a defined investment policy. 

In India, AIFs are regulated by the Securities and Exchange Board of India (SEBI). 

Unlike traditional mutual funds, AIFs generally focus on investment strategies designed for sophisticated investors who can understand the risks involved. 

Depending on their category and investment objectives, AIFs may invest in: 

  • Startups and early-stage businesses. 
  • Private equity opportunities. 
  • Infrastructure projects. 
  • Real estate-related investments. 
  • Debt and other permitted securities. 
  • Listed and unlisted securities. 
  • Other assets allowed under the applicable SEBI regulations. 

AIFs are broadly classified into Category I, Category II and Category III. Each category follows different investment strategies and regulatory conditions. 

What Is the Minimum Corpus Required to Start an AIF in India? 

For a standard AIF scheme, the minimum corpus requirement is generally ₹20 crore. 

The corpus refers to the total amount of capital committed by investors to a particular scheme. 

This doesn’t necessarily mean the entire ₹20 crore must be deposited into the fund’s bank account on the first day. 

In many AIF structures, investors make legally binding capital commitments, and the fund calls for money when investments need to be made. 

How Does the ₹20 Crore Corpus Requirement Work? 

Suppose you’re launching a Category II AIF focused on investing in growing Indian businesses. 

You secure commitments from: 

  • Investor A: ₹5 crore. 
  • Investor B: ₹4 crore. 
  • Investor C: ₹3 crore. 
  • Investor D: ₹3 crore. 
  • Investor E: ₹5 crore. 

The total committed capital is ₹20 crore. 

This illustrates how several investors can collectively meet the corpus requirement. However, the fund must also satisfy SEBI’s rules regarding eligible investors, investment commitments and fundraising. 

Are There Exceptions to the ₹20 Crore Requirement? 

Yes. Not every AIF structure follows exactly the same minimum corpus requirement. 

For example: 

  • Angel fund schemes: The prescribed minimum corpus is generally ₹5 crore. 
  • Standard Category I, II and III AIF schemes: The general minimum corpus requirement is ₹20 crore. 
  • Certain specialised AIF structures: Different conditions or exemptions may apply under SEBI’s framework. 

Before deciding on your fundraising target, check which rules apply to the category and structure you’re proposing. 

What Is the Minimum Investment Per Investor in an AIF? 

For most standard AIFs, the minimum investment from an individual investor is ₹1 crore. 

This threshold helps distinguish AIFs from investment products intended for smaller retail investors. However, there are important exceptions. 

Investment by Employees and Directors 

Employees or directors of the AIF or its manager may invest a minimum of ₹25 lakh, subject to the applicable conditions. 

Investment Through Angel Funds 

Angel funds have separate investor eligibility and investment rules. The standard ₹1 crore minimum should not automatically be applied to every angel fund arrangement. 

Accredited Investors 

SEBI’s framework provides certain relaxations for accredited investors and qualifying structures. The precise treatment depends on the applicable regulations and the fund’s structure. 

If you’re setting up an AIF, don’t assume that every investor must contribute exactly ₹1 crore. The correct threshold depends on the investor’s status and the scheme’s regulatory classification. 

How Much Must the AIF Sponsor or Manager Invest? 

One of the most overlooked expenses when starting an AIF is the sponsor’s or manager’s continuing interest. 

SEBI requires the sponsor or manager to maintain a prescribed investment in the fund so that their financial interests remain aligned with those of investors. 

Category I and Category II AIFs 

For standard Category I and Category II AIFs, the continuing interest is generally: 

  • 2.5% of the corpus, or 
  • ₹5 crore, 

whichever is lower. 

For example, if a Category II AIF has a corpus of ₹20 crore, 2.5% works out to ₹50 lakh. 

The applicable continuing interest would therefore be ₹50 lakh under the standard requirement. 

Category III AIFs 

For standard Category III AIFs, the continuing interest is generally: 

  • 5% of the corpus, or 
  • ₹10 crore, 

whichever is lower. 

For a Category III AIF with a ₹20 crore corpus, 5% would be ₹1 crore. 

These requirements can differ for certain specialised structures, including angel funds and other qualifying arrangements. 

Also, the sponsor’s or manager’s continuing interest cannot ordinarily be satisfied merely through a waiver of management fees. 

Is ₹20 Crore the Actual Cost of AIF Registration in India? 

No. This is a common misunderstanding. 

The ₹20 crore minimum corpus represents the fund’s required investor commitments. It isn’t a government registration fee or an amount that the promoter must personally pay to SEBI. 

The actual cost of establishing an AIF involves several separate expenses. 

These may include: 

  • SEBI application and registration fees. 
  • Legal documentation and fund structuring. 
  • Trust or other entity formation. 
  • Tax and regulatory advisory services. 
  • Compliance systems and professional support. 
  • Appointment of service providers. 
  • Fund administration and accounting. 
  • Audit and reporting expenses. 
  • Operational costs during fundraising. 

Your overall setup budget will depend on the fund category, legal structure and complexity of the proposed investment strategy. 

For example, a fund investing in early-stage startups may have different operational requirements from a Category III fund following a complex trading strategy. 

It’s useful to prepare two separate budgets: one for meeting the fund’s investment commitments and another for establishing and operating the fund. 

What Is the AIF Registration Process in India? 

Once you’ve decided on your fund’s investment strategy and estimated capital requirements, the next step is registration with SEBI. 

The AIF registration process in India generally involves the following steps. 

Step 1: Choose the Appropriate AIF Category 

Decide whether your investment strategy falls under Category I, Category II, or Category III. 

Your choice affects the fund’s investment restrictions, operational requirements and compliance obligations. 

Step 2: Establish the Fund Structure 

An AIF may be established as a trust, company, limited liability partnership or other permitted body corporate. 

Many AIFs in India use a trust structure, but the appropriate choice depends on the fund’s objectives and legal considerations. 

Step 3: Prepare the Required Documents 

Common documents include: 

  • Fund formation documents. 
  • Details of the sponsor and investment manager. 
  • Investment strategy and proposed fund structure. 
  • Financial and eligibility declarations. 
  • Private Placement Memorandum (PPM). 
  • Information about key investment team members. 
  • Applicable compliance policies. 

Step 4: Submit the Application to SEBI 

The applicant submits the prescribed application with the relevant documents and fees. 

SEBI reviews the information and may request clarification or additional documents. 

Step 5: Complete Registration and Scheme Requirements 

Once registration is granted, the fund must complete the applicable scheme-level requirements before raising and deploying investor capital. 

These may include filing the PPM, completing due diligence and satisfying the relevant fundraising conditions. 

How Can an AIF Registration Consultant in India Help? 

Setting up an AIF involves financial planning, legal documentation and several regulatory decisions. 

An AIF registration consultant in India can help fund sponsors understand these requirements before committing substantial resources. 

Depending on the engagement, professional assistance may include: 

  • Evaluating the proposed fund structure. 
  • Identifying the appropriate AIF category. 
  • Explaining corpus and investment requirements. 
  • Coordinating fund formation documents. 
  • Assisting with SEBI registration. 
  • Supporting preparation of the PPM. 
  • Helping address regulatory queries. 
  • Explaining ongoing compliance responsibilities. 

However, hiring a consultant doesn’t guarantee registration approval or successful fundraising. 

Before choosing a consultant, ask about their experience, services, professional fees and responsibilities during the registration process. 

Common Mistakes to Avoid When Starting an AIF 

Starting an AIF requires careful planning. A few misunderstandings can lead to unnecessary expenses or delays. 

Confusing Corpus With Registration Cost 

The minimum corpus is the amount committed by investors to the scheme. It isn’t a registration fee paid to SEBI. 

Ignoring Sponsor Contribution Requirements 

The sponsor or manager may need to maintain a prescribed continuing investment. This should be considered when planning the fund’s finances. 

Choosing the Wrong AIF Category 

Different categories follow different investment and operational rules. Selecting a category without understanding these conditions can create problems later. 

Underestimating Operational Expenses 

Even after registration, the fund may incur costs for administration, audits, compliance, valuation and investor reporting. 

Starting Fundraising Without Proper Planning 

Before approaching investors, establish a clear investment strategy, understand the applicable private placement rules and prepare the necessary documentation. 

Frequently Asked Questions About AIF Investment Requirements

1. What Is the Minimum Investment Required to Start an AIF in India? 

A standard AIF scheme generally requires a minimum corpus of ₹20 crore. The sponsor or manager must also maintain the applicable continuing investment, and the fund must satisfy SEBI’s registration and operational requirements. 

2. Can I Start an AIF With ₹1 Crore? 

₹1 crore is generally the minimum investment amount for an individual investor in a standard AIF, not the minimum corpus required to establish a scheme. A standard AIF scheme generally requires ₹20 crore in total commitments. 

3. Is the ₹20 Crore Corpus Paid to SEBI? 

No. The corpus represents capital committed by investors to the fund. SEBI registration fees and other setup expenses are separate. 

4. Can a Startup Founder Register an AIF in India?

A startup founder may participate in establishing an AIF through an eligible structure, provided the proposed fund, sponsor, manager and key personnel satisfy applicable SEBI requirements. 

5. Does Every AIF Require a ₹20 Crore Corpus? 

No. Certain specialised structures have different requirements. In particular, the angel fund framework was revised in September 2025, introducing a different approach to fundraising and investor eligibility. 

6. Is SEBI Registration Mandatory for an AIF? 

Yes. A fund seeking to operate as an AIF under SEBI’s regulatory framework must obtain the required registration and comply with applicable regulations. 

Conclusion 

Starting an Alternative Investment Fund in India is not about collecting ₹20 crore in investor commitments. There are important factors to keep in mind. You must look at the investment amount each investor has to put in. The sponsor also needs to make contributions. Then there are the registration costs and the expenses needed to run the fund day to day. 

The smartest way to start is by having an investment strategy and a realistic financial plan. When you know what the rules are, for your chosen AIF category, the process becomes much simpler. You can design the fund structure gather the required documents and move forward with registration with confidence. 

For companies that are planning to register an AIF in India, going through these requirements early can help avoid errors. It also makes the whole registration journey smoother and more manageable.

FFMC Registration Cost in India: Fees and Capital Requirements

FFMC registration in India

How much does FFMC registration cost in India? The biggest financial requirement is the capital your company must have before applying for an RBI licence. For a single-branch Full Fledged Money Changer (FFMC), the minimum Net Owned Fund requirement is ₹25 lakh. For multiple branches, it increases to ₹50 lakh. 

If you’re planning FFMC Registration in India, there’s one important thing to understand. This amount isn’t a registration fee paid to the Reserve Bank of India (RBI). It’s the minimum financial strength your company must maintain to qualify for the licence. 

Starting a foreign currency exchange business involves more than getting permission from the RBI. You’ll also need to consider office expenses, documentation, professional assistance and ongoing compliance costs. 

So, how much money should you actually plan for? Let’s break down the expenses and requirements. 

What Is an FFMC License in India? 

An FFMC, or Full Fledged Money Changer, is a company authorised by the RBI to carry out permitted foreign currency exchange activities. 

For example, someone returning from an international trip may have unused foreign currency. An authorised money changer can purchase that currency under the applicable RBI rules. 

Similarly, an FFMC may sell foreign exchange for permitted purposes, subject to regulatory conditions. 

However, an FFMC licence in India doesn’t allow a company to provide every type of foreign exchange or international payment service. Its activities are limited to what the RBI permits. 

That’s why understanding the licence and its requirements matters before investing in the business. 

What Is the Total Cost of FFMC Registration in India? 

There’s no single fixed amount that covers every expense involved in starting an FFMC business. 

The overall cost depends on whether you’re starting a new company, how many branches you want and what professional services you need. 

Here are the main expenses to consider: 

  • Minimum Net Owned Funds: ₹25 lakh for one branch or ₹50 lakh for multiple branches. 
  • Company incorporation: Expenses involved in registering a company, if you haven’t already formed one.
  • Documentation: Costs of preparing financial statements, certificates and supporting records.
  • Professional fees: Charges for assistance with the application and regulatory requirements.
  • Office setup: Rent, furniture, computers, security arrangements and other equipment.
  • Compliance expenses: Costs of maintaining records and meeting RBI requirements. 
  • Working capital: Funds needed for employees, daily operations and foreign currency inventory. 

These costs shouldn’t be confused with government registration fees. 

For example, an existing company with a suitable office may spend less on setting up operations than a newly incorporated business. 

The important thing is to calculate the total investment rather than focusing only on the minimum capital requirement. 

Minimum Capital Requirements for an FFMC License 

One of the first things the RBI considers is whether your company has sufficient Net Owned Funds, commonly called NOF. 

How Much Capital Is Required for a Single Branch? 

A company planning to operate one FFMC branch must have a minimum NOF of ₹25 lakh. 

This isn’t money you automatically deposit with the RBI. It represents the company’s qualifying financial resources. 

Meeting this requirement is necessary, but it doesn’t guarantee approval. 

What If You Want Multiple Branches? 

For a company planning to operate more than one branch, the minimum NOF requirement is ₹50 lakh. 

Suppose you want to open a currency exchange office in Delhi and later expand into Mumbai or Bengaluru. You should consider the higher capital requirement while planning your expansion. 

Opening additional branches is also subject to applicable RBI conditions. 

What Are Net Owned Funds? 

Net Owned Funds aren’t simply the amount of cash available in your bank account. 

They’re calculated based on the company’s financial position under RBI rules. 

The calculation generally considers: 

  • Paid-up equity capital. 
  • Eligible free reserves. 
  • Accumulated losses. 
  • Intangible assets. 
  • Certain investments and other applicable deductions. 

For example, a company may have ₹30 lakh in capital and reserves but still fail to meet the ₹25 lakh requirement if losses and deductions reduce its qualifying NOF. 

That’s why getting the calculation reviewed before applying is a sensible step. 

Is There an RBI Government Fee for FFMC Registration? 

Many websites mention different amounts for FFMC licensing. This can be confusing, especially when you’re trying to prepare a budget. 

The reason is that some quotations combine consultancy charges, documentation expenses and other services. 

There isn’t one universal registration package price that covers everything. 

Before paying a consultant, ask for a breakdown of: 

  • Any applicable official charges. 
  • Professional consultancy fees. 
  • Documentation and certification costs. 
  • Company incorporation expenses, if required. 
  • Additional charges for follow-up assistance. 

Don’t assume that every amount quoted as an FFMC registration fee is payable to the RBI. 

It’s always better to confirm the applicable requirements and charges before submitting your application. 

What Documents Are Required for an FFMC License? 

Preparing your documents carefully can help prevent unnecessary delays. 

The documents generally include: 

  • Certificate of Incorporation. 
  • Memorandum and Articles of Association permitting money-changing activities. 
  • Latest audited financial statements. 
  • Auditor’s certificate confirming Net Owned Funds. 
  • Previous three years’ audited financial statements, wherever applicable. 
  • Confidential report from the company’s banker. 
  • Board resolution approving the proposed business. 
  • Details of associated financial-sector companies. 
  • Required regulatory and legal declarations. 
  • Declaration regarding the proposed KYC, AML and CFT compliance framework. 

The exact documents should be confirmed against the applicable RBI requirements. 

Can Documentation Increase Registration Costs? 

Yes, particularly if your company’s existing records need updating. 

For instance, if your Memorandum of Association doesn’t permit money-changing activities, you may need to amend it. 

Similarly, preparing financial certificates or correcting incomplete records may involve professional charges. 

Reviewing these documents early can help you avoid repeated corrections. 

How to Apply for FFMC Registration in India 

The application process involves several steps, and each one deserves attention. 

Step 1: Check Your Company’s Eligibility 

Make sure your company meets the applicable NOF requirement and other RBI eligibility conditions. 

The company’s management and directors must also satisfy relevant suitability requirements. 

Step 2: Prepare the Required Documents 

Collect incorporation records, audited financial statements, the NOF certificate and other supporting documents.  Check everything before submission. 

Step 3: Submit the Application 

The application must be submitted through the RBI’s prescribed process, including APConnect where applicable.  Follow the current filing instructions issued by the RBI. 

Step 4: RBI Reviews the Application 

The RBI may examine: 

  • The company’s financial position. 
  • Background and suitability of directors. 
  • Proposed business activities. 
  • Regulatory declarations. 
  • Supporting documents and compliance arrangements. 

Additional information may be requested during the review. 

Step 5: Complete the Approval Requirements 

If the application is approved, the company must satisfy any applicable conditions before starting money-changing operations. 

Submitting an application alone doesn’t authorise a company to conduct foreign exchange business. 

What Other Expenses Should You Consider? 

Many entrepreneurs arrange the required capital but underestimate what it costs to operate the business.  Apart from licensing-related expenses, you’ll need to budget for everyday operations. 

Office and Infrastructure 

Your office may require furniture, computers, security equipment and reliable internet connectivity.  Rent and security deposits will depend on the location. 

Employees and Training 

Staff members must understand customer verification, transaction documentation and applicable regulatory requirements. 

Employee salaries and training expenses should be part of your budget. 

Technology and Compliance 

You’ll need suitable systems to maintain transaction records, customer information and regulatory reports. 

Ongoing compliance may also involve accounting, audits and internal controls. 

Working Capital 

You’ll need sufficient liquidity to manage operating expenses and foreign currency inventory. 

The minimum NOF requirement shouldn’t be confused with the total working capital needed to run the business. 

How Can an FFMC Registration Consultant Help? 

Applying for an RBI-regulated licence can feel complicated, especially if you’re unfamiliar with financial documentation and regulatory procedures. 

An FFMC registration consultant can help you understand the requirements and prepare your application properly. 

Depending on the services offered, assistance may include: 

  • Reviewing company eligibility. 
  • Checking capital requirements. 
  • Helping prepare application documents. 
  • Coordinating financial certificates. 
  • Assisting with application submission. 
  • Helping respond to RBI queries. 
  • Explaining compliance obligations. 

However, a consultant cannot guarantee approval. The final decision rests with the RBI. 

Before hiring someone, ask what’s included in their fees and whether additional assistance will cost extra.  A clear quotation can help you avoid unexpected expenses. 

Common Mistakes That Can Increase FFMC Registration Costs 

Some expenses are unavoidable, but others happen because applicants begin without understanding the requirements. 

Confusing Capital With Government Fees 

The ₹25 lakh and ₹50 lakh amounts are NOF requirements, not government application fees. 

Treating them as registration charges can lead to incorrect financial planning. 

Applying Without Checking Eligibility 

A company may have sufficient funds in its bank account but still fail to meet the required NOF after applicable deductions. Check the calculation before applying. 

Ignoring Ongoing Compliance Costs 

Getting the licence is only the beginning.  Customer verification, reporting, record-keeping, and internal controls involve continuing responsibilities and expenses. 

Planning Multiple Branches Too Early 

Expansion involves additional capital and regulatory requirements. 

It’s better to consider these costs before committing to new premises. 

Frequently Asked Questions

1. How Much Does FFMC Registration Cost in India? 

The total expense depends on documentation, professional assistance, office setup and business operations. The minimum NOF requirement is ₹25 lakh for one branch and ₹50 lakh for multiple branches. These are capital requirements, not registration fees.

2. Is ₹25 Lakh Paid to the RBI? 

No. ₹25 lakh represents the minimum Net Owned Funds required for a single-branch FFMC. It isn’t a licence fee paid to the RBI.

3. Can an Individual Apply for an FFMC License? 

No. An FFMC licence is issued to an eligible incorporated company that meets the applicable RBI requirements. 

4. Is Hiring an FFMC Registration Consultant Necessary?

Not necessarily. However, professional assistance can be useful for preparing documents, understanding eligibility requirements and handling application-related queries.

5. Does Meeting the Capital Requirement Guarantee Approval? 

No. The RBI also reviews the company’s suitability, documents, management and other regulatory requirements. 

6. Are There Expenses After Receiving the License? 

Yes. Businesses need to budget for employees, office operations, technology, compliance, audits, and working capital.

Conclusion 

Starting an FFMC business requires more than arranging the minimum capital to get some with that you can hire an FFMC registration consultant. You also need to think about documentation, professional assistance, office expenses, and the cost of meeting regulatory requirements once operations begin. 

Before applying, check your company’s financial eligibility and prepare a realistic budget. Understanding the expenses early can help you avoid unnecessary costs and make better decisions about starting your foreign currency exchange business.

IPO Services in India: Timeline, Stages and Delays

IPO services in India

Once a company begins thinking about going public, the first question people usually ask is “When can we go public?” It makes sense. Leaders want to prepare for the money owners want to know for sure. Everyone needs a date to aim for. But before comparing IPO services in India, it helps to understand what that date depends on. The public offer is only the final stretch of a much longer project. 

Some companies arrive with organized records, clear ownership, and a team ready to answer questions. Companies that bring organized records show that they value order. Companies that have ownership never get lost in responsibility. Companies, with a team can respond quickly to any query. Other companies discover documents or unresolved compliance issues during preparation. Those differences can change the schedule considerably. 

A useful IPO timeline starts with the company’s current position. It should explain what needs doing, who will do it and what could hold things up. 

How Long Does an IPO Take in India? 

An IPO in India is generally a months-long project.  

There is no one end-to-end deadline that applies to every company. Companies that need a lot of preparation, changing their structure or fixing things they did wrong, may take much longer than companies that are already ready to file. Each company is different. Some are not prepared at all. Some are almost ready. The time needed depends on what each company has to do. Some have more work to do than others. That is why the timeline can be different for each business. 

The timetable after the public issue closes is much shorter. SEBI’s T+3 framework provides for listing within three working days of issue closure. That is the final listing stage—not the time needed to prepare and complete an IPO. 

When someone quotes a timeline, ask what they are counting from: 

  • The first readiness assessment? 
  • Appointment of the merchant banker? 
  • Filing of the draft offer document? 
  • Completion of the review process? 

An estimate becomes useful only when its starting point and assumptions are clear. 

What Happens Before a Company Can Launch Its IPO? 

Several teams work on an IPO together. Some tasks can move in parallel, while others have to wait for earlier work. 

1. Checking whether the company is ready 

Before setting a launch target, the advisers need to understand the business and assess the appropriate listing route. 

This means looking at: 

  • Applicable eligibility requirements. 
  • Financial history and reporting. 
  • Ownership and capital structure. 
  • Governance arrangements. 
  • Outstanding compliance matters. 
  • Funding needs and proposed use of proceeds. 

This review may reveal that the company is ready to proceed. It may also identify work that needs attention before filing. 

For example, strong sales do not compensate for unclear ownership records. Both need to be examined. 

2. Choosing the route and appointing the team 

SME and mainboard listings have different requirements. Choosing between them should begin with eligibility and suitability, rather than a promise that one will be quicker. 

The company then needs the appropriate advisers and intermediaries, including merchant bankers, auditors, legal advisers and a registrar. 

An IPO consultant in India may help with readiness and coordination. That role does not replace the responsibilities of the SEBI-registered merchant banker. 

Agree early on: 

  • Who manages the timetable. 
  • Who provides each set of documents. 
  • Who reviews the information. 
  • Who follows up on queries. 
  • Who resolves decisions requiring management approval. 

Without clear responsibilities, even straightforward requests can get stuck. 

3. Preparing financial information and completing due diligence 

This is where the preparation becomes detailed. 

The team examines financial information, corporate records, material agreements, litigation, licences and other matters relevant to the offer. 

Auditors and advisers may ask for evidence behind figures or statements management uses routinely. 

Suppose the company describes a customer relationship as long-term. The contract, however, allows the customer to leave at short notice. The offer document needs to reflect the agreement. 

Due diligence is about making sure the information can be supported, not simply gathering files into a folder. 

4. Drafting the offer document 

For a conventional mainboard IPO, the draft red herring prospectus, or DRHP, contains detailed disclosures about the company and proposed offer. 

These include: 

  • The business and its operations. 
  • Financial information. 
  • Risk factors. 
  • Promoters and management. 
  • Material litigation. 
  • The proposed use of funds. 

Drafting takes coordination. Finance, operations and management may describe the same issue differently, and those differences need to be resolved. 

Filing the draft is a significant milestone. It does not make the launch date certain. 

What Happens After the Draft Is Filed? 

The company moves into the applicable review process, followed by preparation for launch. 

Responding to questions 

SEBI and the stock exchanges may seek information, clarification or revised disclosures through their respective processes. 

A query can require input from several people. The lead manager may need an explanation from management, supporting records from finance and confirmation from an auditor. 

SME offer-document scrutiny follows the relevant exchange process under the applicable framework. It should not be treated as identical to the conventional mainboard route. 

This is why a review period should not be presented as a guaranteed countdown from the first filing. 

Getting ready to open the offer 

Once the relevant requirements have been addressed, preparation continues. 

The team may need to: 

  • Update disclosures and financial information. 
  • Complete offer documents and filings. 
  • Finalise the offer structure. 
  • Coordinate investor communication. 
  • Complete operational arrangements. 
  • Choose a suitable launch window. 

Being procedurally ready does not necessarily mean management will launch immediately. Investor feedback and market conditions still matter. 

Opening the issue and listing 

The public subscription window is measured in days. After closure, the intermediaries complete the applicable allotment, funds-unblocking, share-credit and listing steps. 

The T+3 framework provides for listing within three working days of closure. 

Working days are important. Holidays affect the calendar, so simply adding three ordinary days can give the wrong date. 

What Commonly Delays an IPO? 

Some delays are external. Others begin with information or decisions inside the business. 

Financial records need further work 

A company’s accounts may need reconciliations, explanations or supporting evidence before the offer information is ready. 

Common pressure points include: 

  • Revenue recognition. 
  • Related-party transactions. 
  • Outstanding balances. 
  • Subsidiary records. 
  • Missing documentation. 

If a figure cannot be supported, drafting faster will not solve the problem. The underlying records need attention. 

Shareholding records do not match expectations 

Historical allotments, transfers and approvals may need checking. 

For example, a founder may believe an investor holds a particular percentage, while the available records show inconsistencies. Advisers need to establish the correct position. 

Finding this early is far easier than discovering it when documents are almost ready. 

Management takes too long to respond 

The IPO team needs information from several departments. A request that looks small can stop progress if nobody owns it. 

Appointing an internal coordinator helps. Give that person: 

  • A document tracker. 
  • Named information owners. 
  • Response dates. 
  • Access to senior decision-makers. 
  • A way to escalate unresolved questions. 

Advisers cannot answer every business question on management’s behalf. 

The company changes its plans 

Management may revise the issue size, use of proceeds, selling shareholders or business structure.

Changes can be sensible. They still need to be assessed for their effect on disclosures, approvals and the schedule.

I would suggest asking that question before agreeing to a change of after the team has rewritten the documents. 

Pricing expectations differ from investor feedback 

I believe the valuation shareholders want may not match what investors are prepared to accept. 

That gap can lead to changes, in pricing, structure or timing. Advisers can help interpret demand. Cannot guarantee subscription or a favourable listing price. 

Waiting creates additional preparation 

A postponed launch may require refreshed financial information and updated disclosures. 

This can be frustrating: documents were completed, yet more work appears. But the offer needs to reflect the relevant position at launch. 

Build room for updates into the project instead of assuming preparation ends permanently with the first draft. 

Is an SME IPO Always Faster Than a Mainboard IPO? 

No. The routes differ, but neither guarantees a shortcut. 

An SME issue still needs applicable eligibility, financial preparation, due diligence, disclosures and arrangements such as market making. 

A mainboard company may have more complex operations, subsidiaries and documentation. It may also have a stronger internal team and better-organised records. 

The useful comparison is between the actual preparation required—not just the names of the platforms. 

For mainboard IPO advisory, ask the team to separate: 

  • Requirements already met. 
  • Tasks that can run together. 
  • Issues preventing filing. 
  • External review dependencies. 
  • Decisions needed before launch. 

That gives management a workable picture of the project. 

How Can a Company Reduce Avoidable Delays? 

You cannot control every review question or market movement. You can make your own preparation more dependable. 

Organise the data room properly 

Collect the relevant documents early: 

  • Corporate and ownership records. 
  • Financial information. 
  • Material contracts. 
  • Licences and approvals. 
  • Litigation information. 
  • Intellectual property documents. 

Use clear filenames and version control. Five different copies of an agreement create confusion; one verified version saves time. 

Keep management involved 

An IPO cannot be handed entirely to advisers. 

Schedule regular meetings focused on outstanding items and decisions. Senior management should resolve issues that departmental teams cannot. 

The aim is to remove obstacles, rather than repeatedly report that they exist. 

Plan around milestones 

Use milestones such as: 

  • Readiness review completed. 
  • Financial information prepared. 
  • Draft document filed. 
  • Review questions addressed. 
  • Launch arrangements completed. 
  • Offer opened and closed. 

Revisit target dates when assumptions change. An updated schedule is more useful than repeating a date that no longer reflects reality. 

What Should You Ask Before Hiring IPO Advisers? 

When comparing IPO services in India, request a plan based on your company’s records and circumstances. 

Ask:

  • What needs fixing before filing?
  • Which assumptions support the estimate?
  • Who will act as merchant banker?
  • What must management provide?
  • What could require updated documents?
  • How would delays affect costs?
  • What support continues after listing?

Be cautious about guaranteed listing dates. A credible team should explain both its responsibilities and the parts it cannot control.

Frequently Asked Questions:

Does T+3 mean an IPO takes three days?

No. It concerns listing after issue closure. Preparation, filing and review happen beforehand.

Can the issue open immediately after DRHP filing?

No. The company must complete the applicable review and launch requirements.

Does regulatory review guarantee a safe investment?

No. Review should not be presented as an endorsement of valuation, investment quality or future returns.

Can a company postpone its IPO?

Yes, subject to applicable validity and regulatory requirements. Updates or further filings may be needed.

Should a company depend on IPO proceeds for an urgent payment?

That creates timing risk. Assess suitable alternative funding rather than relying on an uncertain launch date.

Does preparation end on listing day?

No. Listed companies have continuing disclosure, governance and other compliance obligations. Plan for that transition before listing.

Conclusion 

A realistic IPO schedule comes from understanding what is prepared, what needs work and who is in charge of each part. A lot of the work takes place before investors see the offer so checking early can stop issues from appearing late. 

Before choosing a date ask an IPO consultant in India to show you the steps and the ideas behind the plan. You should leave with an idea of what your team has to do next what might change the plan and how you will track the progress.

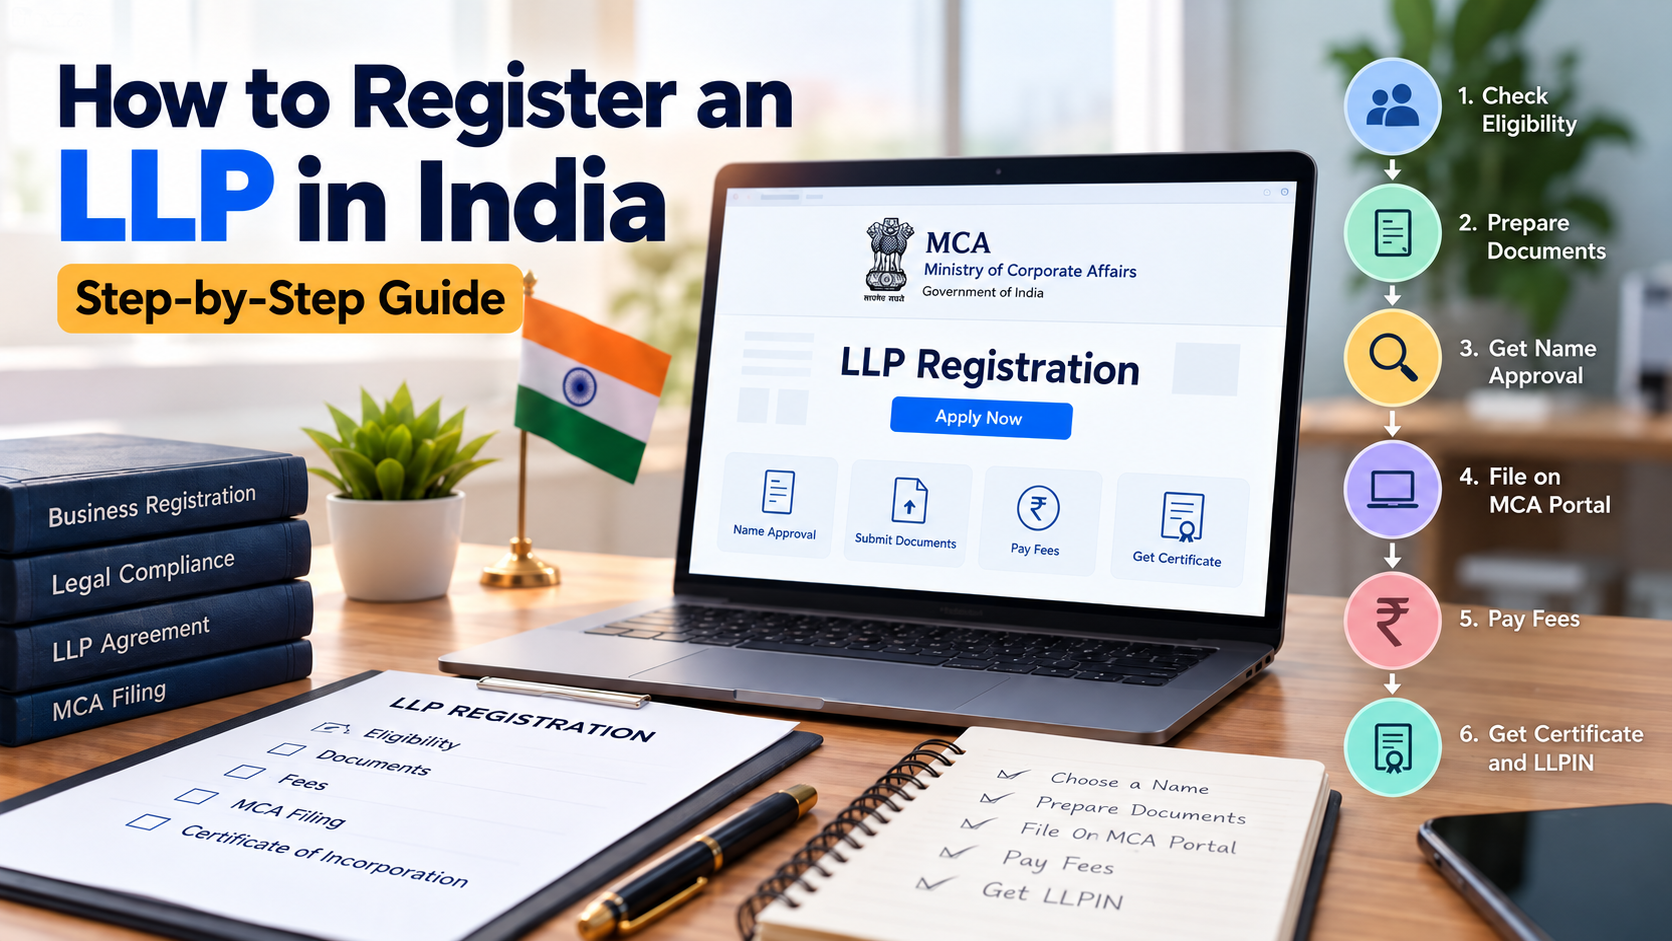
How to Register an LLP in India: Step-by-Step Guide 

LLP registration in India

To complete LLP registration in India, you must have at least two partners. You also need digital signatures and a business name that follows the rules. The required documents include identification proof, address proof, and other basic details. You can apply online through the Ministry of Corporate Affairs portal using the FiLLiP form. After submitting your application, it will be reviewed. Once approved, you will receive the LLP Certificate of Incorporation. This certificate confirms your LLP is officially registered. 

Starting a business involves decisions, and I think choosing a business structure is one of the most important decisions. You might be wondering whether to register a limited company, start a traditional partnership or go with an LLP. 

For many small businesses, consultants, and Entrepreneurs, an LLP is often a good option. Limited liability partnerships offer versatility in how the business is run, plus limited liability coverage. 

The process of registration may seem daunting at first, but becomes much easier when you understand the fundamentals. 

What Is an LLP and Why Do Businesses Choose It? 

An LLP, also called a Limited Liability Partnership, is a business structure that mixes some features of a partnership with the benefits of a legal entity. The LLP, or Limited Liability Partnership, gives partners protection while letting the business act as its legal entity. 

It is governed by the Limited Liability Partnership Act, 2008. 

In a partnership the partners can be responsible for the debts of the business. In an LLP there is liability, which means the partners are not automatically responsible, for all the debts of the LLP. 

However, this protection has exceptions, including situations involving fraud or personal wrongdoing. 

What Are the Main Benefits of LLP Registration? 

There are several reasons entrepreneurs consider registering an LLP: 

  • Limited liability protection: Partners generally have protection from business liabilities beyond their agreed contribution, subject to legal exceptions. 
  • Separate legal identity: The LLP can own assets, sign contracts, and operate in its own name. 
  • Flexible management: Partners can decide how they want to manage the business through an LLP agreement. 
  • No general minimum capital requirement: You don’t need a large initial contribution to register an LLP. 
  • Business continuity: The LLP continues to exist even when partners change. 
  • Suitable for small businesses: Consultants, agencies, and professional service providers often find this structure useful. 

For example if two friends want to start a marketing agency an LLP makes it possible for them to run the business under one business name. At the time it clearly shows what each person is responsible, for. It also explains how the money they make will be shared between them. 

Who Can Register an LLP in India? 

Before beginning the LLP registration process, it’s important to check whether you meet the basic requirements. 

To register an LLP, you generally need: 

  • At least two partners. 
  • At least two designated partners who are individuals. 
  • At least one designated partner who meets the legal requirement for residency in India. 
  • A registered office address in India. 
  • A lawful business activity. 
  • A business name that follows MCA naming rules. 

Individuals and eligible body corporates can become partners, subject to applicable requirements. 

Can Two People Start an LLP? 

Yes, two people can register an LLP together. 

Lets say you and a friend are thinking about starting a consulting business. You both can become partners. Decide how much each person will put in who will handle the daily work and how the money, from profits will be split. 

These details can later be included in your LLP agreement. 

What Documents Are Needed for LLP Registration? 

One of the easiest ways to avoid delays is to prepare your documents before starting the application. 

The exact LLP registration documents may vary depending on the partners and registered office. 

Documents Required from Partners 

You may need: 

  • PAN card for Indian partners, where applicable. 
  • Aadhaar card, passport, or other accepted identity proof. 
  • Residential address proof. 
  • Digital Signature Certificate (DSC) for the required signatories. 
  • Existing DIN or DPIN details, if available. 
  • Other supporting documents requested for the application. 

Foreign partners may need additional documents that are notarised, apostilled, or authenticated, depending on their circumstances. 

Documents Required for the Registered Office 

For the business address, keep the following ready: 

  • Address proof of the registered office. 
  • Recent utility bill. 
  • Rent or lease agreement, if applicable. 
  • No Objection Certificate (NOC) from the property owner, where required. 

You don’t necessarily need a commercial office to register an LLP. A residential address may also be used if the applicable documentation and permissions are in place. 

How to Register an LLP Online in India? 

The registration process takes place through the official MCA portal. You can complete the application online, although preparing the documents and obtaining digital signatures may take some time. 

Here’s how the process works. 

Step 1: Get Digital Signature Certificates 

Since LLP registration is completed online, the required incorporation documents need digital signatures. 

A Digital Signature Certificate, commonly called a DSC, allows authorised individuals to sign electronic documents securely. 

Before filing the application: 

  • Obtain valid DSCs for the required signatories. 
  • Check that the details match their identity documents. 
  • Associate the DSCs with the relevant MCA accounts where required. 

It’s better to complete this step early rather than discover a signature problem while submitting the application. 

Step 2: Choose a Name for Your LLP 

Choosing a business name is exciting, but you can’t simply pick any name you like. 

The MCA has rules to prevent businesses from registering names that are identical or confusingly similar to existing entities. 

Before finalising your name: 

  • Search for similar company and LLP names. 
  • Check for possible trademark conflicts. 
  • Avoid restricted or misleading words. 
  • Choose something relevant to your business. 
  • Make sure the proposed name ends with “LLP” or “Limited Liability Partnership.” 

For example, if you’re starting a design consultancy, you could choose a distinctive name that reflects your services rather than a very common business name. 

Step 3: Apply for Name Approval 

Once you’ve shortlisted a name, the next step is to submit it for approval. 

You can use the MCA’s RUN-LLP service for separate name reservation or propose a name through the FiLLiP incorporation application, subject to the portal’s requirements. 

The Registrar checks whether the proposed name meets the applicable rules. 

If the name is approved, you can proceed with incorporation. If it isn’t, you may need to choose another name or address the issues raised. 

Remember, getting a name approved doesn’t mean your LLP is registered yet. 

Step 4: Fill Out the FiLLiP Form 

This is the main part of the registration process. 

FiLLiP stands for Form for Incorporation of Limited Liability Partnership. 

You’ll need to provide information such as: 

  • Proposed LLP name. 
  • Registered office address. 
  • Nature of business activities. 
  • Partner and designated partner details. 
  • Capital contribution information. 
  • Required identity and address details. 
  • Supporting documents and declarations. 

Eligible applicants may also request DIN/DPIN allotment through the incorporation process, within the applicable limits. 

Take your time while completing this form. 

A spelling mistake in a partner’s name or a mismatch in address details may result in a request for corrections. 

Step 5: Submit the Required Consent and Documents 

The proposed designated partners must provide the necessary consent to act in that role. 

Depending on the application, this may involve Form 9 and other supporting documents. 

Before submitting, make sure: 

  • The information matches the supporting documents. 
  • All required declarations are included. 
  • The relevant forms are digitally signed. 
  • Any necessary professional certification is completed. 

If you’re unsure about a particular requirement, getting professional assistance at this stage may help avoid resubmission. 

Step 6: Pay the LLP Registration Fees 

After completing the application, you’ll need to pay the applicable government filing fees. 

The LLP registration fees India applicants pay depend on the relevant MCA fee schedule and contribution details. 

Other expenses may include DSC charges, stamp duty, and professional assistance. 

Once the application is submitted, you’ll receive a Service Request Number (SRN), which can be used to track its status. 

Step 7: Receive Your LLP Certificate of Incorporation 

After submission, the Registrar reviews the application. 

If the information and documents meet the requirements, the LLP is incorporated. 

You’ll receive: 

  • Certificate of Incorporation. 
  • LLP Identification Number (LLPIN). 
  • Official registration details. 

Your LLP now exists as a separate legal entity. 

However, there are still a few important things to complete before settling into normal business operations. 

How Much Does LLP Registration Cost in India? 

There’s no single amount that every entrepreneur pays to register an LLP. 

The overall cost depends on the number of partners, contribution details, state-specific stamp duty, and whether professional assistance is required. 

Some common expenses include: 

  • DSC charges: For obtaining the required digital signatures. 
  • Name reservation fees: If a separate name reservation application is used. 
  • MCA filing fees: Government charges for incorporation. 
  • Stamp duty: Applicable to the LLP agreement under relevant state rules. 
  • Professional charges: If you hire a consultant, CA, CS, or advocate. 

Before paying for a registration package, ask what’s included. 

For example, a consultant may quote a registration fee that doesn’t include stamp duty or DSC charges. Checking these details beforehand can help you plan your budget. 

How Long Does LLP Registration Take? 

Many entrepreneurs want to know how quickly they can start operating under their registered LLP. 

The timeline depends on how quickly documents are prepared, whether the proposed name is accepted, and how long MCA processing takes. 

A straightforward application may be processed within several working days, but the timeline isn’t guaranteed. 

Common reasons for delays include: 

  • Proposed name rejection. 
  • Missing documents. 
  • Incorrect partner information. 
  • Digital signature problems. 
  • Incomplete forms. 
  • Requests for additional clarification. 

The simplest way to avoid unnecessary delays is to review everything carefully before submitting the application. 

What Should You Do After LLP Registration? 

Getting the Certificate of Incorporation is a major step, but your responsibilities don’t end there. 

There are a few important formalities to complete. 

Prepare and File the LLP Agreement 

An LLP agreement explains how the partners will run the business. 

It usually covers: 

  • Capital contributions. 
  • Profit and loss sharing. 
  • Roles and responsibilities. 
  • Decision-making powers. 
  • Admission and retirement of partners. 
  • Dispute resolution. 

The initial agreement is generally filed using LLP Form 3 within 30 days of incorporation. 

Open a Business Bank Account 

Once your LLP is registered, you can apply for a current account in its name. 

The bank will usually ask for incorporation documents, identification details, and other KYC information. 

Check Additional Registration Requirements 

Depending on your business activities, you may also need: 

  • GST registration, if applicable. 
  • PAN and TAN-related formalities. 
  • Shops and Establishments registration. 
  • Industry-specific licences. 
  • Other registrations required under applicable laws. 

Not every registration is mandatory for every LLP. 

Keep Track of Annual Compliance 

Even after registration, LLPs must meet ongoing filing requirements. 

These generally include: 

  • Filing LLP Form 11 for the annual return. 
  • Filing LLP Form 8 for the Statement of Account and Solvency. 
  • Maintaining accounting records. 
  • Filing income tax returns. 
  • Completing applicable audit requirements. 

Missing important deadlines can result in additional fees and other consequences. 

What Common Mistakes Should You Avoid During LLP Registration? 

Most registration problems don’t happen because the process is impossible to understand. They often happen because small details are overlooked. 

Some common mistakes include: 

  • Choosing a name without checking its availability. 
  • Submitting outdated address proof. 
  • Entering incorrect partner details. 
  • Uploading incomplete documents. 
  • Using invalid digital signatures. 
  • Forgetting to file the LLP agreement after incorporation. 
  • Selecting an LLP without considering future investment plans. 

For example if you want to raise venture capital by issuing equity shares a private limited company might be the structure. A private limited company can suit you better. 

It is worth thinking about your long‑term plans before you make the decision. 

LLP vs Private Limited Company: Which Should You Choose? 

Both LLPs and private limited companies offer liability protection. However the ownership and management structures of a limited company differ from those of an LLP. 

An LLP may be a good fit if you: 

  • Want flexible management arrangements. 
  • Plan to run a consulting or professional services business. 
  • Don’t need to issue equity shares. 
  • Prefer a partnership-style business structure. 

A private limited company may be more suitable if you: 

  • Plan to raise equity funding. 
  • Want to issue shares to investors. 
  • Intend to introduce employee stock options. 
  • Need a corporate ownership structure for future expansion. 

I think neither option is automatically better. The decision should depend on how you plan to operate and grow your business. 

Frequently Asked Questions: LLP Registration 

Can I register an LLP online without visiting an MCA office? 

Yes. The application for incorporation is sent online via the MCA website. You will still need the necessary papers, electronic signatures and any relevant professional licenses. 

Is there a minimum capital requirement for LLP registration? 

No. There is no general statutory minimum capital contribution for registering an LLP in India. Partners can decide their contributions based on the needs of the business.

Can one person register an LLP? 

No. An LLP must have at least two partners. Someone starting a business alone may consider other suitable business structures. 

Is GST registration compulsory for an LLP? 

Not always. GST registration depends on turnover, business activities, and other applicable legal requirements. LLP incorporation alone doesn’t automatically make GST registration mandatory. 

Can I use my home address for LLP registration?

Yes. A residential address may be used as the registered office if the necessary address proof and permissions are available. 

What happens if my LLP name is rejected? 

You may need to submit another suitable name or make corrections according to the Registrar’s instructions. 

Is filing the LLP agreement compulsory? 

The initial LLP agreement must generally be filed with the Registrar through Form 3 within 30 days of incorporation. It also helps define the rights and responsibilities of the partners. 

Conclusion 

Registering an LLP in India may seem like a lengthy process when you’re doing it for the first time. But once your documents are ready and you understand the MCA filing steps, the process becomes easier to follow. 

From choosing a suitable name to submitting the FiLLiP form and completing post-registration formalities, each step matters. 

Online LLP registration in India can be a practical option for entrepreneurs who want limited liability protection and flexibility in managing their business. 

Before applying, take some time to understand the requirements, compare business structures, and plan for ongoing compliance. Making the right decisions at the beginning can save you considerable effort later. 

Annual Compliance Cost of a Private Limited Company in India

Annual Compliance Cost of a Private Limited Company in India

For a private limited company in India, a good starting budget of ₹25,000 to ₹60,000 per year is needed for annual compliance costs. Things like bookkeeping, GST and TDS work, difficult audits, government charges, and filings that happen at times can make the total go over ₹1 lakh. These are estimates from professionals. They are not the prices set by the government. They are also not a promise of a package, with all costs included. 

Published provider estimates vary substantially in scope. Treat the range as a starting point for obtaining itemised quotations rather than a minimum amount every company must pay. 

What does annual compliance cost of a private limited company include? 

Annual compliance cost is the money you spend on keeping company records preparing accounts arranging audits that are required and finishing any filings that must be done. 

It usually has several parts: 

  • Professional fees: Charges for accounting, audit, tax work and company-secretarial support. 
  • Government fees: Amounts payable for applicable statutory filings. 
  • Recurring operational compliance: GST, TDS and payroll-related work where applicable. 
  • Event-based work: Additional filings triggered by changes to directors, share capital or the registered office. 
  • Support costs: Accounting software, digital signature renewal and document management. 

Keep these expenses separate from corporate income tax, GST payable and other tax liabilities. Paying an accountant to file a return is different from paying the tax shown in that return. 

Company incorporation is another separate expense. A registration package does not automatically cover the following year’s compliance. 

How much should a startup budget for annual compliance? 

Start with your activity level and the services you actually need. 

What should a straightforward company expect? 

For a company with clean books, limited transactions and straightforward ownership, use ₹25,000–₹60,000 as an initial professional-service budget to test against quotations. 

Check whether that amount covers: 

  • Preparation of annual accounts. 
  • Statutory audit. 
  • Annual ROC filings. 
  • Company income-tax return preparation. 
  • Routine company-secretarial documentation. 

Do not assume these services are all included merely because a provider uses the phrase “annual compliance.” 

Why can the annual cost exceed ₹1 lakh? 

An increase in costs can be seen when the company needs: 

  • Monthly bookkeeping across several bank accounts. 
  • Regular GST or TDS return preparation. 
  • Payroll and employee-related compliance. 
  • Inventory accounting or transaction reconciliation. 
  • Foreign-investment or cross-border support. 
  • Tax audit, transfer-pricing work or specialised reporting, where applicable. 
  • Correction of past records and overdue filings. 

An advertised package may be reasonably priced for its stated scope while covering only part of your company’s needs. 

Action: Request separate prices for core annual compliance, recurring accounting and tax work, and additional filings. 

Which core obligations should a private limited company plan for? 

For an ordinary active private limited company, the baseline includes maintaining accounts, statutory audit, corporate records and applicable annual filings. Low turnover alone does not remove company-law audit requirements.  

What accounting and statutory audit work is involved? 

Bookkeeping means recording transactions and reconciling them with invoices, bank statements and other evidence. 

Statutory audit is the independent examination of financial statements under applicable company law. It is different from maintaining the books. 

Budget for: 

  • Recording income and expenses. 
  • Bank and payment reconciliation. 
  • Reviewing receivables and payables. 
  • Preparing financial statements. 
  • Supporting the auditor’s questions and evidence requests. 
  • Finalising the audit report and relevant documentation. 

Audit fees depend on the work involved, including transaction complexity and the condition of the records. Turnover is one factor, not the only factor. 

Action: Confirm whether your quote includes bookkeeping, accounts preparation and statutory audit as distinct services. 

What are AOC-4 and MGT-7 or MGT-7A? 

These filings serve different purposes: 

  • AOC-4: Filing financial statements and required accompanying documents, using the applicable form or variant. 
  • MGT-7: The annual return for companies outside the OPC and small-company categories. 
  • MGT-7A: The abridged annual return for OPCs and eligible small companies.  

An annual return reports corporate information; it does not replace the financial-statements filing. 

For an ordinary company, financial statements are generally filed within 30 days of the AGM, and the annual return within 60 days of the AGM, subject to applicable provisions, exceptions and extensions.  

Action: Ask your company secretary to identify the correct forms and calculate your actual deadlines. Avoid using the same calendar date for every company. 

Does a company need an income-tax return if it has no profit? 

Yes. The Income Tax Department states that companies must file a return irrespective of whether they report profit or loss.  

Your professional-service scope should address: 

  • Return preparation and filing. 
  • Reconciliation of income and tax information. 
  • Review of deductions and tax adjustments. 
  • Treatment of losses. 
  • Applicable audit reports or other tax filings. 

For FY 2025–26, the department identifies ITR-6 for companies other than those claiming exemption under section 11. Confirm the forms and law applicable to the reporting period rather than carrying old instructions into every future year.  

Action: Ask whether your fee includes only uploading the return or also preparing the tax computation and resolving reconciliation differences. 

Which additional costs depend on your business? 

Not every company needs every compliance service. Applicability should be assessed before pricing the package. 

When should you budget for GST, TDS and payroll work? 

Ask your adviser which obligations apply based on registration, transactions, payments, employees and relevant thresholds. 

Potential services include: 

  • GST return preparation and reconciliation. 
  • TDS calculation, deposit support and return preparation. 
  • Payroll processing. 
  • Applicable professional-tax, EPF or ESI work. 
  • Tax audit or specialised tax reporting. 

Statutory audit and tax audit are different requirements. A company-law audit does not mean a separate income-tax audit is automatically required in every case.  

Action: Request an applicability checklist. Each service should be marked required, not applicable or subject to review. 

Which filings should not automatically be treated as annual? 

Some costs arise only when a condition is met or an event occurs: 

  • ADT-1: Relevant auditor-appointment filing; do not assume a fresh filing is required every year. 
  • DPT-3: Consider where deposit or specified non-deposit reporting applies. 
  • MSME Form I: Consider where the applicable supplier-payment reporting conditions are met. 
  • Director KYC: Check the director’s current compliance cycle. 
  • Director changes: Review filings triggered by appointment or resignation. 
  • Share transactions: Review filings arising from allotment or changes in capital. 
  • Registered-office changes: Assess the applicable process and filing requirements. 

One important update: ICAI’s January 2026 announcement explains that routine annual director KYC was replaced by a three-year cycle effective 31 March 2026. Do not automatically budget it as an annual filing without checking the director’s circumstances.  

Does small-company status reduce compliance costs? 

It can reduce parts of the workload, but it does not mean “no audit” or “no annual filing.” 

The prescribed small-company financial thresholds increased from 1 December 2025 to: 

  • Paid-up share capital not exceeding ₹10 crore. 
  • Turnover not exceeding ₹100 crore, assessed under the applicable definition.  

Both conditions and statutory exclusions must be considered. Holding companies, subsidiary companies, section 8 companies and companies governed by a special Act are excluded from the definition.  

Paid-up capital is not the same as authorised capital. The figure relevant to small-company classification should not be confused with the capital basis used for filing fees. 

Action: Ask your adviser to confirm your classification for the relevant year and explain which simplifications actually apply. 

How are government filing fees different from professional charges? 

A government filing fee is payable under prescribed rules. A professional charge pays for preparing, reviewing, certifying and submitting the documents. 

For standard ROC document filings, the prescribed fee schedule uses nominal share-capital categories. The exact payable amount depends on the form, company and applicable rules.  

When reviewing a quotation, ask: 

  • Are government fees included or billed separately? 
  • Which forms are covered? 
  • Are applicable taxes on professional services additional? 
  • Are certification and document preparation included? 
  • Are corrections or resubmissions chargeable? 
  • Does the quote exclude additional fees for delay? 

Avoid treating a quoted “ROC filing cost” as the government fee alone. 

Action: Ask for separate subtotals for professional charges, government charges and taxes. 

How can you calculate an annual compliance budget? 

Use this planning formula: 

Annual compliance budget = professional services + government fees + recurring accounting and tax work + event-based work + support costs. 

Avoid counting a service twice if it is already part of the annual package. 

What would a hypothetical startup budget look like? 

Assume a small services company receives these quotations: 

  • Core annual package, including statutory audit and accounts preparation: ₹30,000. 
  • Monthly bookkeeping: ₹2,000 × 12 = ₹24,000. 
  • Applicable GST and TDS support: ₹12,000 a year. 
  • Estimated government fees and digital-signature-related expenses: ₹2,000. 

The illustrative budget is ₹68,000, before any applicable tax on professional services and unexpected event-based work. 

These are assumed figures showing the calculation, not verified market rates for each service. Actual government charges and digital signature needs must be checked. 

If bookkeeping or tax support is already included in the ₹30,000 package, remove the corresponding separate amount. 

Action: Turn each quotation into an annual total. Monthly prices can appear small while materially changing the full-year budget. 

How much can late filing add to the cost? 

Delays can create additional filing fees and separate legal exposure. 

The Companies Act’s section 403 framework provides for additional fees of at least ₹100 per day for delayed filings under sections 92 and 137, with amounts prescribed under the rules. Do not apply the same calculation to every MCA form.  

For illustration, where the applicable charge is ₹100 per day per form: 

  • One form delayed by 30 days adds ₹3,000. 
  • Two forms each delayed by 30 days add ₹6,000. 

That illustration excludes normal fees, professional charges and any separately imposed statutory penalties. Payment of an additional filing fee does not automatically remove other liability. 

Action: Track document preparation and sign-off dates before the statutory deadline. Last-minute filing is harder when accounts or signatures are incomplete. 

How can you reduce costs without missing obligations? 

Reduce repeated work and prevent avoidable corrections. 

Useful steps include: 

  • Reconcile bank transactions every month. 
  • Keep invoices and expense evidence organised. 
  • Separate personal and company transactions. 
  • Give your adviser complete information on time. 
  • Review applicability before buying unnecessary services. 
  • Compare providers on the same scope. 
  • Keep filing acknowledgements and final documents. 
  • Review the package when transactions, staffing or ownership change. 

Assign clear responsibility: 

  • The founder supplies business information and approvals. 
  • The accountant maintains records and reconciliations. 
  • The auditor performs the independent audit. 
  • The company-secretarial adviser manages applicable corporate filings. 

Outsourcing helps with execution, but directors should still monitor completion. 

What should you ask before choosing an annual compliance package? 

Request written answers to these questions: 

  • Does the price include statutory audit? 
  • Is bookkeeping included, and what transaction limit applies? 
  • Are annual financial statements and the income-tax return included? 
  • Which ROC filings and supporting documents are covered? 
  • Are government fees and applicable taxes on professional services additional? 
  • Is GST or TDS support included? 
  • What counts as an event-based extra? 
  • Are past-year corrections or notice responses excluded? 
  • Who will perform the audit and certify applicable forms? 
  • Will you receive copies of all submissions and acknowledgements? 

A clearly defined package is easier to compare and budget than a broad “all-inclusive” promise. 

FAQs about annual compliance costs: 

Does a zero-turnover company still have compliance expenses? 

Yes. Zero turnover does not automatically cancel accounting, audit or filing obligations for an ordinary active company. The work may be simpler, but it still needs to be assessed and completed. 

Is statutory audit mandatory for a small private limited company? 

For an ordinary active private limited company compliance, low turnover or small-company status alone does not remove the statutory audit requirement. Do not confuse this with income-tax audit thresholds. 

Is ₹25,000 enough for the entire year? 

It may cover a defined package for a straightforward company. It may exclude bookkeeping, GST, TDS, government fees, taxes, additional filings or backlog work. Check the written scope before relying on the amount. 

Are annual compliance fees fixed by the government? 

Government filing charges are prescribed. Professional fees vary with scope, complexity and the service provider. There is no single government-fixed all-inclusive compliance package price. 

Does an annual package include GST and TDS returns? 

Only if the quotation says so. Confirm filing frequency, transaction limits and reconciliation support. 

Can a company stop filing because it has stopped trading? 

Stopping operations does not automatically end the company’s legal obligations. Ask about continuing compliance, formal dormant status or closure, as appropriate, rather than simply abandoning filings. 

Is director KYC still an annual expense? 

Do not assume so. The routine framework moved to a three-year cycle from 31 March 2026. Confirm the director’s filing history, changes and applicable requirements. 

What is the best way to compare two quotations? 

Compare the same deliverables and annual total. Separate professional fees, government charges, taxes and exclusions, and identify any duplicated services. 

Conclusion 

The annual compliance cost of a private limited company depends on its activity, records, and applicable obligations. Use 25,000 rupees to 60,000 rupees as a starting point for a basic package. Then figure out the services the company needs. 

Before finalising your budget: 

  • Confirm your company classification and applicable filings. 
  • Separate professional fees from government charges and taxes. 
  • Check whether audit, bookkeeping, GST and TDS work are included. 
  • Allow for event-based work and support costs. 
  • Keep your records up, to date and track which filings have been completed. 

An itemised annual quotation gives you a reliable budget. It helps avoid missed responsibilities, duplicate charges and last-minute surprises. 

How to Launch an SME IPO in India: A Step-by-Step Process

How to launch SME IPO in India

To start an SME IPO in India, check if you are eligible to hire a merchant banker who is registered with SEBI; get your company and financial records ready; send the draft offer document to the selected SME exchange; get all the needed approvals and file the required papers; start the issue and finish the allotment and listing. Make sure to create a plan for compliance after the listing is done before you begin the process. 

This path can work for businesses that are already established and for startups that are at a stage where they can get public equity capital. It is not a way to get funding, for a business that has just started. 

What is an SME IPO, and who is it for? 

An SME IPO is a public offering that results in a company being listed on a special platform, for small and medium enterprises like NSE Emerge or BSE SME. Of getting money only from private investors a company sells shares to the public using a controlled and official process. 

An offer can include two different components: 

  • Fresh issue: The company issues new shares and receives the proceeds, subject to issue expenses. 
  • Offer for sale (OFS): Existing shareholders sell their shares and receive the sale proceeds. That portion does not fund the company’s expansion. 

For example, if an IPO includes a ₹24 crore share issue along with a ₹6 crore offer for sale the total money the company gets is ₹24 crore, not ₹30 crore. This is an example, not something that is being planned right now. 

An SME IPO is something to think about if you have a plan for growth financial records that are strong and can be checked and a team that is ready for public reporting. If you need money quickly to deal with cash problems, look at other options at the same time, as you consider the IPO path. 

Is your business eligible for an SME IPO in India? 

Eligibility depends on applicable SEBI regulations and the selected exchange’s criteria. Passing a few financial tests does not establish complete eligibility. 

Which NSE Emerge requirements should you check first? 

NSE’s published general eligibility criteria include the following screening points: 

  • Incorporation: Company incorporated in India under the Companies Act. 
  • Post-issue capital: Paid-up capital at face value of no more than ₹25 crore. 
  • Track record: At least three years through qualifying company, promoter or predecessor business history. 
  • Operating profit: At least ₹1 crore from operations in any two of the previous three financial years. 
  • Net worth: Positive net worth. 
  • Cash flow: Positive free cash flow to equity in at least two of the three preceding financial years. 

These are selected requirements, not the full checklist. Ask the merchant banker to confirm the required financial basis, qualifying history and remaining conditions. 

Does the ₹25 crore limit mean you can raise only ₹25 crore? 

No. The initial SME listing capital ceiling refers to post-issue paid-up capital at face value, rather than the amount collected at the issue price. BSE’s published eligibility document also identifies a ₹25 crore post-issue paid-up capital ceiling. 

For example, issuing 20 lakh shares with a ₹10 face value at ₹100 per share generates ₹20 crore in gross proceeds, while adding ₹2 crore to paid-up share capital. The company must still account for its existing capital and all other eligibility conditions. 

Can startups qualify without meeting the usual requirements? 

Do not assume that being a startup creates an exemption. Have your adviser identify the exact listing route and assess it under current rules before you treat the IPO as a funding option. 

How do you launch an SME IPO step by step? 

Step 1: How should you assess IPO readiness? 

Begin with a written readiness assessment before committing to a launch date. Ask whether the business qualifies, whether its disclosures are supportable, and whether the proceeds will serve a clear purpose. 

Review the following areas: 

  • Financial records: Audited statements and the evidence behind reported figures. 
  • Cash collection: Receivables, payment cycles and cash-flow consistency. 
  • Customer concentration: Dependence on a few customers or contracts. 
  • Legal matters: Disputes, licences and unresolved documentation. 
  • Ownership records: Shareholding history and agreements. 
  • Tax reconciliations: Differences between accounts and tax filings. 
  • Related-party transactions: Dealings with promoters and connected businesses. 

A growing business can still need substantial preparation if its records are inconsistent. 

Action: Create a gap tracker with four columns: issue, evidence needed, responsible person and completion date. Resolve critical gaps before setting the filing timetable. 

Step 2: Who should you appoint to manage the IPO? 

Appoint a SEBI-registered merchant banker with relevant SME issue experience. For an SME IPO, the merchant banker’s work includes due diligence, offer-document preparation, underwriting arrangements and ensuring market-making arrangements. 

The working team will also typically involve: 

  • Auditors to support financial preparation and verification. 
  • Legal advisers to review contracts, disputes and disclosures. 
  • Company-secretarial advisers to coordinate corporate records and filings. 
  • A registrar to the issue to support application and allotment administration. 
  • Relevant banking and depository participants for issue execution. 

An IPO consultant may coordinate readiness and preparation, but that role does not replace the registered merchant banker’s responsibilities. 

Action: Compare scope, professional fees, experience, team capacity and post-listing support. Ask who owns each deliverable and what happens if the transaction is postponed. 

Step 3: How should you prepare the company and its records? 

If your business is a private limited company, plan the conversion to a public limited company with your legal and company-secretarial team. Have them schedule the necessary corporate approvals and filings. 

Next, organise a secure data room containing: 

  • Incorporation documents, constitutional documents and statutory records. 
  • Shareholding history, allotment records and shareholder agreements. 
  • Financial statements, tax records and banking information. 
  • Material contracts, licences, property records and intellectual property documents. 
  • Details of litigation, borrowings and related-party dealings. 

Your advisers should determine which records need restatement, certification or additional supporting evidence. 

Action: Reconcile important figures across accounts, returns and management reports. Maintain one agreed version of each document and log subsequent changes. 

Step 4: How do you choose the exchange and prepare the offer document? 

Evaluate NSE Emerge and BSE SME by comparing: 

  • Current eligibility criteria for the proposed issuer. 
  • Documentation and application requirements. 
  • Exchange fees and other transaction costs. 
  • The company’s financial history and proposed issue structure. 

Avoid assuming their requirements are identical. 

The merchant banker leads preparation of the draft offer document: commonly a draft red herring prospectus for a book-built issue or a draft prospectus for a fixed-price issue. The document explains the business, financial information, risks, ownership, issue structure and intended use of funds. 

A DRHP is a draft red herring prospectus. It supports the review process; filing it does not mean shares are already available for purchase. 

Action: Build evidence behind the business story. If you claim an expanding customer base, support it with records and disclose concentration or retention risks where relevant. 

Step 5: How do exchange review and regulatory filings work? 

Submit the draft offer document and supporting application to the chosen SME exchange through the prescribed process. The exchange reviews the submission, raises queries where necessary and considers in-principal approval. Required offer-document filings with the Registrar of Companies and SEBI also form part of the process. 

Do not describe exchange review as an endorsement of the investment. NSE explicitly distinguishes its review of listing requirements from approval under every applicable law. 

Action: Maintain a query register with the question, proposed response, supporting evidence, owner and due date. Keep responses consistent with the financial and legal disclosures. 

Step 6: How should you plan pricing, dilution and the use of proceeds? 

Work with the merchant banker on the issue structure and pricing approach. Distinguish the funds required by the company from any shareholder sale component. 

Prepare a dilution model before agreeing to an issue size. For example, if founders own all 80 lakh existing shares and the company issues 20 lakh new shares, their combined ownership becomes 80% of the one crore post-issue shares. This simplified illustration excludes other share issuances and shareholder sales. 

Make each funding objective measurable: 

  • Machinery purchases: Support the budget with supplier estimates and an implementation plan. 
  • Working capital: Explain the operating cycle and how the funding requirement was calculated. 
  • Expansion plans: Identify expected milestones and who will oversee delivery. 

Have the merchant banker check whether each proposed objective is permitted under the applicable rules. 

NSE’s published restricted SME IPO criteria prohibit objectives that include repaying loans from promoters, the promoter group or related parties, directly or indirectly. They also cap OFS participation at 20% of total issue size and sales by a selling shareholder at 50% of that shareholder’s holding. 

Action: Request a written check of every proposed use of funds, shareholder sale and relevant lock-in requirement before finalising the structure. 

Step 7: What must be ready before the public issue opens? 

Complete the relevant approvals, offer-document filings, issue arrangements and prescribed disclosures before opening subscriptions. Coordinate the launch timetable with the merchant banker, registrar and exchange. 

NSE states that SME issues must be fully underwritten, with the merchant banker underwriting at least 15% in its own books. It also requires arrangements for market making for at least three years after listing. 

Underwriting is a contractual arrangement addressing subscription shortfalls under agreed terms. Market making involves an authorised participant providing buy and sell quotes to support trading. Neither guarantees a rising share price. 

Action: Agree a communications approval process. Keep public statements consistent with the offer document and avoid promises of returns or listing gains. 

Step 8: What happens after the issue closes? 

After the issue closes, the issue team coordinates: 

  • Reconciliation of applications. 
  • Finalisation of the basis of allotment. 
  • Fund unblocking or refunds, where applicable. 
  • Credit of allotted shares to investor accounts. 
  • Completion of final listing requirements. 

NSE’s published onboarding timetable provides for listing on T+3 working days, where T is the issue-closing day. This timetable concerns the period after subscriptions close; it does not mean the whole IPO can be prepared in three days. 

Action: Confirm the actual allotment, share-credit and trading dates with the issue team and exchange notices. 

Step 9: How should you prepare for life after listing? 

Listing changes how you manage disclosure and accountability. Prepare a compliance calendar covering: 

  • Applicable financial reporting and filing deadlines. 
  • Disclosure of material developments. 
  • Shareholder communication and investor matters. 
  • Insider-trading controls. 
  • Monitoring and reporting of issue proceeds, as applicable. 

Requirements can depend on the company’s circumstances and current rules. NSE provides a separate Emerge compliance calendar rather than leaving issuers to infer obligations from mainboard guidance. 

Action: Assign an owner and backup for each obligation. Run a mock reporting cycle before listing to check that the team can produce accurate information on time. 

How long does an SME IPO take, and what does it cost? 

There is no dependable single timetable for every company. Preparation, audit work, restructuring, exchange queries and launch conditions can change the schedule. 

Ask for a milestone plan that separates: 

  • Readiness assessment and gap resolution. 
  • Financial preparation and offer-document drafting. 
  • Exchange review and responses to queries. 
  • Final filings and public-issue launch. 
  • Allotment, share credits and listing. 

A stated launch target should explain its assumptions and dependencies. 

Likewise, request an itemised cost proposal rather than relying on one package price. 

Also check taxes, reimbursable expenses and withdrawal terms. Compare net usable proceeds with total transaction costs and continuing obligations. 

When should you postpone an SME IPO? 

Consider postponing if: 

  • Eligibility is unresolved. 
  • Accounting records need major repair. 
  • The funding objective is unclear. 
  • Important disclosures lack supporting evidence. 
  • The management team cannot support public reporting. 

Another warning sign is needing the IPO proceeds by a date the business cannot afford to miss. Compare bank finance, private equity or other suitable funding routes while fixing readiness gaps. 

Use a practical decision test: can you show how the capital will improve the business, support the disclosures with evidence, and remain accountable after listing? 

Frequently Asked Questions: 

Is MSME or Udyam registration enough to qualify for an SME IPO? 

No. MSME registration does not mean that the company meets the rules of the securities market. Check the company against the listing rules of the exchange that is being used and the rules set by SEBI. 

Can a startup that is making a loss launch an SME IPO? 

Do not think it can. Operating profit is not the same as profit so look at the exact financial test and the plan with the merchant banker. Check the eligibility checklist above for the points used by NSE Emerge. 

Can a private limited company start the IPO directly?

A private company needs to plan to become a company and get the required approvals before starting the public offer. Let the legal team and company secretary plan the steps for the business. 

Do the company and the selling shareholders get the IPO money? 

No. Money from the issue goes to the company; money from the OFS goes to the selling shareholders. Keep accounts for the related costs. 

Does an IPO consultant take the place of a merchant banker?

No. The consultant can help with preparation and coordination. The merchant banker is still responsible, for managing the issue as required by the rules. 

Does market making ensure that there is trading or that the listing goes up? 

No. It helps with trading by setting prices. It does not guarantee that every shareholder can sell any amount at the price they want or make a profit. 

Is mainboard migration automatic after an SME IPO? 

No. Treat migration as a separate future assessment under the exchange’s rules then in force. Do not present it as a guaranteed result of the initial listing. 

What should a founder do first? 

Prepare recent audited financial statements, the current shareholding structure and a clear funding plan. Request a written eligibility and readiness assessment before committing to an issue date. 

Conclusion 

Launching an SME IPO in India requires preparation across eligibility, financial records, governance, documentation and issue execution. A well-prepared business should understand how much capital it needs, how the issue will affect ownership and what responsibilities continue after listing. 

Before committing to a launch date: 

  • Confirm eligibility for the proposed listing route. 
  • Resolve financial and documentation gaps. 
  • Appoint an experienced SEBI-registered merchant banker.
  • Define the use of proceeds and assess founder dilution.
  • Budget for issue expenses and continuing compliance.
  • Assign responsibility for post-listing reporting.

Start with a written IPO readiness assessment. It gives your board a practical basis for deciding whether to proceed, prepare further or choose another funding route. 

How Long Does SEBI AIF Registration Take? Process, Timeline and Common Delays

How Long Does SEBI AIF Registration Take? Process, Timeline and Common Delays

Quick answer: How long does AIF registration take?

SEBI does not prescribe a guaranteed overall period for granting Alternative Investment Fund registration. As a practical planning estimate, applicants should generally allow approximately three to six months from preparation to receipt of the registration certificate.

The process can take longer—sometimes six months or more—if the application is incomplete, the fund structure is complex, the sponsor or investment manager does not clearly meet regulatory requirements, or responses to SEBI’s queries are delayed.

SEBI’s published guidance states that an applicant will generally receive an initial reply within 21 working days after submitting an application. This does not mean the registration will be granted within 21 working days. The final timeline depends substantially on how quickly and satisfactorily the applicant responds to regulatory requirements and observations. SEBI’s AIF registration guidance

Understanding SEBI AIF registration

An Alternative Investment Fund, or AIF, is a privately pooled investment vehicle that collects capital from sophisticated investors and invests according to a defined investment policy.

AIFs in India are regulated under the Securities and Exchange Board of India (Alternative Investment Funds) Regulations, 2012. The regulations were most recently amended on July 14, 2026. Current SEBI AIF Regulations

An applicant may seek registration under one of three broad categories:

  • Category I AIF: Includes venture capital funds, infrastructure funds, social impact funds and other funds considered economically or socially desirable.
  • Category II AIF: Commonly includes private equity funds, debt funds and other funds that do not undertake leverage except for permitted operational requirements.
  • Category III AIF: Includes funds that may use complex trading strategies and leverage, subject to applicable conditions.

The category selected affects the fund’s investment strategy, regulatory obligations and the information SEBI may examine during registration.

Estimated SEBI AIF registration timeline

A well-prepared AIF registration can be divided into the following stages:

Registration stageIndicative time
Fund planning and category selection1–2 weeks
Formation of the fund and manager entities2–4 weeks
Drafting legal and regulatory documents3–6 weeks
Filing the application on the SEBI portal2–5 working days
Initial review or communication from SEBIGenerally within 21 working days
Responding to SEBI observations2–8 weeks or longer
In-principle approval and payment of fees1–3 weeks
Grant of registration certificateDepends on satisfactory compliance
Typical end-to-end planning estimate3–6 months

These periods are planning estimates, not statutory guarantees. Several stages may also run simultaneously.

Stage 1: Planning the AIF structure

Estimated time: One to two weeks

The registration journey begins before any application is filed. The sponsor and proposed investment manager must first determine:

  • The investment objective of the fund
  • The appropriate AIF category and subcategory
  • The legal structure of the fund
  • Target investors
  • Proposed fund corpus
  • Sponsor commitment
  • Management and governance structure
  • Investment and exit strategy
  • Proposed tenure of the scheme
  • Whether the fund will use borrowing or leverage
  • Key service providers

An AIF may generally be established as a trust, company, limited liability partnership or body corporate. In practice, many Indian AIFs use a trust structure, but the correct structure depends on taxation, governance, investor expectations and the commercial model.

Making major changes after the application has been submitted can lead to additional questions, document revisions and delays. It is therefore important to finalise the commercial and legal structure at the beginning.

Stage 2: Establishing the fund and investment manager

Estimated time: Two to four weeks

Once the structure has been selected, the relevant entities and arrangements must be established. Depending on the chosen structure, this may include:

  • Formation of the trust, company or LLP
  • Execution and registration of the trust deed
  • Incorporation or establishment of the investment manager
  • Appointment of the trustee, where applicable
  • Finalisation of ownership and control
  • Appointment of directors, partners or designated partners
  • Establishment of an appropriate office and operational infrastructure
  • Opening of bank accounts
  • Obtaining PAN and other registrations
  • Preparation of board or partner resolutions

The exact time will depend on the legal form, availability of documents, name approvals and coordination among the sponsor, manager, trustee and professional advisers.

Stage 3: Preparing the AIF registration documents

Estimated time: Three to six weeks

Documentation is frequently the most demanding stage of the AIF registration process. SEBI examines more than the existence of the fund entity. It also considers whether the proposed sponsor and manager are suitable, adequately experienced and capable of operating a regulated investment fund.

The application package may include:

  • Form A
  • Constitutional documents of the applicant
  • Trust deed, LLP agreement or memorandum and articles of association
  • Details of the sponsor and investment manager
  • Shareholding and ownership structure
  • Financial statements and net-worth evidence
  • Details of directors, partners and key investment personnel
  • Professional qualifications and investment-management experience
  • Infrastructure and staffing details
  • Disciplinary and litigation declarations
  • Investment strategy and risk-management framework
  • Draft Private Placement Memorandum
  • Compliance policies
  • Due-diligence declarations and supporting documents
  • Details of affiliates and group entities

SEBI’s January 2025 registration FAQs provide an application checklist and explain that applications must be filed through the SEBI Intermediary Portal. The stated application fee is ₹1,00,000 plus applicable GST. SEBI FAQs for grant of AIF registration

Registration fees payable after approval vary according to the AIF category. Applicants should verify the latest fees and applicable taxes at the time of filing.

Stage 4: Filing the application with SEBI

Estimated time: Two to five working days after the documents are ready

The applicant must submit the registration application through the SEBI Intermediary Portal. The applicant receives login credentials and uses the “Fresh Registration” option under the AIF section to complete the filing.

Before submission, applicants should verify that:

  • Form A is complete and consistent
  • Names and addresses match constitutional records
  • Supporting documents are properly executed
  • Financial information is updated
  • The AIF category matches the proposed investment strategy
  • Sponsor and manager details are fully disclosed
  • The Private Placement Memorandum is consistent with the application
  • The application fee has been paid correctly
  • Required declarations have been signed by authorised persons

Even a technically minor inconsistency can result in a regulatory query. For example, different descriptions of the investment strategy in Form A and the PPM may require clarification or revision.

Stage 5: SEBI’s initial review

Indicative response: Generally within 21 working days

SEBI’s published guidance states that an applicant will generally receive a reply within 21 working days of submitting the application. Applicants should interpret this carefully.

The 21-working-day period generally relates to an initial regulatory communication. SEBI may:

  • Seek additional information
  • Point out missing documents
  • Ask for clarification of the investment strategy
  • Request changes to the fund structure
  • Examine the experience of key personnel
  • Seek evidence of the manager’s operational capabilities
  • Ask questions about affiliates or past business activities
  • Require revisions to the PPM
  • Seek clarification about sponsor commitment or net worth

Therefore, receiving a reply within 21 working days is not the same as obtaining final registration within that period.

Stage 6: Responding to SEBI observations

Estimated time: Two to eight weeks, but potentially longer

This stage has the greatest influence on the overall registration timeline. The speed of approval often depends on the quality of the application and the applicant’s ability to respond quickly and accurately.

A strong response should:

  • Address every observation separately
  • Use clear and direct language
  • Include revised documents where required
  • Highlight changes made in each document
  • Ensure that all revised documents remain consistent
  • Include supporting evidence rather than unsupported statements
  • Be approved by the relevant sponsor, manager or governing body before submission

If the first response is incomplete, SEBI may issue another round of observations. Multiple rounds of queries can extend the registration timeline considerably.

Applicants should maintain a central response tracker showing each SEBI observation, the proposed response, the responsible person, required supporting documents and submission status.

Stage 7: Approval, registration fee and certificate

Once SEBI is satisfied that the applicant meets the regulatory requirements, it may approve the application and ask the applicant to pay the applicable registration fee.

After payment and completion of the required formalities, SEBI may grant the certificate of registration.

The fund must ensure that its subsequent activities remain within the scope of the category and conditions under which registration was granted.

Does the GARUDA mechanism make AIF registration faster?

SEBI introduced the Green-Channel: AIF Rollout Upon Document Acknowledgement, or GARUDA, mechanism through a circular dated July 30, 2026. The mechanism is intended to streamline the processing and launch of AIF schemes by relying more heavily on prescribed due diligence and declarations. SEBI GARUDA circular

However, applicants should distinguish between:

  1. Registration of the AIF itself; and
  2. Filing and processing of the scheme’s Private Placement Memorandum.

GARUDA primarily relates to the processing and rollout of schemes. It does not mean that every new AIF registration will automatically be completed within a fixed green-channel period.

For the first scheme, scheme launch remains connected to the grant of AIF registration. Accordingly, the applicant must still satisfy SEBI regarding its eligibility, structure, sponsor, manager, key personnel and other registration requirements.

What can delay SEBI AIF registration?

1. An incomplete application

Missing annexures, unsigned documents, outdated financial statements or incomplete declarations commonly lead to additional observations.

2. Inconsistency between documents

SEBI may seek clarification if Form A, the trust deed, investment management agreement and PPM describe the fund differently.

3. Unclear investment strategy

Broad statements such as “investing in growth opportunities” may not adequately explain the proposed asset classes, sectors, investment stages, geography, risk controls and exit strategy.

4. Insufficient experience of the investment team

SEBI may examine whether the investment manager and key personnel possess suitable professional qualifications and relevant experience.

5. Complex ownership structures

Multiple layers of holding companies, foreign shareholders or unclear beneficial ownership may increase the level of regulatory scrutiny.

6. Sponsor or manager eligibility issues

Questions concerning net worth, fit-and-proper status, prior regulatory matters, litigation or disciplinary history can lengthen the review.

7. Weak operational readiness

The manager must demonstrate that it has adequate infrastructure, personnel, compliance arrangements and systems to manage the AIF.

8. Delayed responses to SEBI

If the applicant takes several weeks to respond to each observation, the registration process will naturally take longer.

9. Frequent commercial changes

Changing the fund category, sponsor, manager, investment strategy or legal structure during regulatory review may require substantial revisions.

10. Deficiencies in the PPM

Inaccurate, incomplete or inconsistent disclosures in the Private Placement Memorandum can delay the process and create regulatory risk.

How can applicants complete AIF registration faster?

No consultant or applicant can guarantee a specific approval date because registration remains subject to SEBI’s review. However, the following steps can reduce avoidable delays:

Complete a regulatory readiness assessment

Review the sponsor, manager, key personnel, ownership structure and investment proposal against the applicable AIF requirements before filing.

Finalise the structure early

Select the fund category, legal structure, investment strategy, sponsor and manager before preparing the application.

Use a comprehensive document checklist

Create a checklist based on the latest SEBI regulations, master circulars, FAQs and portal requirements.

Keep all documents consistent

Use identical descriptions of the fund, parties, strategy, tenure, corpus and governance arrangements throughout the application.

Prepare for regulatory questions

Anticipate questions about the investment team, sponsor commitment, track record, beneficial ownership, risk management and conflicts of interest.

Assign a dedicated response team

A single team should coordinate information from legal, tax, finance, compliance and investment professionals.

Respond promptly and completely

A fast but incomplete response may create another round of questions. The objective should be to provide one comprehensive and well-supported response.

Can an AIF start raising money before receiving registration?

A proposed AIF should not represent itself as a SEBI-registered AIF before receiving its registration certificate.

Scheme launch and circulation of the PPM must also follow the applicable regulatory framework. The exact requirements may differ for regular schemes, accredited-investor-only schemes, angel funds and large value funds for accredited investors.

Applicants should examine the latest regulations and SEBI circulars before approaching investors or circulating offering documents.

Practical example of an AIF registration timeline

Consider a Category II private equity fund with an Indian sponsor and investment manager:

  • Weeks 1–2: The promoters finalise the fund structure, target corpus, investment strategy and key team.
  • Weeks 3–5: The fund entity and investment manager arrangements are established.
  • Weeks 4–8: Form A, constitutional documents, compliance policies and the PPM are prepared.
  • Week 9: The application is submitted through the SEBI portal.
  • Weeks 10–13: SEBI conducts its initial review and communicates observations.
  • Weeks 14–16: The applicant prepares and submits a detailed response.
  • Weeks 17–20: Additional clarifications, if any, are addressed.
  • Weeks 21–24: Approval, payment of registration fees and issuance of the certificate may follow, subject to SEBI’s satisfaction.

In this example, the overall process takes approximately five to six months. A simpler, exceptionally well-prepared application may move faster, while a complex application involving multiple observations may take longer.

Is there a guaranteed SEBI AIF registration timeline?

No. SEBI does not guarantee that every AIF registration application will be approved within a fixed number of days.

The regulator’s published guidance refers to an initial reply generally being issued within 21 working days. The final registration period depends on the completeness of the application, the complexity of the structure and the applicant’s speed in satisfying regulatory requirements.

Applicants should be cautious of anyone promising guaranteed approval within 21 days or any other fixed period.

Conclusion

A realistic timeline for completing SEBI AIF registration is generally three to six months, including preparation, filing, regulatory review, responses and approval formalities. Complex applications may take longer.

The most effective way to reduce delays is to submit a complete, consistent and well-supported application from the outset. Sponsors and fund managers should finalise their structure early, prepare clear disclosures and maintain a dedicated team for responding to SEBI observations.

BIATConsultant assists fund sponsors and investment managers with AIF structuring, document preparation, SEBI registration support, regulatory coordination and post-registration compliance. Professional preparation can help applicants identify potential issues before filing and move through the review process more efficiently.

Disclaimer: This article is intended for general informational purposes and does not constitute legal, tax, investment or regulatory advice. SEBI regulations, circulars, fees and portal requirements may change. Applicants should review the latest official requirements and obtain professional advice based on their proposed fund structure.

Frequently Asked Questions

How many days does SEBI take to register an AIF?

SEBI does not specify a guaranteed overall approval period. Its published guidance states that an applicant will generally receive an initial reply within 21 working days. Final registration may practically take around three to six months, depending on the application and responses to observations.

Can SEBI AIF registration be completed in one month?

It is generally not advisable to plan on completing the entire process in one month. Preparation of the entities, documents and PPM itself may take several weeks, followed by SEBI’s review and possible queries.

Why does AIF registration take several months?

The process involves scrutiny of the applicant, sponsor, investment manager, key personnel, fund structure, investment strategy, financial resources, regulatory history and offering documents.

What is the fastest way to obtain AIF registration?

The best way to avoid delay is to finalise the structure early, prepare a complete application, maintain consistency across all documents and respond comprehensively to SEBI’s observations.

Does the 21-working-day period mean automatic approval?

No. The period mentioned in SEBI’s guidance relates to a general response after receiving the application. It is not an automatic or guaranteed approval timeline.

Does the AIF category affect the registration timeline?

Yes. The category and strategy may affect the nature of SEBI’s review. Category III structures, complex strategies, leverage arrangements and unusual ownership structures may require additional explanation.

How long does Category II AIF registration take?

A Category II AIF should generally budget approximately three to six months for the complete process. The actual duration depends on documentation quality, structure and regulatory observations.

How long does Category III AIF registration take?

Category III registration may take three to six months or longer where the proposed strategy, leverage, risk controls or operational framework requires detailed review.

Can an AIF launch its first scheme immediately after filing?

Not necessarily. For a first scheme, launch remains linked to receipt of AIF registration and satisfaction of the applicable PPM filing requirements. Applicants must follow the latest SEBI regulations and circulars.

Is professional assistance mandatory for AIF registration?

Engaging a consultant is not, by itself, a substitute for meeting SEBI’s requirements. However, legal, tax, compliance and regulatory professionals can help structure the fund, prepare consistent documents and manage regulatory observations effectively.

AIF Registration in India: Step-by-Step Process Explained

Hedge Fund AIFs: A Closer Look at Category III Funds

Introduction

India’s alternative investment fund market is grown significantly over the last few decades , making Alternative Investment Funds (AIFs) is one of the most preferred investment for the private firms, ventures, hedge funds and the institutional investors. To operate this legally in India, this AIF must contain registration from the Securities and Exchange Board of India (SEBI) SEBI (Alternative Investment Funds) Regulations, under 2012.

If you want plan for launching an investment fund in India, the understanding of AIF registration process is most important element for understanding AIF. This guide explains each step by step in detail.

What is an Alternative Investment Fund (AIF)?

An Alternative Investment Fund (AIF) is a specialized investment vehicle that pools capital from multiple investors to invest in non-traditional asset classes, such as private equity, real estate, hedge funds, venture capital, and commodities. These funds are typically managed by professional fund managers and are structured as limited partnerships or limited liability companies.

AIFs can be structured as:

  • Trusts
  • Limited Liability Partnerships (LLPs)
  • Companies
  • Body Corporates

These are the funds which are regulated by SEBI and are generally used for the investments in startups, private companies, infrastructure projects, real estate, private equity, venture capital, debt instruments, and hedge fund strategies.

Categories of AIFs in India

Before starting any registration process the fund managers has to choose the appropriate AIF category according to need.

Category I AIF

These are AIFs that invest on start up and early stage venture , small and medium enterprises , infrastructure . AIFs I also Include investment in social and economically desire group. Category I considered to have moderate risk and low regulatory restriction compare to other AIFs categories.

Examples:

  • Venture Capital Funds
  • Angel Funds
  • Infrastructure Funds
  • SME Funds
  • Social Venture Funds

Category II AIF

These are AIFs that do not fall under both categories AIFs I and AIFs II . This category known for moderate risk and uncertainites for investment . These category include private Equity funds , debt funds , and funds invest in real state among India.

Examples:

  • Private Equity Funds
  • Debt Funds
  • Fund of Funds

Category III AIF

Category III Use complex stragies for These are AIFs that use complex trading strategies and leverage to generate high returns for investors, such as hedge funds, among others.

Step-by-Step AIF Registration Process in India

Step 1: Determine the Fund Structure

The first step is decide the legal structure of the fund for investment process.

And determining whether the funds fall in which category either is category I , II, Or III . Choosing the correct category is critical because regulatory requirements differ for each category.

You must:

  • Create the trust, LLP, or company
  • Draft constitutional documents
  • Obtain PAN and other registrations
  • Establish the investment management entity

SEBI reviews the legal structure carefully before granting approval.

Step 2: Select the Appropriate AIF Category

The second step is to determine whether the the fund falls under which is it Category I, Category II, or Category III.

The category affects investment restrictions, compliance requirements, and operational guidelines. Selecting the correct category at the beginning helps avoid regulatory complications later.

Step 3: Appoint the Sponsor and Investment Manager

Every AIF requires a sponsor and an investment manager for the analyising of funds.

The sponsor establishes the fund and contributes the required continuing interest, while the investment manager is responsible for managing investments and making portfolio decisions.

SEBI reviews the qualifications, experience, and regulatory track record of these entities during the registration process.

Step 4: Draft the Private Placement Memorandum (PPM)

The Private Placement Memorandum (PPM) is one of the most important documents for the AIF registration in India.

It contains key information such as:

  • Investment strategy for the investors
  • Risk factors and uncertainty
  • Governance structure
  • Fee structure
  • Investor rights
  • Exit mechanisms

A well-drafted PPM improves transparency and increases the likelihood of regulatory approval.

Step 5: Prepare Documentation

The Applicants must have all the documents which are needed for the investment before filing the application.

Common documents include:

  • Trust Deed or LLP Agreement
  • Certificate of Incorporation
  • PAN card details
  • Bank account details
  • Sponsor information
  • Investment manager details
  • Financial statements
  • Compliance declarations
  • Private Placement Memorandum

Accurate documentation helps prevent delays during SEBI review.

Step 6: Submit the Application to SEBI

This is one of the most important key element of the AIFs registration because application is officially submitted and the review as well as approval will be done SEBI. The application for AIF registration is submitted through SEBI’s online intermediary portal. The document should well prepared for the delay of registration.

The applicant must complete Form A, upload supporting documents, and pay the applicable fees.

Once submitted, SEBI begins its review process.

Step 7: Respond to SEBI Queries

Before the approval the SEBI may seek clarifications regarding the fund structure, investment strategy, governance framework, or the documentation.

Timely and accurate responses are essential for smooth approval.

Step 7: Respond to SEBI Queries

These is the final step SEBI will ask for the document clarification regarding several step for the investment. Respond to SEBI Queries objective is to ensure that the proposed Alternative Investment Fund complies with all regulatory requirements and adequately protects investor interests. In these several Queries may ask :

Asking for the missing documents , clarification regarding the fund structure, Investors protection, Governance and compliance framework concern.

How Long Does AIF Registration Take?

The time taken for AIF registration process depends on the situation of complexity of the application and the quality of documentation that has been submitted.

In most cases:

  • Fund Structuring: 2–4 Weeks
  • Documentation Preparation: 3–6 Weeks
  • SEBI Review: 4–12 Weeks
  • Final Approval: 2–4 Weeks

Most AIF registrations are completed within 2 to 8 months.

Conclusion

AIFs is very important crucial step for every fund manager , venture capital funds ,private equity funds and investment professionals looking to establish a regulated investment platform in India. By selecting the best AIFs category , fund structure , preparing all the documents and analysing the document which is needed for the AIFs registration process. By selecting the appropriate fund structure, preparing robust documentation, drafting a comprehensive PPM, and complying with SEBI regulations, applicants can successfully launch and operate an Alternative Investment Fund.

Frequently Asked Questions (FAQs)

What is a SEBI AIF Registration?

An Alternative Investment Fund that has registered with the Securities and Exchange Board of India (SEBI) is known as a SEBI AIF Registration. AIFs are investment vehicles that invest in assets such as private equity, venture capital, real estate, and debt securities.

What is AIF Registration?

All the registration process are done and approval from the SEBI is most important . In these approval from SEBI to establish and operate an Alternative Investment Fund in India.

Is SEBI Registration Mandatory for AIFs?

Yes, it is very important in every Alternative investment funds, and must be register with SEBI.

Who Can Register an AIF in India?

A Trust, LLP, Company, or Body Corporate can apply for AIF registration subject to SEBI regulations.

How Long Does AIF Registration Take?

It takes almost 2-8 months according to document submission to SEBI. If any document is not missing it will approve soon.

What is a Private Placement Memorandum (PPM)?

A PPM is a legal document that outlines the fund’s investment strategy, risks, fee structure, governance, and investor rights.

What Are the Benefits of AIF Registration?

AIF registration provides regulatory recognition, investor confidence, fundraising opportunities, and a structured framework for managing investments.